
CGTN Spanish: Xi Jinping: China and the U.S. can find the right way for our two major countries to get along on this planet we both call home
Source: PR Newswire
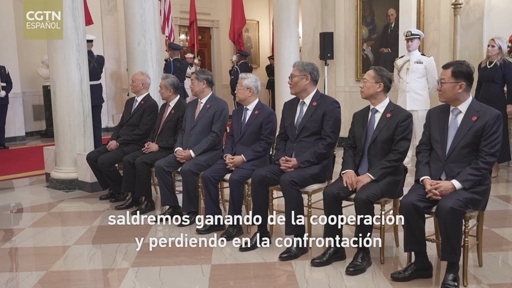
Chinese President Xi Jinping and U.S. President Donald Trump emphasized that both countries benefit from cooperation and lose from confrontation during Xi's September 24 White House state visit. Xi said competition should remain healthy and bounded, with both sides maintaining guardrails to avoid conflict. The remarks signal a constructive tone in U.S.-China relations, though the report cites no specific trade, tariff, technology, or investment agreements.
Analysis
The market-relevant variable is not diplomatic tone but whether follow-on communiques alter tariff schedules, export-control enforcement, outbound-investment restrictions, or procurement access. In the absence of those specifics, a broad China-risk relief rally would be vulnerable to reversal: SPDR S&P China ETF (GXC), iShares China Large-Cap ETF (FXI), Apple (AAPL), and industrial exporters could re-rate on reduced tail risk, but their earnings estimates should not change materially. Near-term beneficiaries of lower headline risk would likely include semiconductor equipment and consumer-electronics supply chains; the more durable upside sits with companies whose China revenue is constrained by policy rather than weak end demand.
Over 1-3 months, the key catalyst is whether talks produce measurable relief around advanced-chip rules or reciprocal tariff exemptions. That would be incrementally positive for Qualcomm (QCOM), Texas Instruments (TXN), Applied Materials (AMAT), Lam Research (LRCX), and KLA (KLAC), although equipment names retain substantial regulatory risk because U.S. restrictions are structural and unilateral enforcement can tighten without a bilateral breakdown. A credible détente would be comparatively negative for domestic-substitution beneficiaries such as Chinese semiconductor and automation suppliers, while reduced supply-chain fragmentation could temper the strategic premium embedded in Mexico industrial/logistics exposures.
Contrarian view: the first-order equity response may overstate the probability of policy normalization. Competition in AI, advanced semiconductors, critical minerals, Taiwan, and defense supply chains is unlikely to be resolved by a high-level meeting; businesses will continue dual-sourcing and carrying higher inventory buffers over the next 6-18 months. Falsification of the cautious stance would be a written agreement with implementation dates, specific licensing or tariff relief, and subsequent upward revisions to China-exposed revenue guidance; renewed export-control actions or tariff threats would quickly reverse any relief trade.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Key Decisions for Investors
- Do not chase a broad FXI/GXC rally on rhetoric alone. Use a signed, implementable policy announcement as the trigger; absent that, maintain neutral China beta because a headline reversal can erase the move within days.
- Set a 1-3 month conditional long basket of QCOM, TXN, AMAT, LRCX, and KLAC only if export-license language or tariff exemptions are specified. Target a 10-15% relative upside versus SOXX from multiple expansion; exit on new Commerce Department restrictions or company guidance indicating China revenue deterioration.
- For existing AAPL exposure, retain rather than add aggressively: reduced geopolitical-risk discount is helpful, but the relevant earnings catalyst is an observable improvement in China demand and supply-chain certainty. Add only following evidence in channel checks or management commentary; downside remains renewed tariff escalation or consumer nationalism.
- Consider a tactical pair after any indiscriminate détente rally: long SOXX versus short FXI over 3-6 months. U.S. semiconductor leaders retain superior earnings quality and AI demand support, while FXI remains more exposed to domestic Chinese growth, property, and policy uncertainty; close if bilateral measures explicitly reopen high-end technology trade.
More News
- Iran awaits US move after WSJ report says Trump rejects peace plan
- Iran says it awaits US response on seven-day roadmap to end war
- Boom or bust? The case for and against panicking about 5% yields
- Arming Taiwan an important US interest, Taipei official says after Trump-Xi summit
- What would a US diesel export ban mean for global fuel prices?
- US, Iran Explore Phased Hormuz Deal