
Tempus Realty Partners Announces $66 Million Office Acquisition in Hopkins, Minnesota
Source: PR Newswire
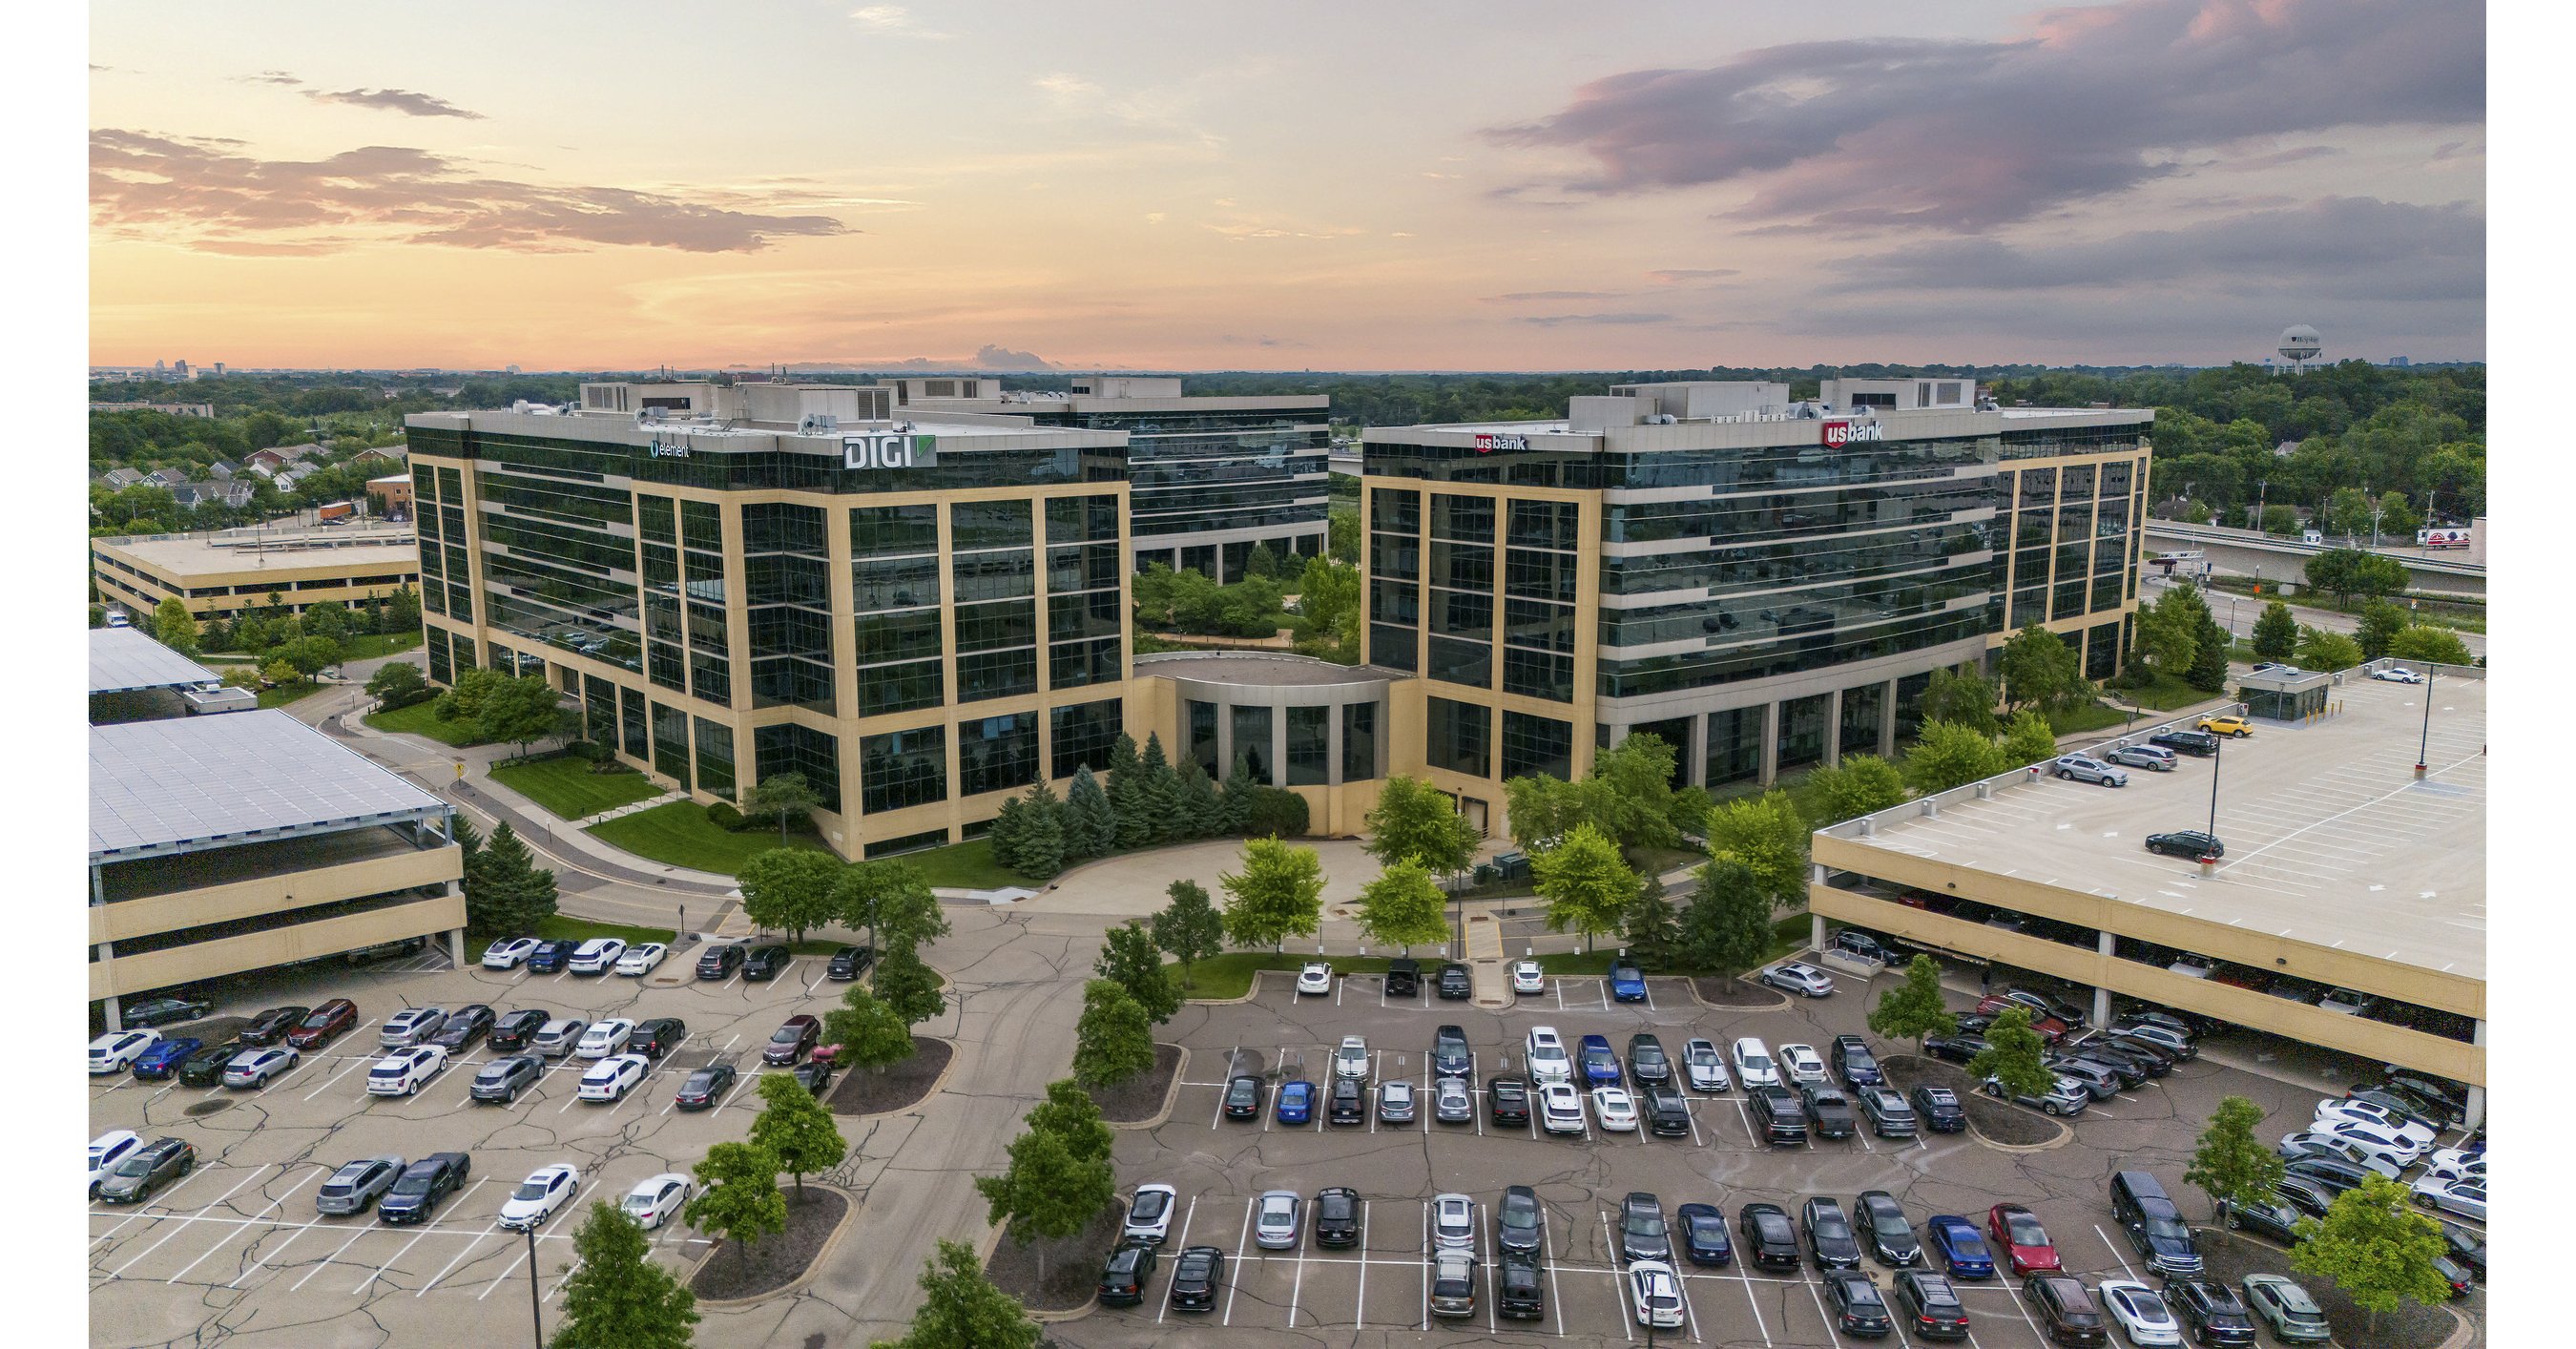
Tempus Realty Partners acquired the 546,548-square-foot Excelsior Crossings Class A office campus in Hopkins, Minnesota, for $66 million. The property is 98% leased, with U.S. Bank occupying 54% of the space and four other headquarters tenants in the second building. Tempus cites an attractive acquisition basis and a niche recovery in Class A office demand, supported by more than $1.4 million of recent capital upgrades.
Analysis
At roughly $121/sq. ft., the transaction is more informative as a private-market price-discovery point than as a direct earnings event for USB, DGII, or EFN. The basis implies institutional-quality suburban office assets with credit tenancy can still clear at a substantial discount to replacement cost, potentially supporting NAV marks for similarly located, highly leased assets held by office REITs. It does not validate a broad office recovery: the asset’s tenant concentration, amenity profile, and location make it materially non-comparable to commodity downtown office inventories.
For USB, the relevant signal is modestly positive for operational continuity but immaterial to consolidated P&L; its real estate footprint remains a potential efficiency lever if hybrid-work utilization weakens. DGII and EFN face no meaningful read-through unless the acquisition precedes lease renewals or expansion commitments, which would provide a more credible indicator of local employment and space demand. The purchaser's claimed upside cannot be independently assessed without in-place rent, lease-expiry schedule, financing terms, and cap rate; leverage is especially important because higher refinancing costs can erase the benefit of a low basis.
The contrarian takeaway is that selective private capital may be creating a floor for top-quartile suburban campuses while public office REIT valuations continue to embed broad distress. That spread is investable only where public vehicles own comparable assets and have manageable 2027-28 debt maturities; indiscriminate long office exposure remains premature. A near-term reversal would be signaled by major tenant downsizing, sublease additions in the I-394 corridor, or a financing structure requiring aggressive rent growth to meet debt service.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Ticker Sentiment
Key Decisions for Investors
- No standalone trade in USB, DGII, or EFN: estimated earnings sensitivity is de minimis, and the announcement lacks lease and financing data needed to establish a valuation catalyst.
- Monitor comparable suburban-office transactions over the next 1-3 months for cap rate and debt-cost disclosure; a sequence of sales below replacement cost but at stable cap rates would support a selective long basket of well-capitalized office REITs with high-quality suburban exposure rather than broad office ETFs.
- Maintain a relative-value bias toward high-occupancy, amenity-rich suburban office assets versus commodity CBD office exposure over 6-18 months; avoid or hedge issuers with large 2027-28 refinancing needs until transaction pricing demonstrates that lenders will underwrite post-maturity cash flows.
- Set an alert for any U.S. Bank lease renewal, contraction, or relocation disclosure. A material reduction by the anchor tenant would invalidate the asset-quality signal and reinforce downside risk for concentrated suburban-office valuations.
More News
- South Korean solar stocks jump as curbs on Chinese sector expected to remain in place
- Paramount will need to release way more movies to make this merger work
- How Kevin Warsh’s rate hike exposed a 2-speed U.S. economy, with AI and housing at the poles
- Meta is breaking out after introducing Muse AI agent. Where the stock is going, according to the charts
- China Vanke shares surge on report of regulatory debt intervention
- Heidi CEO on AI in Healthcare, $900M valuation