
CordenPharma nomme le Dr Jean-Luc Herbeaux au poste de directeur général pour mener la prochaine phase de croissance
Source: PR Newswire
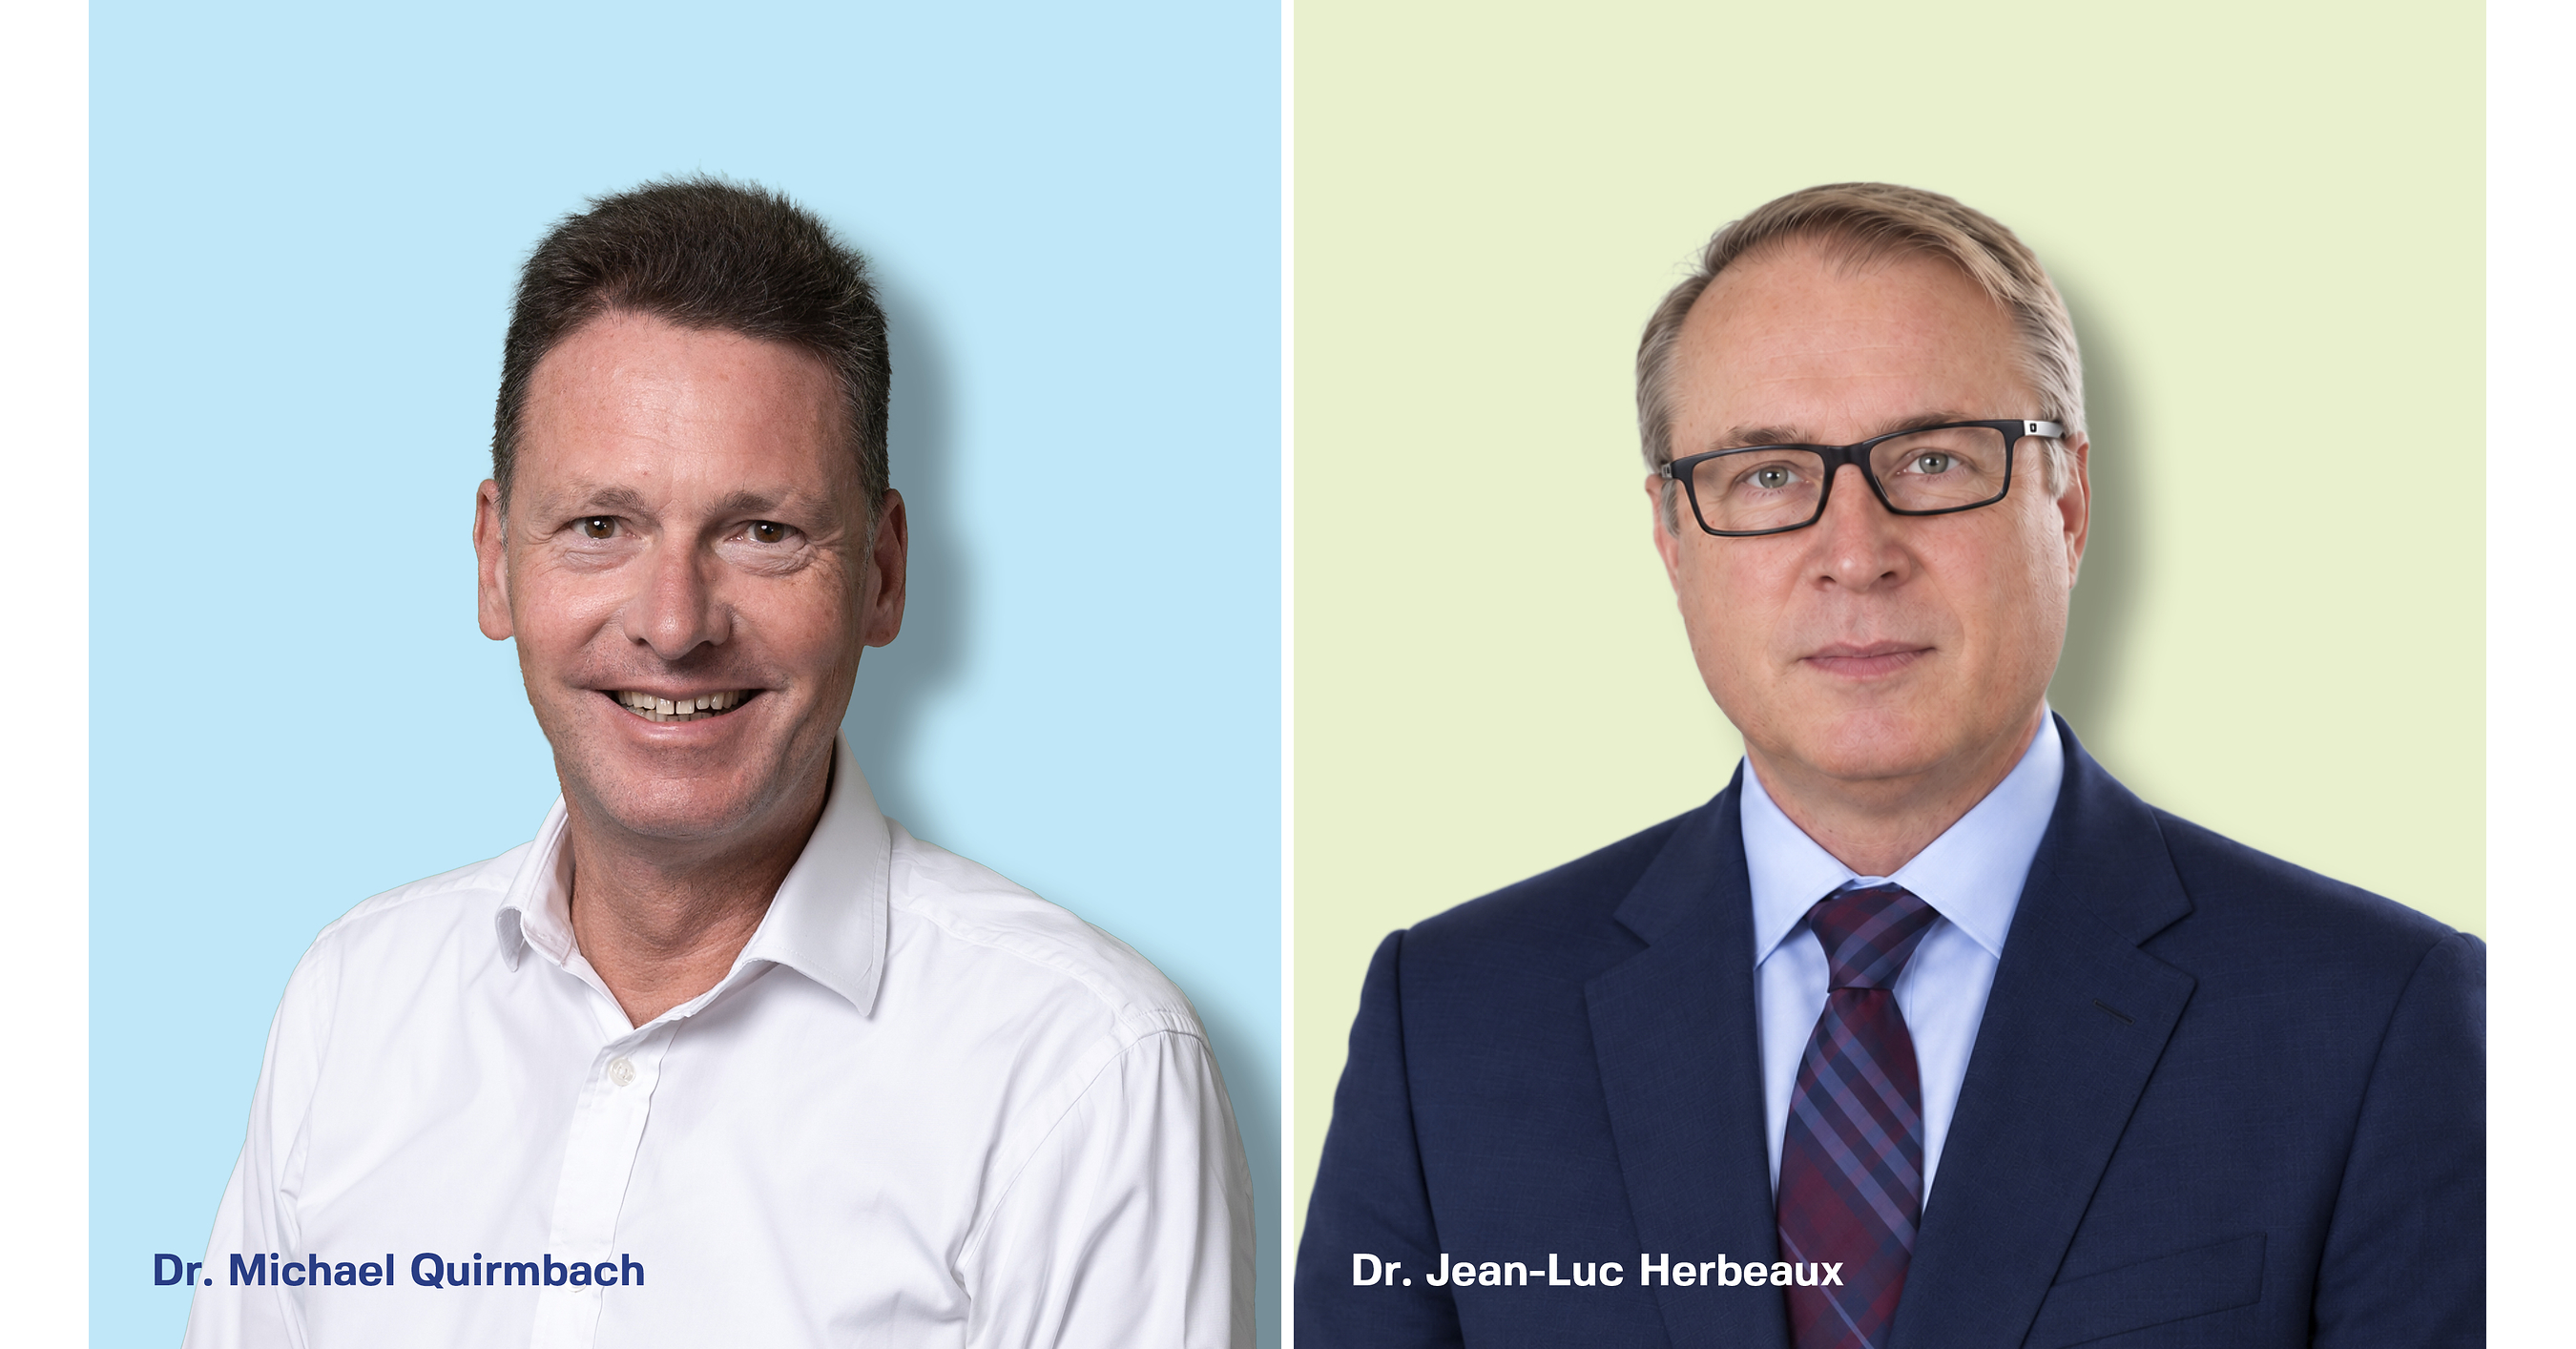
CordenPharma appointed Dr. Jean-Luc Herbeaux as CEO effective October 1, 2026, succeeding Dr. Michael Quirmbach, who will remain a board member and senior adviser. The planned transition follows substantial expansion under Quirmbach, during which annual revenue grew from €245 million to more than €1 billion over 12 years; the company reported €960 million of FY2025 revenue. Herbeaux, formerly Hovione CEO, will execute CordenPharma’s growth strategy following its AmbioPharm acquisition and continued global manufacturing-capacity investments, backed by private-equity owner Astorg.
Analysis
This is not a direct EVK earnings catalyst, but it modestly improves the read-through on CDMO demand for complex modalities. Herbeaux's operating background suggests CordenPharma is likely to compete more aggressively on execution, capacity utilization and integrated customer offerings rather than purely on scientific differentiation. That raises competitive pressure for large public CDMOs with overlapping peptide, oligonucleotide and lipid-delivery capabilities, including Lonza (LONN.SW), Siegfried (SFZN.SW) and Cambrex-owner Permira's private platform; EVK's exposure is more indirect through pharma-services and specialty-input demand.
The investable second-order issue is whether another PE-backed CDMO moves from expansion to a monetization posture. A new CEO following substantial capacity investment often precedes tighter KPI discipline, bolt-on M&A or preparation for a strategic sale/IPO over the next 12-24 months. If CordenPharma prioritizes utilization and pricing to support an exit valuation, it could temper industry-wide price competition; if it instead pursues share gains through capacity-led contracting, public peers with weaker utilization could see margin pressure before revenues are affected.
Near term, no listed-equity trade is justified from a planned leadership transition alone. The relevant 1-3 month datapoints are customer wins, incremental peptide/oligonucleotide capacity announcements, and the integration economics of AmbioPharm. The thesis turns negative for public CDMO peers if CordenPharma discloses materially discounted long-term contracts or aggressive greenfield expansion; it turns supportive if management emphasizes return thresholds, capacity rationalization, or inorganic growth financed by Astorg.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Key Decisions for Investors
- No immediate EVK position change: the company-specific linkage is insufficient and the structured signal is neutral. Reassess only if EVK identifies CordenPharma as a material customer, supplier, or competitor in pharma-services disclosures.
- Place a 90-day monitoring alert on LONN.SW and SFZN.SW for bookings, utilization commentary and peptide/oligonucleotide pricing. A deterioration in pricing or order visibility attributable to competitive capacity would favor a tactical short basket versus a defensive pharma-services index.
- For private-markets exposure, flag CordenPharma as a potential 12-24 month exit candidate. Monitor debt refinancing, carve-out reporting, management incentive-plan changes and acquisition pacing; these are more actionable valuation signals than the CEO transition.
- Do not chase a broad CDMO long on this news. Upgrade only if sector peers report sustained backlog conversion and stable pricing alongside evidence that new complex-modality capacity is earning returns above cost of capital.
More News
- BlackRock’s Fink, Blackstone’s Gray Back Carney’s Canada Investment Push
- Exclusive-Malaysia talks to rival airlines as it monitors AirAsia’s financial health, sources say
- Factbox-Private equity, foreign investors fuel Aussie M&A activity in 2026
- Australia’s Reliance Worldwide agrees to Brookfield’s $2.9 billion buyout bid
- Push for AI regulation mounts as talk of AI’s ‘existential’ risks go mainstream. But Trump resists calls for a slowdown
- Wells Fargo sees improvement in a key metric — plus, Lilly gets praise beyond GLP-1s