
E&R Engineering inaugurará una nueva planta en Malasia
Source: PR Newswire
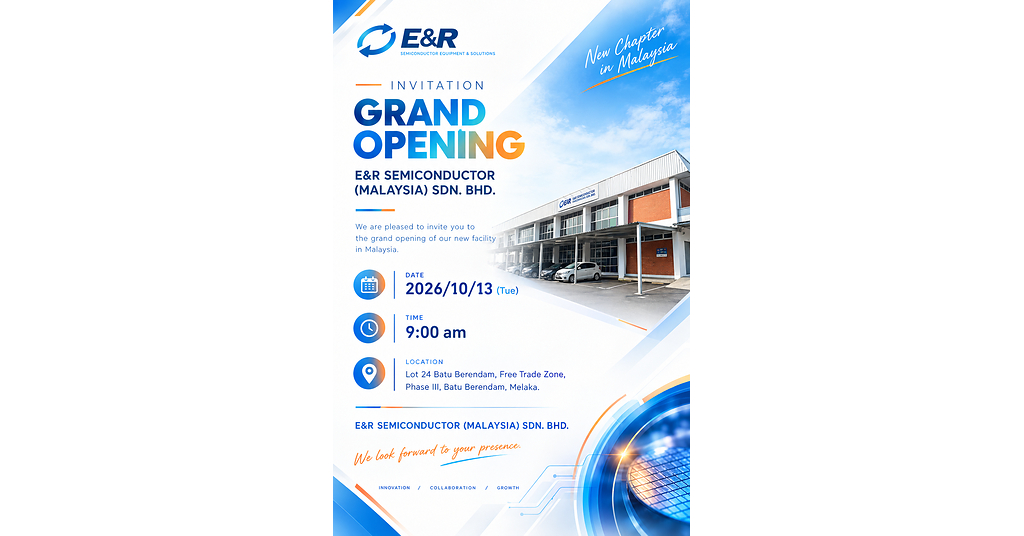
E&R Engineering plans to inaugurate its Malaysian subsidiary on October 13, 2026, shifting part of its packaging-materials production from China while expanding total capacity. The plant is testing and qualifying samples, with mass production expected to begin in early 2027, and is expected to create 50 local jobs. E&R says the facility will supply semiconductor and OSAT customers in Southeast Asia and provide local engineering support; the article cites a projected Malaysian semiconductor market of $16.51 billion by 2030.
Analysis
The strategic value is less the added floor space than the possibility of becoming a locally qualified, faster-response supplier to Malaysia’s OSAT cluster. If customers adopt the local source, E&R could improve retention and reduce delivery friction; the same proximity also raises the cost of switching for customers once the products are qualified. Those benefits are conditional: sample testing is not evidence of customer approval, recurring orders, or attractive utilization.
Near term (days to weeks), the opening itself is unlikely to establish an earnings inflection. Over the next 1–3 months, the key signals are qualification milestones, customer commitments, and whether service support converts into equipment or materials orders. Over 6–18 months, the upside depends on production ramp and utilization absorbing the cost of a second operating footprint. Because the announcement describes both a shift of some production and capacity expansion, the balance between relocation and net new capacity matters: the former may diversify supply with limited incremental overhead, while the latter can pressure margins if demand lags.
The contrarian risk is treating Malaysia’s semiconductor growth narrative as proof of E&R-specific demand. Local competitors or incumbent global suppliers may already meet customer requirements, and a delayed qualification could leave E&R carrying duplicated operating costs without meaningful share gains. No trade is warranted from this release alone; financial impact and valuation context are missing.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.28
Key Decisions for Investors
- Keep E&R Engineering on a watchlist rather than trading the announcement. Verify capital spending, expected operating costs, customer qualifications, and revenue contribution before underwriting an earnings upgrade.
- For the next 1–3 months, monitor evidence of customer approvals and repeat orders—not hiring or facility milestones alone. A delayed mass-production start or weak order conversion would undermine the local-supply thesis.
- Reassess over 6–18 months against utilization and gross-margin commentary: persistent underutilization or margin deterioration would indicate capacity was added ahead of demand; improving utilization alongside repeat business would support the strategic case.
- Treat the local OSAT opportunity as a possible benefit to customers through shorter supply chains, not as automatic share loss for incumbent suppliers. Avoid a supplier pair trade until customer qualification and competitive displacement are evidenced.
More News
- World Bank warns of AI concentration risks as it lifts East Asia and Pacific growth outlook to 4.5%
- Security researcher claims to they found KVM guest-host escape flaw
- CH Robinson to Buy RXO for $5.8B in Bet on AI Model
- Nike’s China troubles: What are the implications for other sportswear brands?
- SpaceX stock climbs to highest since June, returning Musk to trillionaire status
- Schneider Electric drops $22.6B on PTC as datacenter boom rains money on infra companies
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: Sector Analysis, Improvements on Research Data, and Performance Enhancements
- Choosing an AI Copilot for Equity Research