
Russia’s Oil Product Exports Rise Even as Diesel Shipments Slump
Source: Bloomberg
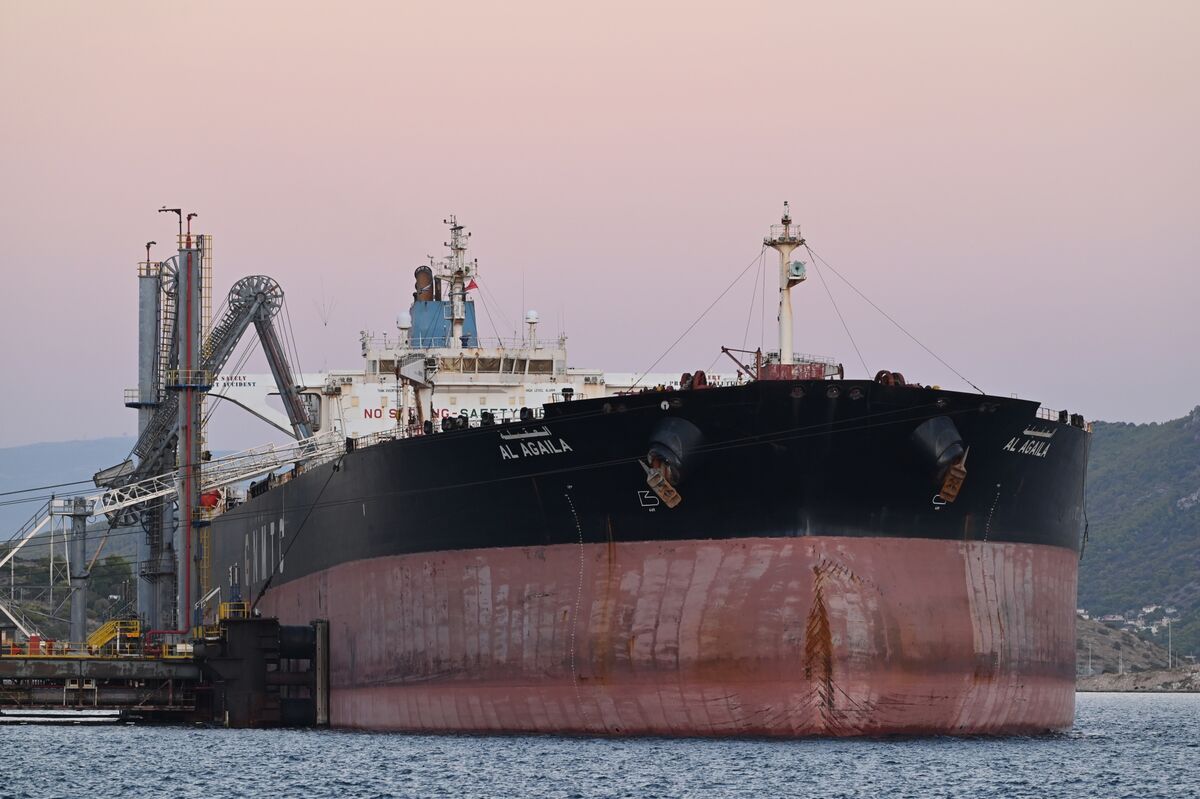
Russia’s seaborne refined-product exports rose to a three-month high of about 1.17 million barrels per day in September. Diesel shipments slumped amid a government export ban, but stronger fuel oil and naphtha flows more than offset the decline, according to Vortexa data.
Analysis
The key market implication is a change in product mix, not evidence of broad Russian supply growth: weaker diesel availability can tighten middle-distillate balances even while heavier and lighter products add pressure elsewhere. If the export restriction persists, diesel buyers may bid for Atlantic Basin or Middle Eastern replacement barrels, supporting gasoil cracks and potentially drawing cargoes away from other regions. Conversely, additional fuel oil could pressure high-sulfur fuel-oil differentials and encourage substitution toward cheaper residual fuels where specifications allow; naphtha’s impact depends on destination and competing petrochemical demand. This is not automatically bullish for refiners: replacement demand may support product realizations, but crude costs, refinery utilization, and regional product yields determine whether margins improve.
The near-term signal is fragile. September seaborne data do not establish October loadings, destination-level availability, or the effect on inventories and benchmark spreads. A policy reversal could quickly unwind diesel tightness; sanctions, freight, insurance constraints, and refinery outages could also disrupt the apparent offset from other products. Over 1–3 months, track Russian diesel loadings, regional gasoil inventories, and the diesel-versus-fuel-oil spread. Over 6–18 months, repeated restrictions could redirect trade and increase the value of flexible refining and storage, but this single monthly mix shift is insufficient evidence for a structural thesis. With no pricing or destination data supplied, prefer a conditional relative-value setup over an outright energy position.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.00
Key Decisions for Investors
- Watch rather than initiate an outright crude or broad energy position. Verify October diesel loadings, cargo destinations, and regional inventory changes before treating September’s mix as a persistent supply shock.
- Conditional trade: if Russian diesel exports remain curtailed and gasoil inventories fall, consider a hedged long gasoil crack versus a short high-sulfur fuel-oil crack. The thesis is that the restriction supports middle distillates while added residual flows weigh on fuel oil; size against observed spreads, not shipment headlines alone.
- Define the thesis failure conditions: a material restart of Russian diesel exports, rebuilding regional gasoil inventories, or sustained narrowing of the gasoil-versus-fuel-oil spread. Reassess if any occurs.
- Avoid naming equity winners on this evidence alone. Refiners’ net exposure depends on crude sourcing, product slate, utilization, and regional pricing; seek company-level guidance and margin sensitivity before expressing the view through stocks.
More News
- The world needs Ukraine’s grain. Its farmers are running out of reasons to plant
- Trump vows quick end to Iran war as fighting in Yemen intensifies
- Trump's diesel agreement with Putin accused of contradicting Russia sanctions law
- Trump reaches Russian diesel supply deal as U.S. fuel prices surge
- RBI Announces Special Oil Window, Regulatory Steps for Rupee
- Trump struck a diesel deal with Putin just weeks after signing Russia sanctions. Zelenskyy calls it ‘a weak decision’
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: AI-Powered Report Editing, Investor Relations, and Enhanced Search
- Automating Financial Model Updates: A Source-Controlled Workflow