
Stelios nahm es mit den Fluggesellschaften auf mit easyJet. Jetzt nimmt er es mit den Giganten des Online-Handels auf
Source: PR Newswire
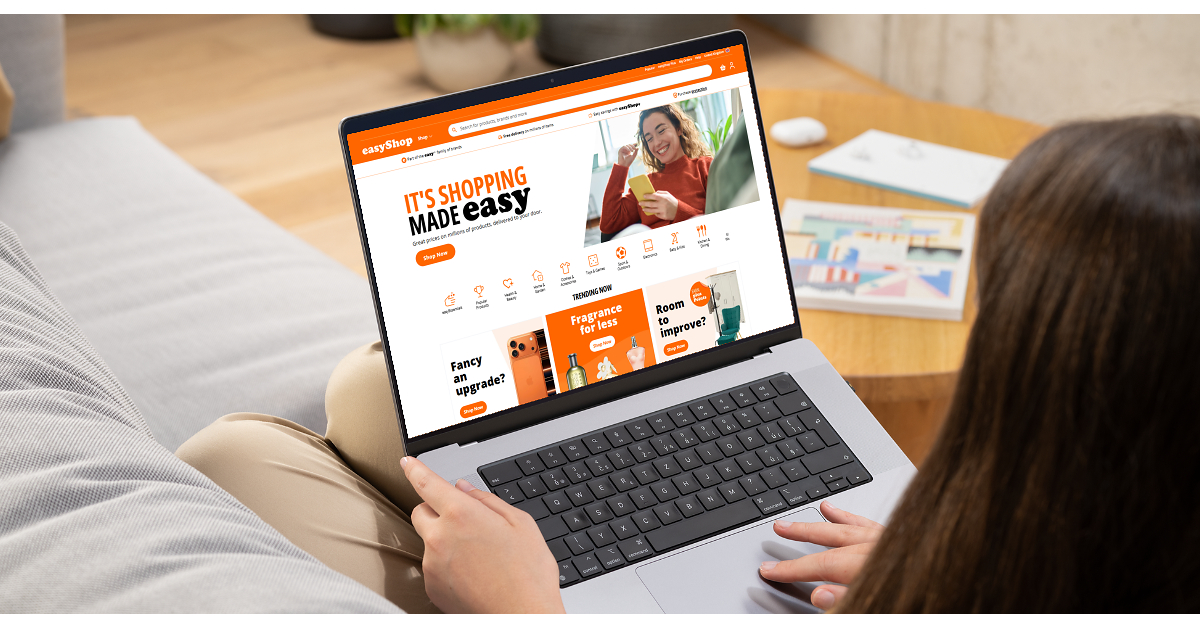
easyShop has launched in 21 European countries as an online marketplace positioned to compete with Amazon, with hundreds of retailers already active. Its model holds no inventory or private-label products and allows retailers to sell across markets through one account, with VAT calculated automatically. The launch ahead of Black Friday and Christmas offers a new expansion channel for sellers, though the article provides no sales or financial performance figures.
Analysis
The near-term threat to Amazon is negligible unless easyShop can turn seller onboarding into repeat consumer traffic. Its seller-friendly rules may win some multihoming and give merchants an incremental channel, but neutrality alone does not reproduce the demand aggregation, delivery reliability, returns handling, and advertising economics that make a marketplace valuable. Cross-border VAT automation reduces one friction; it does not establish that shipping, customer acquisition, or local compliance are economical.
For Amazon, the second-order risk would be gradual: if sellers shift promotional inventory or marketing spend to a credible alternative, marketplace fee and ad growth could face pressure before headline market share changes. There is no evidence here of buyer scale, transaction volume, unit economics, or seller retention, so this is a watch item rather than an earnings revision. The Black Friday/Christmas period offers an early but noisy test; 6–18 months of repeat-purchase and GMV data would matter more.
The easy brand is licensed to easyShop, which is operated by OnCommerce; this announcement does not establish a direct operational or earnings link to easyJet. Do not infer an EZJ catalyst from the shared brand. Contrarian read: a “fairer” marketplace pitch may attract merchants, but merchants follow profitable demand, not platform rhetoric. For AMZN, a measurable sustained shift in European third-party GMV, seller advertising, or retention would be needed to change the thesis.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- No immediate AMZN position: the launch is not evidence of material share loss, and the key scale and economics data are absent.
- Track easyShop through the holiday period and into 2027: seek independently verifiable active buyers, repeat orders, GMV, delivery/returns performance, and seller retention before treating it as a competitive catalyst.
- Reassess AMZN only if credible data show sustained European seller or ad-budget diversion alongside weaker marketplace growth or guidance; that would strengthen a relative short thesis, while weak buyer repeat rates would falsify it.
- No EZJ trade on this news: verify any direct licensing revenue or material commercial exposure before linking easyShop performance to easyJet.
More News
- Apple’s new home devices are a bet on its upgraded Siri AI
- Cheap Chinese and open source LLMs could trigger trillion-dollar AI infrastructure 'reset'
- Iran threatens Gulf data centres: How exposed is the region’s internet?
- Chip Selloff Spreads Globally, Apple Makes Smart Home Push
- Apple Unveils $299 HomeView Smart Home Hub, New Apple TV 4K, HomePod Mini 2
- Apple unveils new smart home products, showcasing updated Siri AI