
NOTHING NINE: The Real Test Begins After Paris
Source: PR Newswire
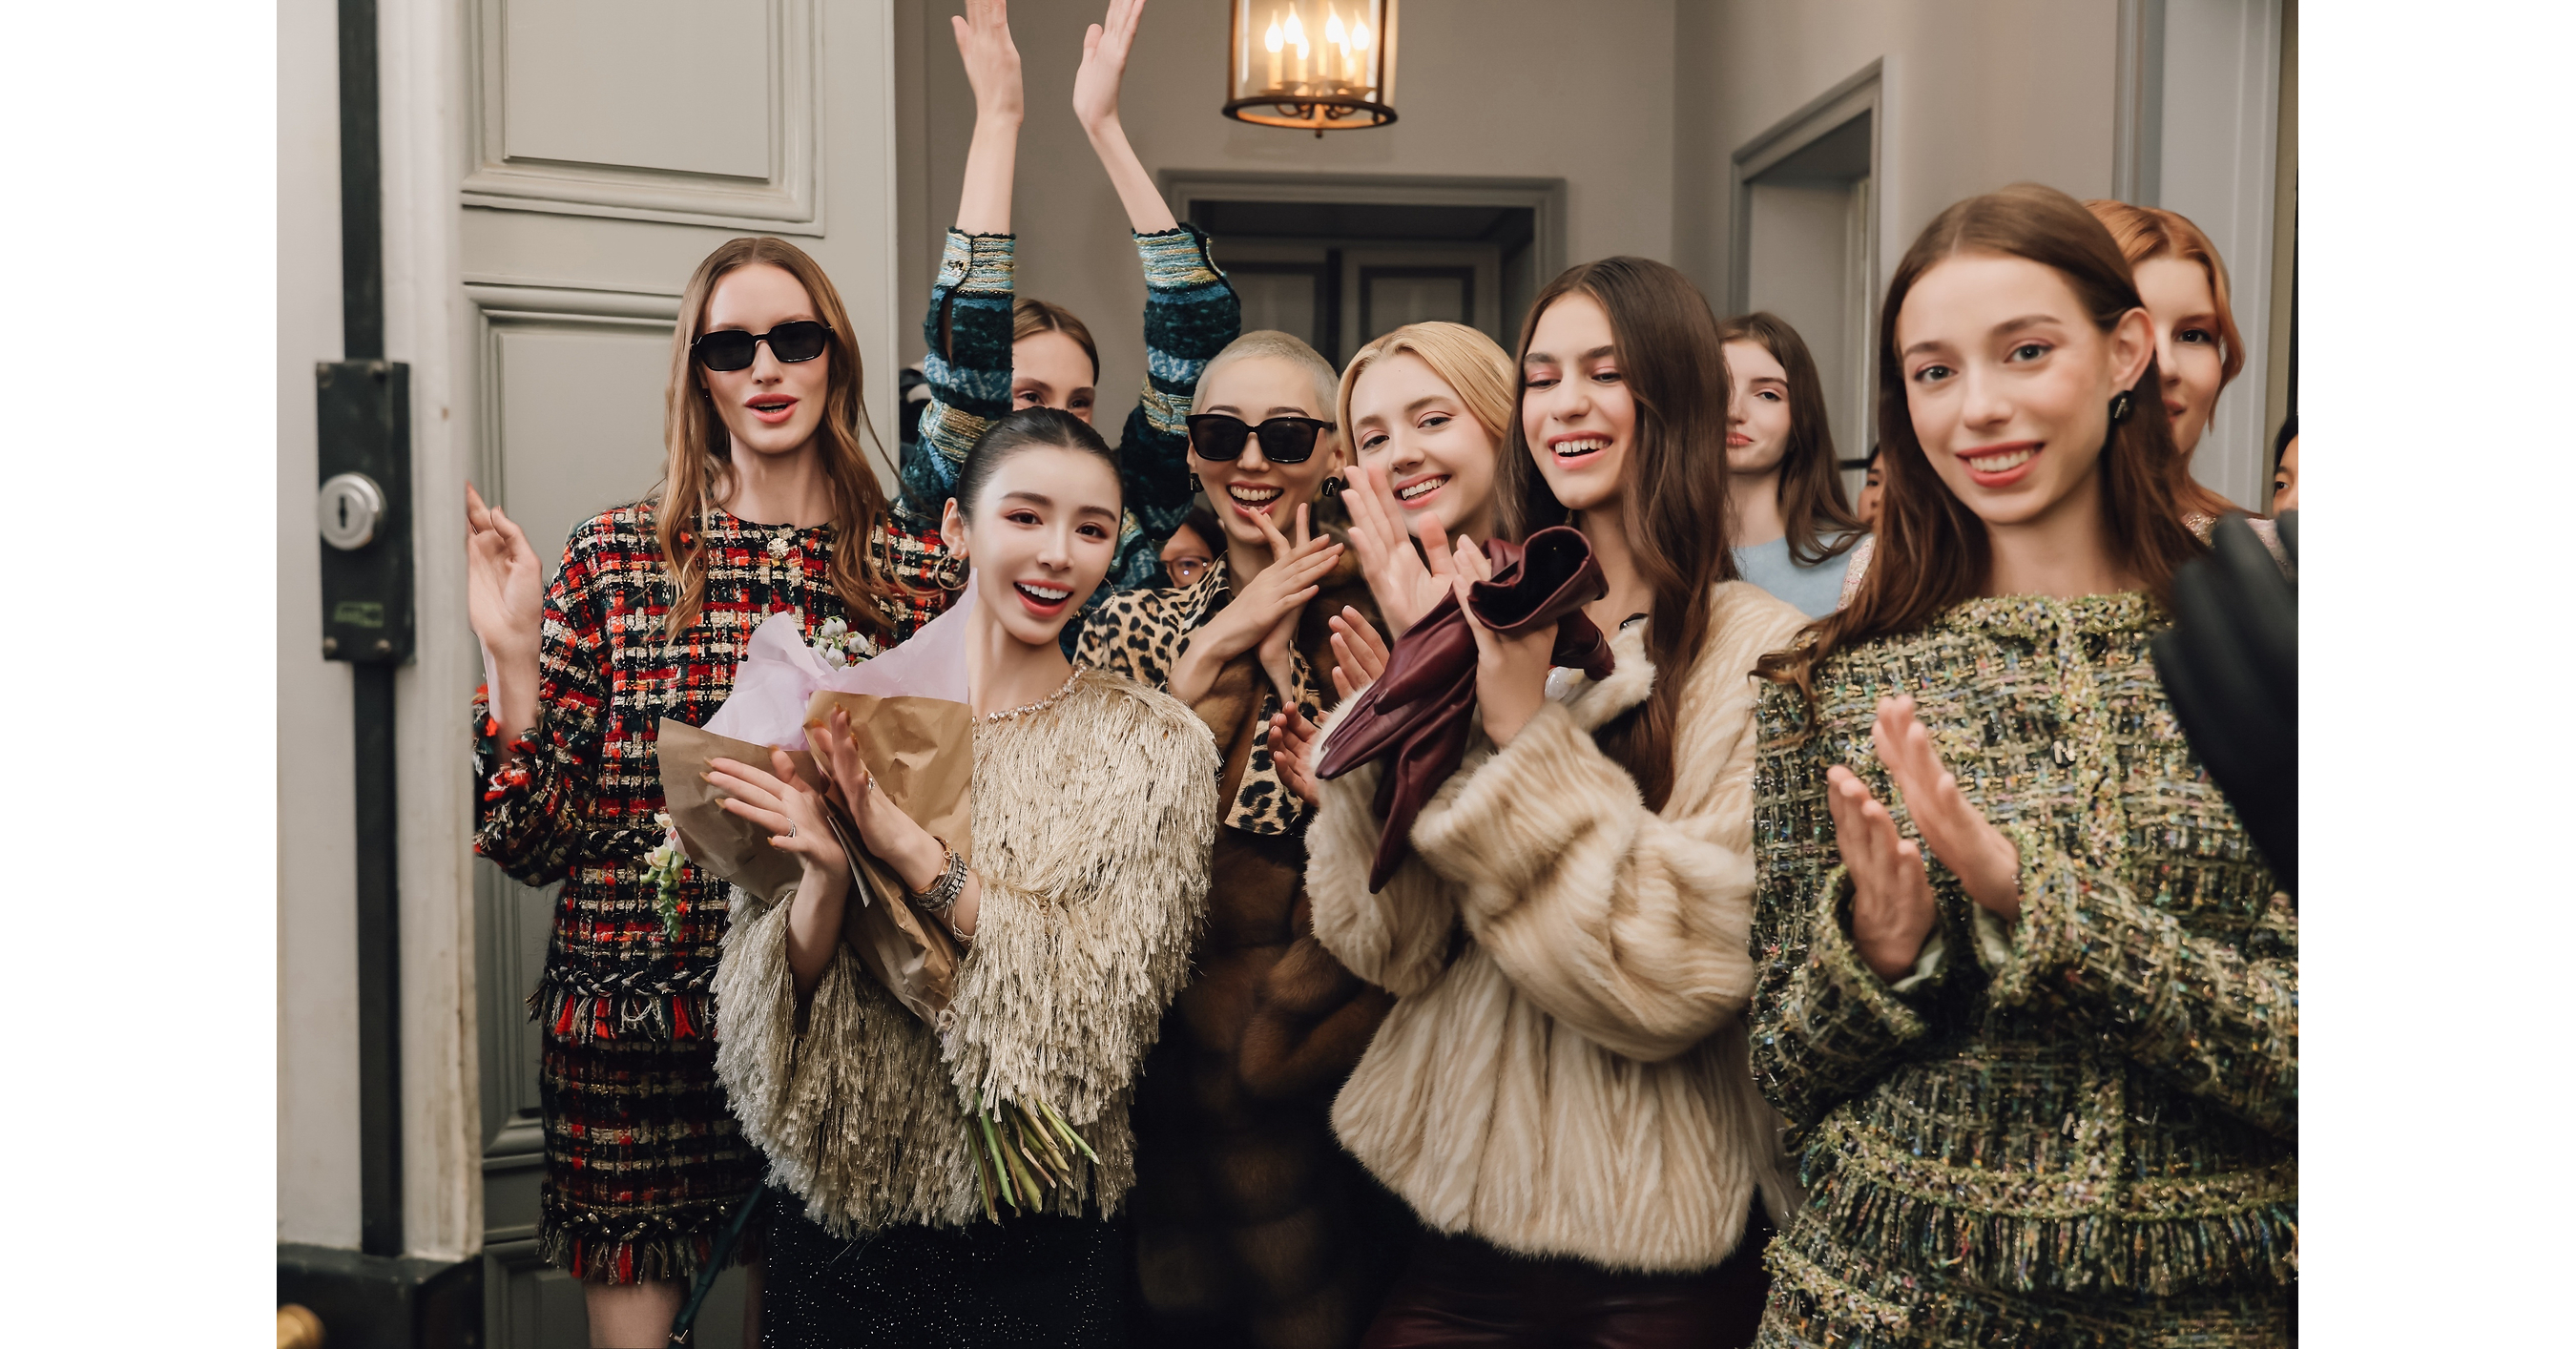
Chinese designer brand NOTHING NINE reported 100% year-on-year sales growth from 2024 to 2025 and a further 200% increase in 2026 to date; it said overall sales rose 300% year on year following its Paris Fashion Week show. Overseas buyer enquiries increased 60% during the show and the following two months, and an Italian boutique has placed repeat orders. The company plans presentations in Europe and Los Angeles in late 2026 and early 2027, targeting at least eight stable multi-brand retail partners across Europe and North America by end-2027.
Analysis
The useful signal is not runway visibility but whether inquiries convert into repeat orders at prices that support labor-intensive production. The stated sales growth and post-show uplift lack a disclosed base, channel mix, sell-through, returns, or margin data; treat them as company-reported traction, not evidence of scalable economics. A repeat order is a stronger indicator than buyer enquiries, but one boutique does not establish broad demand.
The key second-order risk is capacity: a hand-finished jacket requiring multiple artisans for 14–16 days suggests growth may be constrained by skilled labor and production lead times. Scaling too quickly could dilute quality or require inventory and working-capital commitments before wholesale receipts arrive. Wholesale expansion can also raise revenue while lowering gross margin versus direct sales, depending on terms and markdown support.
Near term, Paris exposure may generate attention, but the investable test over the next 1–3 months is conversion into documented orders and repeat purchases. Over 6–18 months, the eight-partner target matters only if those doors produce healthy sell-through and reorder without discounting. The contrarian read is that headline growth rates may overstate commercial durability because the starting base and attribution are undisclosed. No public company identity or ticker is supplied, so this is not a direct equity signal; read-through to listed luxury names is too diffuse to trade.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.45
Key Decisions for Investors
- No direct position: the brand is not mapped to a public ticker, and the article does not establish a liquid listed beneficiary.
- Track order conversion, repeat-order count, sell-through, realized pricing, gross margin, and production lead times; treat buyer enquiries and presentation plans as leading indicators, not booked demand.
- Reassess if the planned retail-partner expansion produces repeat orders with limited discounting; downgrade the growth narrative if partner additions fail to convert or production delays and quality issues emerge.
- Avoid using this as a catalyst for broad luxury-sector exposure: the spillover to listed brands is likely immaterial absent evidence of meaningful category share or competitor demand displacement.
More News
- Federal Reserve is likely to hold interest rates steady in October. Here's what that means for consumers
- From Wall Street to Silicon Valley, Anthropic IPO poised to have massive 'trickle-down effect'
- EQT becomes the nation’s leading natural gas ‘juggernaut’ with a $13B deal as data center, export demand surges
- Microsoft offers buyouts to nearly 30% of workforce in ongoing AI shift
- Anthropic’s risk factors include the end of humanity, a feud with the Pentagon, and CEO Dario Amodei’s reputation
- Elon Musk warns more than 200 AI cloud companies face ‘guppy-level death’ as the AI boom runs into a debt crisis