
Corvex Management requisitions general meeting to elect James Gemmel to the board of Whitbread PLC
Source: PR Newswire
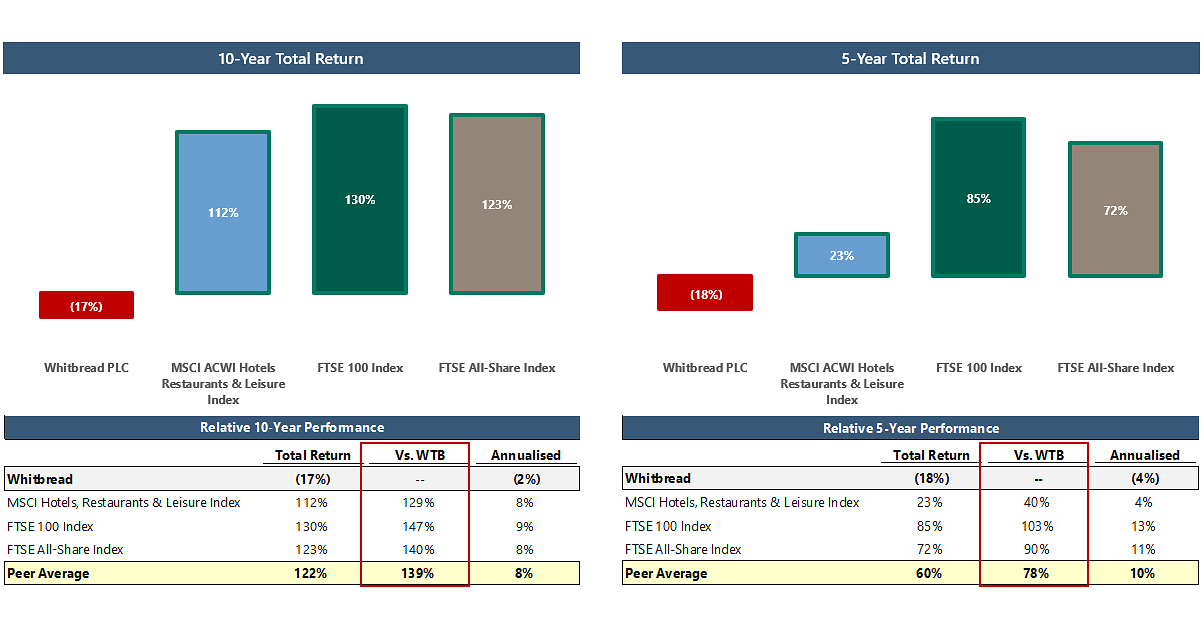
Corvex Management, which holds 6.4% of Whitbread shares and about a 7% economic interest, has requisitioned a shareholder meeting to elect partner James Gemmel to the board. The activist cited Whitbread's negative total returns of 17% over 10 years, 18% over five years and 22% over one year, alongside roughly £2.6bn of post-Costa growth capex that produced only about 3% EPS CAGR, a flat dividend and a £2.3bn increase in lease-adjusted net debt. Corvex is seeking one board seat rather than control or a sale, arguing that Whitbread's planned ~£2.5bn of five-year gross capex, including ~£1.5bn of sale-leaseback financing, requires greater shareholder oversight and a review of strategic alternatives.
Analysis
The relevant re-rating mechanism is not simply a governance change: an independent capital-allocation review could lower Whitbread's forward investment intensity, redirect cash toward repurchases/dividends, or impose return thresholds on new rooms. That would improve free-cash-flow visibility, but the offset is that further sale-and-leaseback funding converts property economics into fixed rental obligations, increasing downside operating leverage if UK business travel or domestic leisure softens. The market should therefore value any activist-driven upside against a higher required return on a more lease-heavy earnings stream.
Near term, a board-seat campaign creates an event-driven floor and raises the probability of disclosures around unit returns, property values, and alternatives for the operating and real-estate components. A single director nomination is more likely to gain institutional support than a control slate, particularly if the board does not present a credible independently verified response; the catalyst window is the meeting date through the next results/capital-plan update (1-3 months). Conversely, Corvex's stated lack of a predetermined transaction means a takeover premium is not the base case, and a sharp first-day move that prices a sale would be vulnerable.
The contrarian point is that the key issue may be the cost of capital rather than brand quality. Cutting growth spend can mechanically lift near-term FCF while damaging network density and long-run share gains; a credible plan must show mature-site cash returns above the lease-adjusted cost of capital, not merely a lower CapEx number. MDU and KNF demonstrate Corvex can influence strategic outcomes, but they are not clean read-throughs for UK lodging, so the pedigree alone should not command a permanent valuation premium.
Falsification for a constructive WTB view would be management demonstrating sustained improvement in lease-adjusted ROIC and FCF conversion while maintaining the current investment plan, or shareholder support decisively rejecting the nominee. More negatively, weaker RevPAR, cost inflation, or rising lease-adjusted leverage alongside unchanged capital commitments would turn the governance dispute into a balance-sheet/multiple-compression problem over 6-18 months.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.32
Ticker Sentiment
Key Decisions for Investors
- Initiate a modest event-driven long in WTB.L ahead of the general-meeting timetable, sized for governance optionality rather than a sale. Add only if the board publishes site-level return hurdles, property-value evidence, or a credible capital-return framework; take profits into any takeover-style premium because no transaction demand has been articulated.
- Express the thesis as long WTB.L / short IHG.L only after confirming Whitbread's valuation discount on a consistent lease-adjusted EV/EBITDA and FCF basis. The pair isolates a potential capital-allocation re-rating from UK travel beta, but it is vulnerable if IHG's asset-light earnings compound faster than Whitbread can improve returns.
- Avoid extrapolating the news into longs in MDU or KNF; their relevance is limited to activist credibility and creates no identifiable earnings catalyst. Treat any sympathy move as liquidity to reduce, not add.
- Set an alert for the next WTB results: exit or hedge the long if RevPAR and occupancy weaken while lease-adjusted net debt rises and management reiterates the full investment plan without quantified return thresholds. The missing diligence item is the economics of incremental rooms and sale-leaseback terms; without it, this remains an event trade rather than a 12-month fundamental conviction.
More News
- South Korean solar stocks jump as curbs on Chinese sector expected to remain in place
- Paramount will need to release way more movies to make this merger work
- Meta is breaking out after introducing Muse AI agent. Where the stock is going, according to the charts
- Australia’s IDP shares drop after rejecting $494 mln Blackstone offer
- Lennar shares pop as Berkshire builds almost a 10% stake in beleaguered homebuilder
- Royal Caribbean nears $3 billion deal to take 50% equity stake in Sandals