
Parks Associates: MDU Owners/Operators Value Trusted Brands With Reputation For Strong Cybersecurity and Data Privacy Protection When Selecting Proptech Vendors
Source: PR Newswire
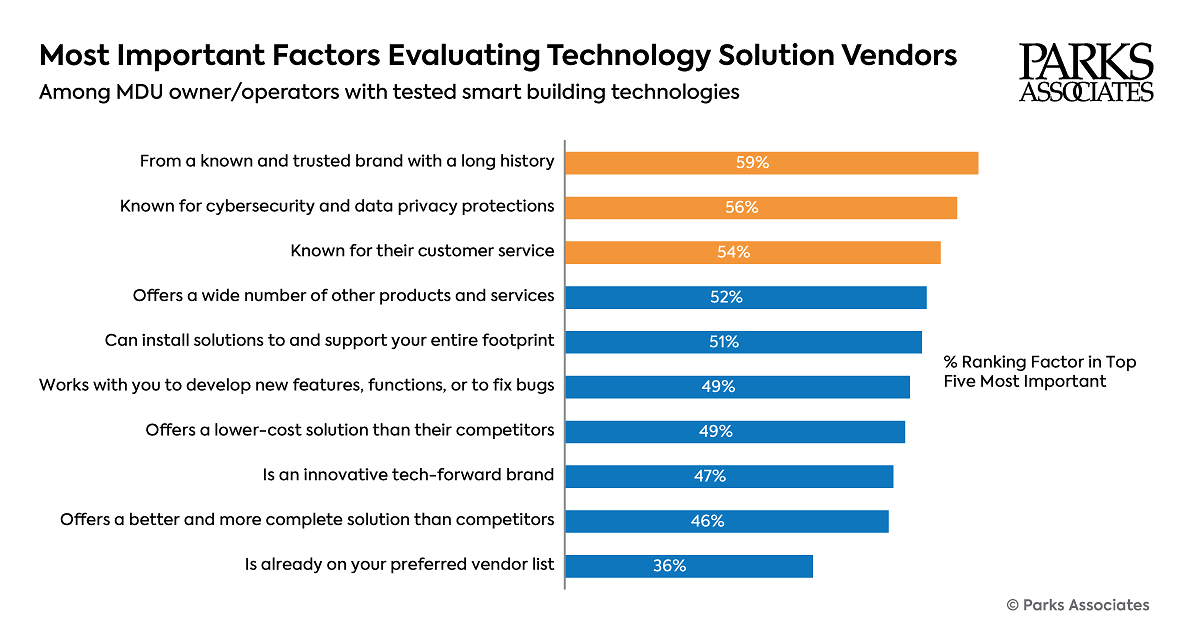
Parks Associates says MDU owners/operators place strong emphasis on vendor brand reputation for cybersecurity and data privacy, with 56 companies ranking it the second-most important factor in proptech selection. The survey also notes a connectivity opportunity: ~42% of apartment/condo residents want in-unit smart home devices, but fewer than 10% report communities currently offer them. The article is primarily event/research promotion, with limited direct implications for near-term public market pricing.
Analysis
This reads more like a procurement filter than a demand inflection: in multifamily tech, cybersecurity and privacy are turning into table stakes, which rewards incumbents with recognizable brands, compliance muscle, and integration depth. That should marginally improve win rates for platform vendors like CALX and, to a lesser extent, JCI/ALLE/GNTX, while pressuring smaller point-solution providers that rely on feature parity but lack trust credentials. The second-order effect is longer sales cycles but higher retention once embedded, which is constructive for recurring revenue models and negative for one-off hardware commoditizers.
Near term, the market reaction should be muted unless conference commentary translates into measurable pipeline acceleration over the next 1-3 months. The key watch item is whether multifamily operators actually convert stated interest into funded deployments; if capex stays tight, the “smart space” narrative stays aspirational and the thesis fails on timing rather than strategy. Falsifiers are simple: no improvement in CALX multifamily bookings, no pickup in JCI/ALLE channel commentary, or a macro-driven slowdown in property upgrades.
The contrarian view is that consensus may overestimate category growth and underestimate vendor concentration. The real opportunity is not more devices, but fewer vendors passing security review, which should widen dispersion between trusted platforms and weaker competitors over 6-18 months. That argues for selective quality exposure, not a broad proptech beta trade, and suggests any upside in CALX is more about share capture than top-down TAM expansion.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.10
Ticker Sentiment
Key Decisions for Investors
- Small tactical long CALX into the next 1-3 month channel-check window; thesis is modest share gains from trust/managed-network procurement, with ~2:1 upside/downside if multifamily commentary improves. Exit if management does not show better MDU backlog conversion by the next print.
- Relative-value pair: long ALLE, short CMBM for 1-3 months. ALLE has a clearer brand-security moat in access control, while CMBM is more exposed to spec-driven pricing and lower switching costs; this is a quality-versus-commodity trade, not a category bet.
- Keep JCI on a watchlist rather than buying outright; if building-automation commentary confirms cyber/compliance-driven bundling, it becomes a cleaner 6-18 month winner. No trade unless we see evidence of incremental share or margin lift in connected-building segments.
- Avoid chasing GNTX on this headline alone. The event is directionally favorable, but the current signal is too soft to justify risk; reconsider only if the company cites measurable multifamily conversion or design-win velocity at the September conference.
More News
- Nvidia GPUs are everywhere. Here are the ways companies are accessing them
- Stocks were up this week. Here are the names that are now overbought
- Why Nvidia’s stock is dodging the AI credit scare that is crushing Broadcom and Oracle
- As companies pour billions into Earth-based AI infrastructure, Google is taking the data center race off-planet
- Verizon stock heads for worst day since 2002 as SpaceX U.S. network plans whack telcos
- AI's Supercharging a Scam Economy Bigger Than the Cocaine Trade