
METLEN and PETRONAS enter into LNG Supply Agreement to strengthen energy security and diversification in Southeast Europe
Source: PR Newswire
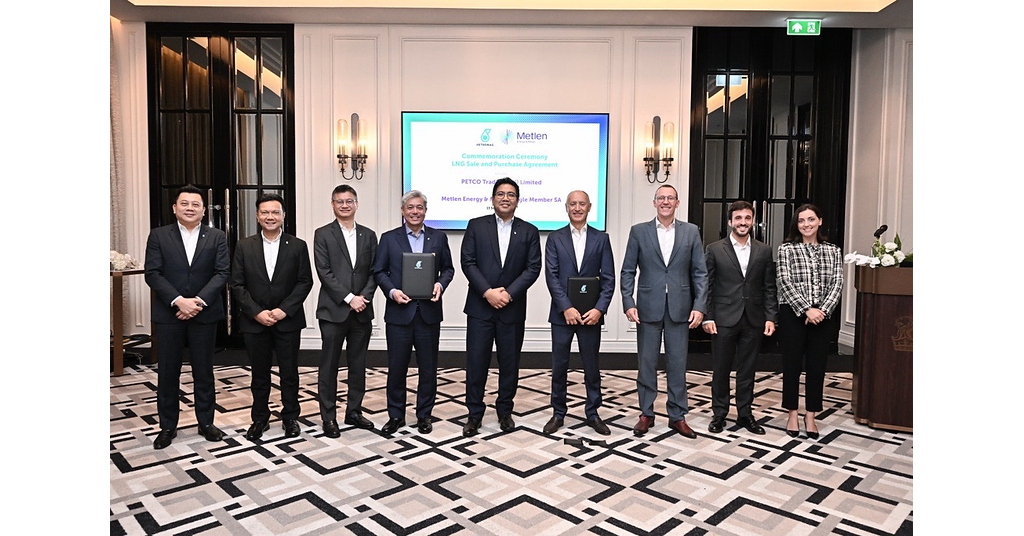
METLEN and PETRONAS subsidiary PETCO Trading signed a five-year LNG supply agreement covering six cargoes annually, or about 0.6 bcm per year, beginning in 2027. The deal diversifies METLEN's LNG procurement and is intended to improve supply flexibility and energy security for Greece and Southeast Europe, while expanding PETRONAS' LNG presence in European and Mediterranean markets. The agreement is strategically positive for both companies but is unlikely to materially affect broader LNG markets given its relatively modest volume.
Analysis
This is strategically useful but financially immaterial at group level unless it enables higher-margin regional gas trading or materially improves utilization at METLEN’s thermal generation assets. The unpriced contract should be treated as procurement optionality rather than an earnings upgrade: value accrues if Atlantic-basin LNG remains competitively priced versus TTF and METLEN can monetize destination flexibility into Balkan markets during winter congestion. PETRONAS gains a modest route-to-market foothold, but the volume is too small to alter its portfolio economics.
For MTLN, the relevant 1-3 month catalyst is management disclosure of pricing indexation, destination rights, and whether contracted supply replaces expensive spot procurement versus simply adds inventory risk. A widening TTF-JKM spread or Southeast European pipeline constraints would make the agreement more valuable; a well-supplied European LNG market would largely eliminate its trading premium. The principal downside is hidden take-or-pay exposure if regional gas demand weakens, especially because fixed LNG commitments can amplify working-capital needs and leverage during low-price periods.
Consensus may overread the announcement as evidence of a durable regional-hub moat. That moat depends on regasification access, transmission capacity, and downstream customer contracts—not molecule supply alone—and these assets are shared with larger European portfolio players. The tradeable implication is therefore conditional: MTLN deserves a modest rerating only if subsequent disclosures demonstrate incremental energy-segment EBITDA or improved cash conversion, rather than a generic diversification narrative.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Ticker Sentiment
Key Decisions for Investors
- Maintain MTLN at neutral pending its next results disclosure; upgrade only if management quantifies incremental gas-trading or generation EBITDA and confirms flexible destination/pricing terms. A guidance increase of at least 3-5% would justify reassessing a long position.
- Use any announcement-driven MTLN strength to avoid chasing: the contract alone is unlikely to change consolidated earnings materially over the next 12 months. Entry is more attractive after confirmation that TTF volatility and Balkan basis spreads are producing realized trading gains.
- Set an alert on winter TTF and Southeast European hub spreads: a sustained regional premium above roughly EUR 5/MWh versus Northwest Europe would support a tactical long MTLN for the 2027 delivery ramp; convergence below EUR 2/MWh weakens the optionality thesis.
- Do not infer a read-through for MSCI or LSEG from this development; their inclusion in the supplied ticker set is not linked to an identifiable revenue or valuation mechanism.
More News
- What investors need to know about Alphabet's stock-busting earnings report
- Our next steps for Alphabet stock after earnings disappoint at nearly every turn
- Budget 2026 speech
- Fortinet’s stock is taking a dive after earnings. Here’s why.
- Wendy's shares jump 15% as Nelson Peltz's Trian offers $1.4 billion to buy burger chain
- Microsoft's Big Bets on AI Start to Pay Off