
Uni K Wax Names Jarred Fajerski Chief Executive Officer
Source: PR Newswire
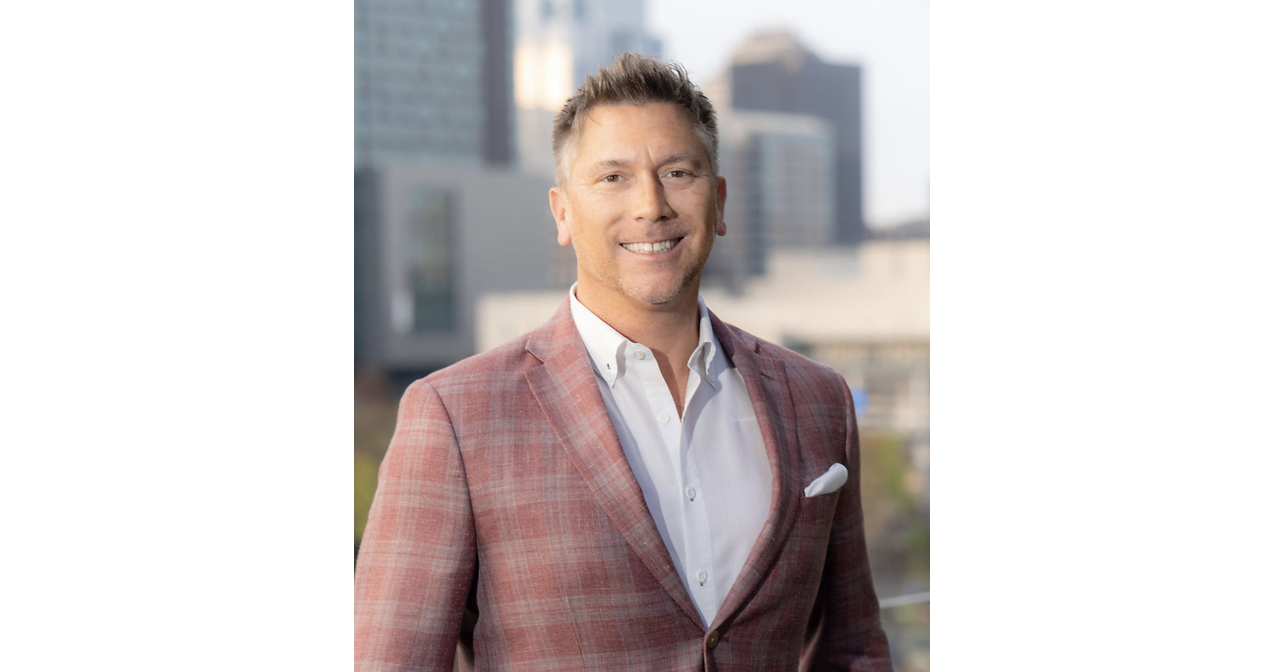
Uni K Wax appointed Jarred Fajerski as CEO during a major expansion phase, targeting a footprint of 71 locations (nearly 40 open studios and 31 in development across nine markets). The brand highlighted prior experience scaling 1,000+ units and $56M in sales at SSG and growing Hand & Stone from 140 to 500+ locations via two private-equity transactions, signaling confidence in continued unit-level growth and franchisee profitability. Overall, the announcement is upbeat but company-specific with limited immediate market impact.
Analysis
This is an execution-quality signal, not a near-term earnings event. In franchise models, the CEO hire only matters if it improves franchisee payback periods, site-level margins, and the ability to absorb slower independents via conversions; those are the levers that can justify a higher growth multiple. Absent evidence of that conversion, the announcement is mostly optionality.
The second-order winners are the real-estate and franchise-development ecosystems: better operator discipline can accelerate signed-to-open conversion, which benefits landlords in strip centers and brokers who live on multi-unit expansion. The clearest public read-through is modestly negative for incumbent waxing brands such as EWCZ if Uni K becomes a more credible capital-light competitor, but that only matters if the brand starts taking measurable share over the next 2-4 quarters.
Contrarian view: the market often overprices ‘growth CEO’ optics and underprices saturation risk. The binding constraint is probably not ambition but unit economics; if customer acquisition costs rise or labor/hygiene standards slip, the growth narrative can reverse fast. This is a 6-18 month story, with the first falsifier being stalled openings or evidence that conversion-led growth is cannibalistic rather than additive.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- No immediate position in TBHC on this headline; treat it as a watchlist name until next 1-2 quarters of unit-level data show better franchisee economics and net unit growth.
- Set a conditional alert on EWCZ into the next earnings cycle: only consider a tactical short if commentary shows slower comp acceleration and Uni K’s conversion strategy starts looking like genuine share gain.
- If you want a relative-value expression, use a consumer-services basket only after proof points emerge: long higher-quality franchise consolidators with visible same-store sales, short fragile salon/beauty names where margin leverage is more exposed; otherwise stay flat.
- Fade any sharp post-announcement move if the stock trades on management pedigree alone; absent hard KPIs, leadership-hire re-ratings usually mean-revert within days to weeks.
More News
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- Penske Automotive agrees to be taken private by Penske, Mitsui
- Supermicro promised a new CFO in December 2024. A $2.5 billion smuggling case and a co-founder’s arrest later, it has one
- Blackstone President Jon Gray Bets Big on AI Boom
- What's behind the sell-off in AI neocloud stocks like CoreWeave and Nebius
- Giant Taiwanese chipmaker TSMC confirms it’s in talks with Elon Musk to join ‘Terafab’ complex in Texas: ‘The AI market continues to be very strong’
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AlphaSense Pricing: What Public Contract Data Shows in 2026
- Eli Lilly Q4 2025 Earnings: Revenue Surges 43% as Mounjaro and Zepbound Dominate the GLP-1 Market