
Nio's Premium Deliveries Are Surging. Is This Warning Sign Getting Overlooked?
Source: fool.com
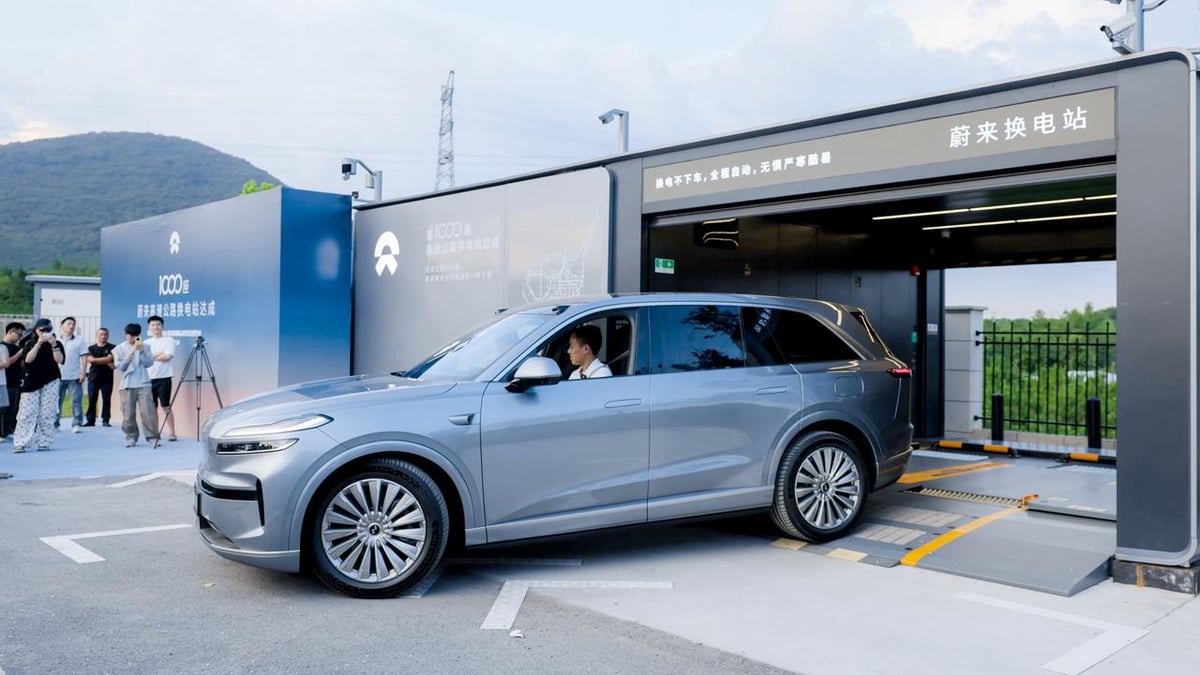
Nio delivered 37,408 vehicles in September, up 7.7% year over year; its premium brand grew 55.3%, while Onvo deliveries fell by 6,483 vehicles. Onvo deliveries have declined for four consecutive months from a May 2026 peak of 12,029 to 8,763 in September, despite Nio's Q3 deliveries rising 25.4% year over year. CEO William Li cited stronger competition and limited brand awareness, with marketing, community engagement, and store expansion planned to reach more buyers.
Analysis
The key risk is not September’s consolidated growth rate; it is whether NIO’s premium-brand strength is masking a weakening demand engine at Onvo. If Onvo needs sustained discounting, marketing, and store expansion to stabilize orders, incremental volume may carry weaker economics and absorb cash that could otherwise support product launches or the premium business. Conversely, a genuinely higher-value premium mix could cushion near-term economics—but delivery mix alone cannot establish that; verify realized pricing, incentives, and contribution margins by brand.
Over the next 1–3 months, the signal is whether Onvo’s monthly deliveries stabilize and whether orders convert without rising incentives or channel inventory. Four monthly declines warrant attention, but deliveries are not orders: seasonality, model transition, and the prior-year launch comparison complicate inference. Li Auto, BYD, and other Chinese EV makers could capture family-vehicle demand if Onvo’s awareness and distribution gaps persist; that is a competitive risk, not evidence of confirmed share transfer.
Over 6–18 months, execution determines whether added stores and community marketing create repeatable demand or merely raise the cost of acquiring customers. The contrarian point: the headline slowdown may overstate deterioration if the premium brand is gaining economically attractive mix, while the quarter’s growth may overstate resilience if Onvo’s weakness requires escalating support. No valuation, brand-level margin, or order data is supplied, so avoid treating deliveries alone as a fundamental inflection.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mixed
Sentiment Score
-0.15
Ticker Sentiment
Key Decisions for Investors
- Keep NIO at neutral/underweight rather than add on premium-brand growth alone. Reassess after the next two monthly reports: stabilization in Onvo deliveries without heavier incentives would weaken the cautious thesis; continued declines would strengthen it.
- For a relative-value expression, prefer underweighting NIO against a diversified China EV peer exposure rather than initiating an outright short on this data alone. Define the thesis around Onvo order conversion and economics, not one monthly delivery print.
- Monitor Onvo orders or backlog, retail inventory, incentive intensity, store-opening costs, and brand-level realized pricing/contribution margins. These are the missing data needed to distinguish demand weakness from delivery timing and to assess whether premium mix offsets Onvo support costs.
- Falsification: sustained Onvo delivery stabilization accompanied by improving order conversion and no material deterioration in NIO’s reported margins would argue against the underweight. Further monthly declines, rising promotions, or weaker margin guidance would validate it.
More News
- DoorDash offers $17 billion for Instacart: ‘the largest companies are only eating more and more of the pie’
- Alphabet Erases $500 Billion as ChatGPT, Google AI Cut into Search
- Alphabet just had its worst day as a public company. BofA now values Google search at a lower multiple than fossil fuel stocks
- Alphabet’s stock has worst day in over 20 years, dragging the S&P 500 to first loss in four days
- ECB’s Lagarde Steps Aside as European Economic Pressure Builds
- Warren urges DOJ criminal probe of Bank of America over anti-money-laundering violations