
Malteurop acquires the Chunlei Malting Co. malting plant - A strategic investment that significantly expands its operations and strengthens its position in export markets
Source: PR Newswire
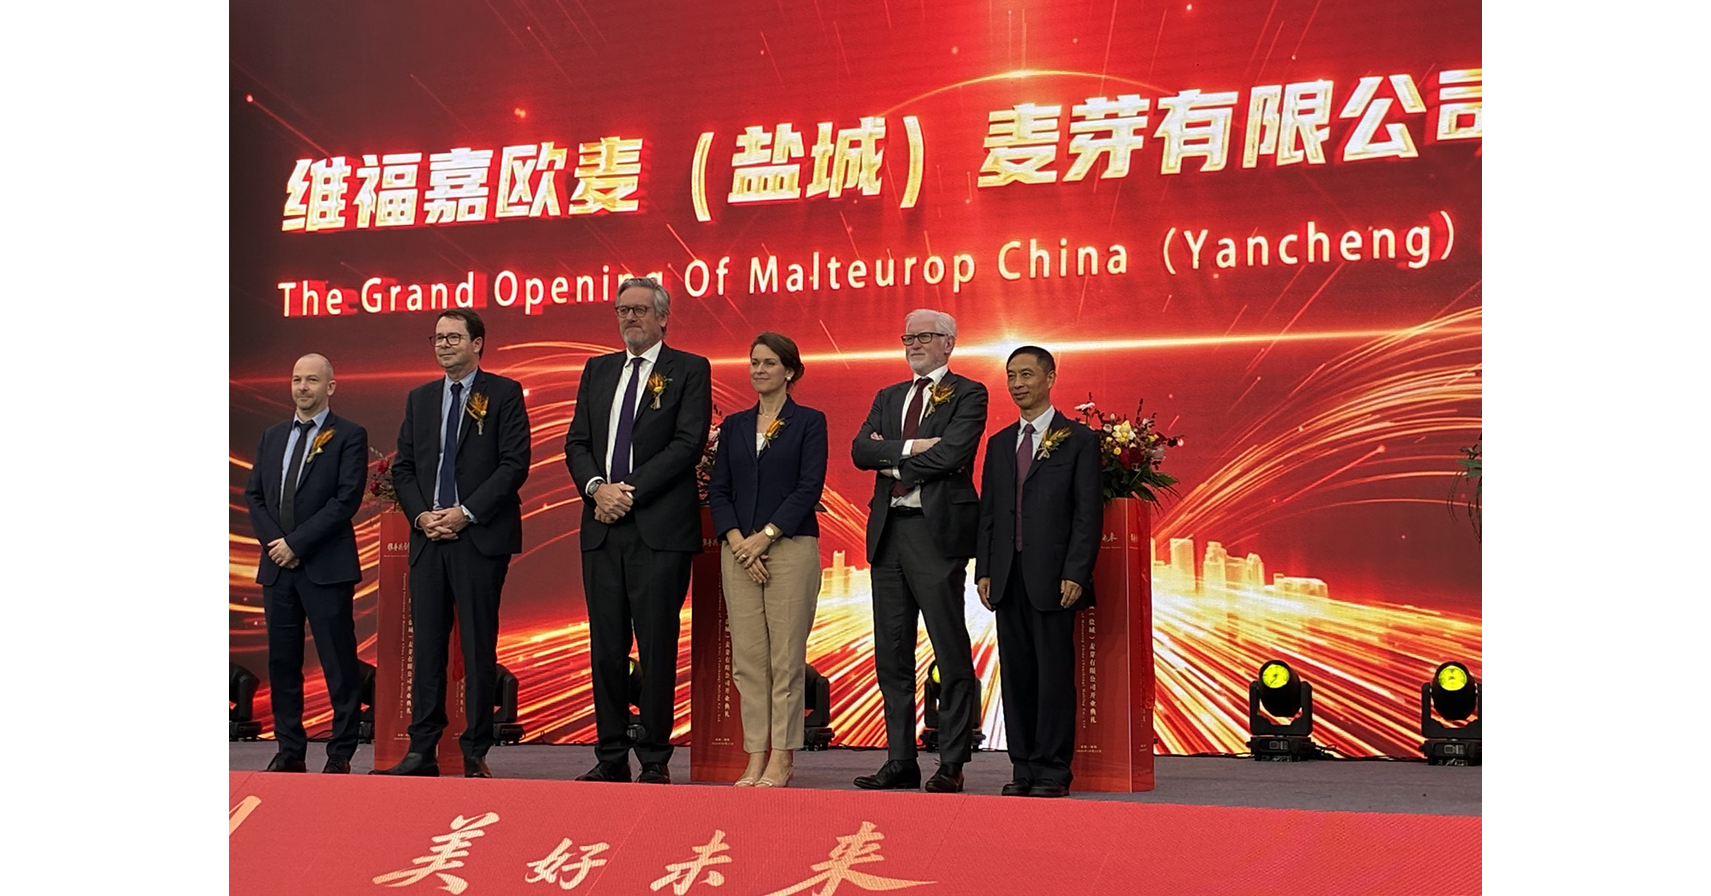
VIVESCIA’s Malteurop finalized its acquisition of the Chunlei Malting plant near Yancheng in summer 2026, adding annual capacity of 220,000 tonnes—enough malt for about 2 billion liters of beer. The deal expands Malteurop’s manufacturing and logistics footprint in China, where it is the only foreign commercial malt producer, and the company says future investments may further increase capacity. The plant combines locally sourced biomass with renewable electricity and battery storage for lower-carbon production.
Analysis
The investable signal is strategic positioning, not a demonstrated earnings inflection. The acquisition could improve Malteurop’s freight economics and customer reach in eastern China, while adding exposure to local barley sourcing and brewer demand. Whether that creates value depends on purchase price, utilization, customer contracts, and the capacity it replaces or adds; none is disclosed. The claim of being China’s only foreign commercial malt producer should be independently checked before treating it as a durable competitive moat.
Near term, the transaction was finalized over the summer, so the ceremony and announcement are weak catalysts on their own. Over 1–3 months, verify operating utilization, malt volumes, customer retention, and integration costs. Over 6–18 months, the upside case is incremental export throughput and premium-grade demand; the downside is industry capacity outrunning demand, prompting price competition and lower plant utilization. Low-carbon claims are not automatically a cost advantage: rice-straw availability, seasonal supply, energy reliability, and auditable emissions accounting matter. A policy or trade dispute affecting foreign operators is a separate tail risk.
Contrarian read: the market may overvalue headline capacity and “green” positioning while overlooking the capital and working-capital burden of operating the asset. Conversely, proximity to export infrastructure and local customer relationships may be more valuable than the plant’s nameplate capacity alone. VIVESCIA/Malteurop are not mapped to public tickers here; with no disclosed financial terms or operating data, there is no clean direct equity trade.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.45
Key Decisions for Investors
- No direct position on this announcement: the buyer is not a mapped public issuer, the acquisition is already completed, and the release supplies no price, utilization, or earnings contribution.
- Set a 1–3 month diligence alert for purchase consideration, acquired-plant utilization, incremental malt sales, customer commitments, and any capacity rationalization. Reassess only if these support a measurable return on invested capital.
- Track Chinese malt pricing, barley procurement costs, and export volumes as the key falsifiers: rising costs without price pass-through, weak utilization, or continued capacity additions would undermine the value-creation case.
- Treat the decarbonization angle as a watch item, not a green-premium thesis, until biomass sourcing, energy costs, and emissions claims are independently substantiated.
More News
- AI Doubts Spread Cracks in Equities, Credit Markets: Evening Briefing Americas
- With earnings in rearview mirror, SpaceX-Tesla merger chatter takes center stage
- Apple’s $2,000 iPhone Duo Debuts With Limited Supply
- Are global oil reserves sufficient to withstand renewed US-Iran war?
- Boeing 777 freighter output halted for two months over supplier row
- Exclusive-Boeing supplier dispute has halted 777 freighter production for two months, sources say
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- What Is an AI Research Agent?
- Bitcoin's 52% Crash Proves It's a Tech Stock: Here's What That Means for Portfolio Construction