
Democrats Tap Trump’s Economic Playbook at Republican Midterm Convention
Source: Bloomberg
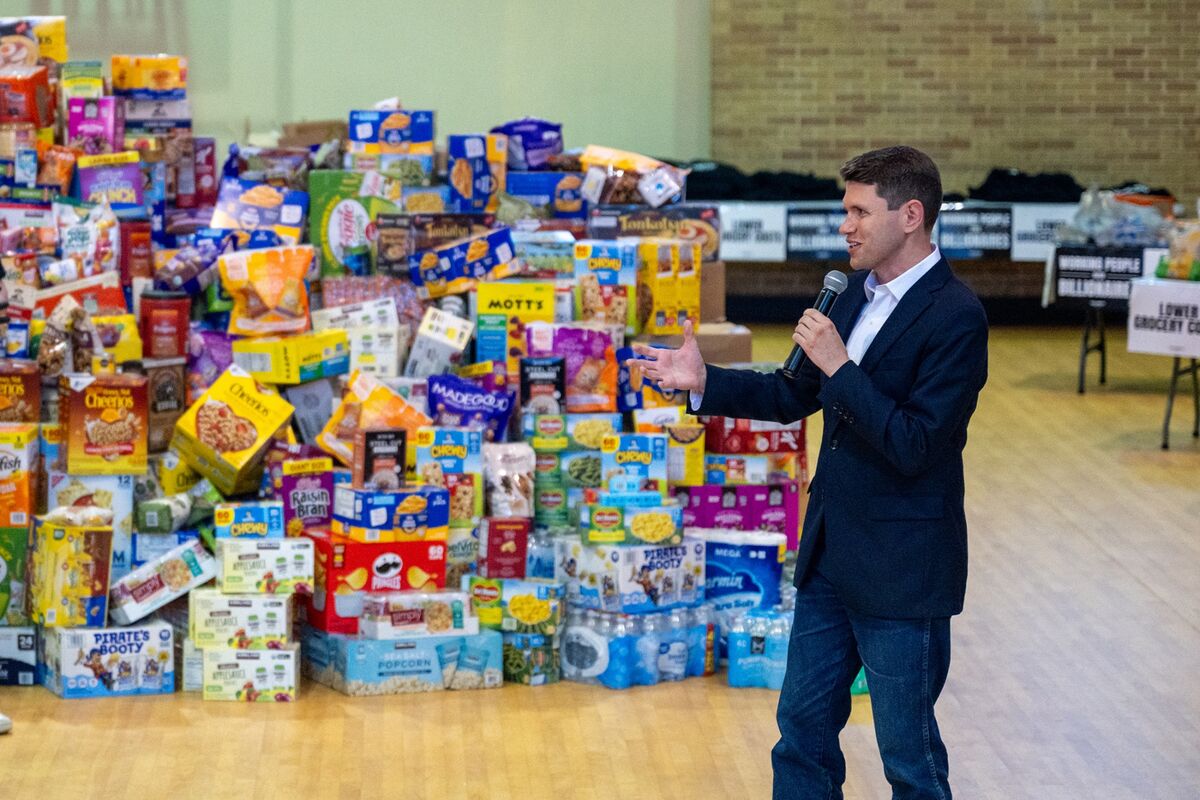
Democrats plan to center their response to the Republican midterm convention on President Trump’s handling of the cost of living. The article signals that affordability and consumer-price pressures will be a key electoral issue, but provides no new economic data, policy measures, or market-moving details.
Analysis
This is not yet a market-moving policy signal, but it raises the probability that affordability becomes the dominant 2026 election transmission channel. Markets should focus less on political messaging and more on whether it translates into pressure for highly visible price interventions: prescription drugs, housing costs, credit-card rates, utility bills, and tariffs on consumer staples. The first-order risk is sector-specific headline volatility rather than a broad equity repricing.
Over the next 1-3 months, the key market variable is whether inflation and real-wage data validate or undermine the affordability narrative. A reacceleration in CPI shelter, food-at-home, auto insurance, or consumer-credit delinquencies would increase the odds of populist regulatory proposals and compress multiples for exposed consumer-finance and healthcare intermediaries. Conversely, softer core services inflation and improving real disposable income would leave the issue politically salient but financially low-impact.
The underappreciated second-order effect is corporate pricing behavior. Consumer companies already facing volume elasticity may become more reluctant to take price, favoring promotions and pack-size changes; that can protect unit demand but pressure gross margins into 2026. This is more relevant for lower-income exposure than for premium discretionary demand, making margin dispersion within staples, restaurants, and retail potentially wider than the headline inflation trade implies.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mixed
Sentiment Score
-0.10
Key Decisions for Investors
- No directional index trade on this item alone; treat it as a policy-risk watch rather than an investable catalyst until specific legislative, executive, or tariff proposals emerge.
- Monitor a consumer-stress basket: long WMT versus short XLY on a 1-3 month horizon if food, shelter, or revolving-credit data worsen. WMT has relative traffic resilience, while discretionary multiples are more exposed to weakening real purchasing power; exit if core CPI decelerates for two consecutive prints and retail sales ex-autos/gas remain firm.
- Maintain heightened diligence on COF, SYF, DFS and subprime-adjacent consumer lenders ahead of delinquency data and earnings. Any campaign focus on credit-card pricing could create regulatory headline risk before it has earnings impact; avoid adding exposure unless net charge-off guidance and funding spreads remain stable.
- Watch consumer gross-margin commentary from PG, KHC, HSY, MCD and YUM during the next earnings cycle. A shift toward promotions without offsetting volume acceleration would support relative underweights in branded, lower-income-exposed consumer names; falsification is sustained positive volume growth alongside stable or expanding gross margin.
More News
- American embassies tighten security as Iran threat warnings intensify ahead of U.S. midterm elections
- France’s latest debt warning describes a country where governance is breaking down — and even doing too little, too late is barely possible
- Instacart reportedly discussed selling itself with DoorDash and Uber
- Sudan’s soaring fuel prices make getting by harder for workers
- Israelis hold final rally against Netanyahu ahead of what may be the most consequential election in the country’s history
- What next for France as riots rattle markets? Three questions facing investors ahead of more protests