
Manifold Tech Limited and FARO INSIGHT Partner to Expand Reality Capture into New Markets
Source: PR Newswire
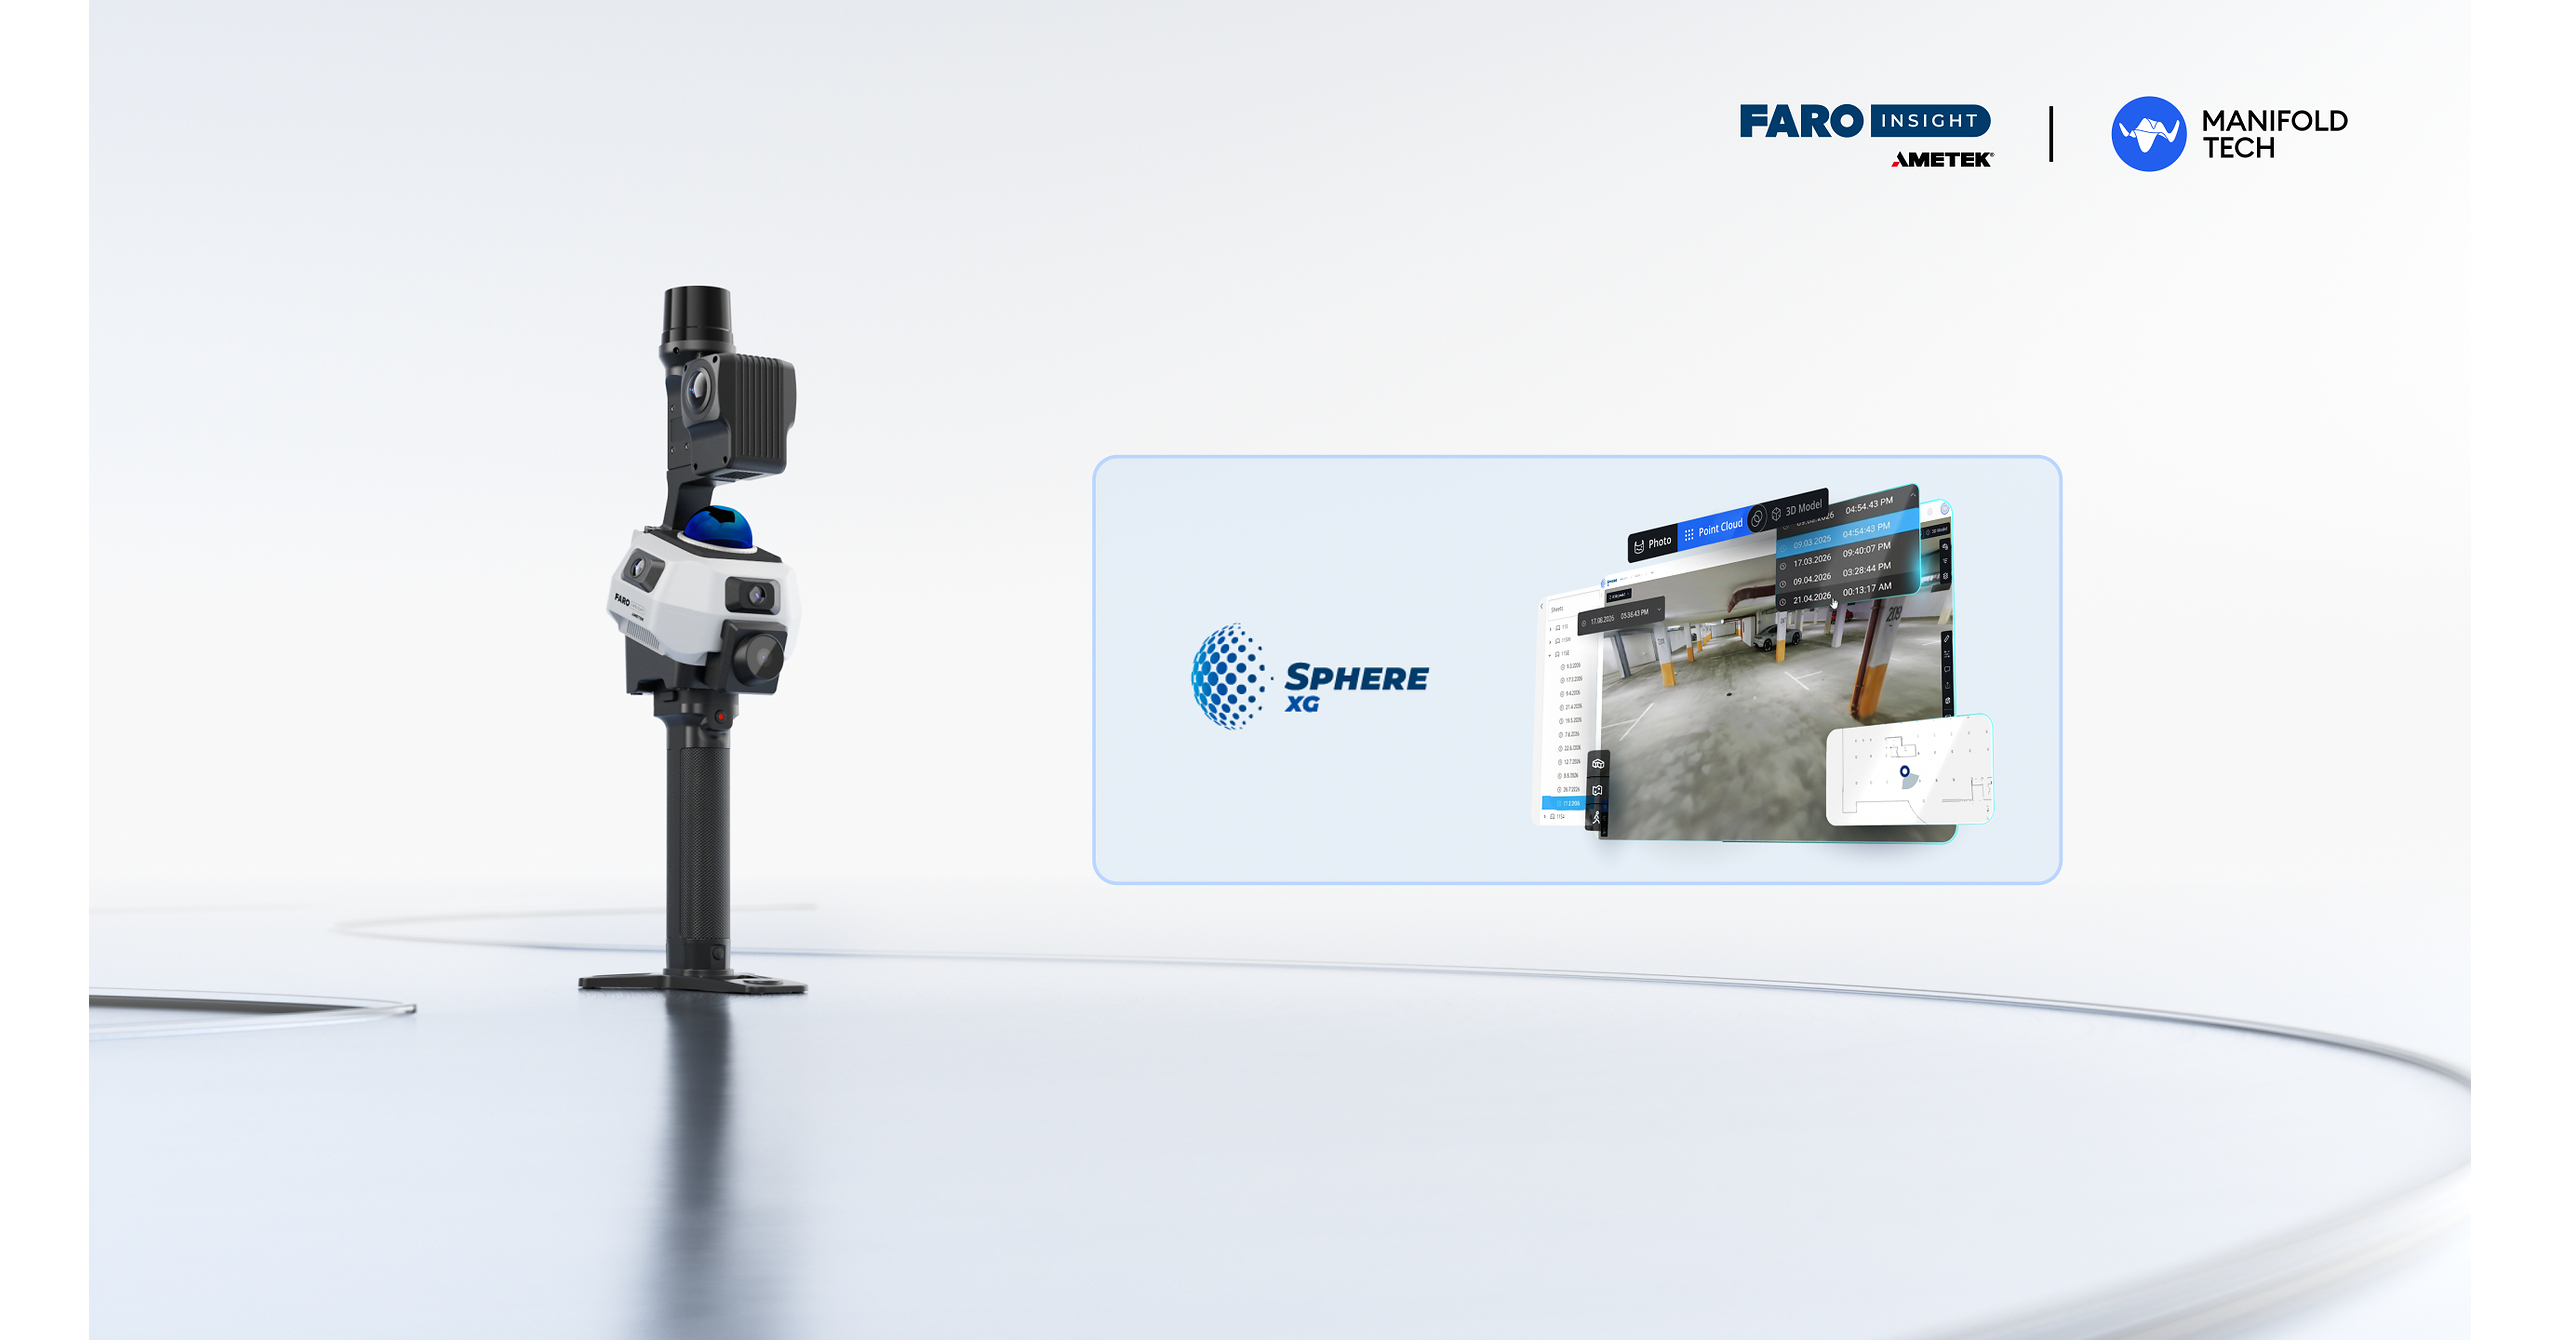
Manifold Tech and AMETEK's FARO INSIGHT launched Rovi i.1, a mobile reality-capture solution integrated with the FARO Sphere XG cloud platform. The product combines real-time localization, geometry, imagery and 3D Gaussian Splatting to generate point clouds, photorealistic 3D environments and digital-twin assets for construction, industrial, infrastructure, public-safety and heritage workflows. The collaboration broadens FARO's connected capture-to-cloud offering, though no financial terms, revenue targets or commercial launch metrics were disclosed.
Analysis
For AME, the strategic value is not likely to be hardware revenue but improving FARO Sphere XG's workflow lock-in. A lower-friction mobile capture product can expand the installed-data funnel, creating recurring cloud, storage, visualization and collaboration revenue while increasing switching costs for AEC and industrial users. The meaningful earnings question is whether Rovi drives paid Sphere seats and processing consumption rather than merely cannibalizing higher-priced terrestrial-scanner workflows.
Competitive pressure falls most directly on standalone reality-capture vendors whose differentiation rests on field hardware rather than an integrated data environment, including Leica Geosystems/Hexagon (HEXA-B), Trimble (TRMB), and Matterport (MTTR). If mobile capture reaches adequate measurement accuracy, it can shift lower-complexity site documentation away from premium laser-scanning deployments; conversely, poor accuracy would confine it to visualization and leave high-value metrology demand intact. 3D Gaussian Splatting may reduce time-to-model and cloud-compute cost versus traditional photogrammetry, but enterprise adoption depends on interoperability, data governance and liability-grade accuracy—none of which is established by the release.
Near term, this is too small to alter AME estimates or justify a directional trade; AME's valuation will remain driven by its broader Electronic Instruments execution and capital-allocation cadence. Over 6-18 months, the relevant catalyst is evidence that Sphere XG attaches to mobile deployments and converts into recurring revenue, which could support a modest multiple premium for a more software-like revenue mix. The thesis is falsified if management does not disclose digital-revenue growth, attachment rates, or field adoption by the next two earnings cycles, or if users retain incumbent point-cloud workflows rather than adopting Sphere as the system of record.
Consensus may overread the product as a new end-market expansion when it is initially a channel and workflow test. The more constructive non-consensus outcome is that AME uses the partnership to access robotics/autonomy data applications without underwriting Manifold's technology risk on its own balance sheet; the adverse outcome is that the partner captures the higher-growth sensing economics while AME supplies commoditized cloud integration.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.34
Ticker Sentiment
Key Decisions for Investors
- No immediate standalone AME trade: treat the announcement as a watch item, not an earnings catalyst, given immaterial disclosed economics and the absence of pricing, unit volumes, or recurring-revenue terms.
- For existing AME longs, maintain exposure but require confirmation within 1-2 quarters: Sphere XG paid-seat growth, mobile-product attach rate, or management commentary that digital workflow revenue is accretive to segment margins. Lack of disclosure by two reporting cycles is a thesis downgrade.
- Monitor a relative-value alert: if AME materially outperforms HEXA-B and TRMB by more than 10% on this narrative without revised revenue guidance, consider fading the excess via short AME/long HEXA-B; hardware substitution remains unproven and AME's broader premium can compress.
- Watch MTTR as the higher-beta read-through: enterprise evidence that mobile field capture is being used for paid documentation workflows would be constructive, but only consider a long after verification of retention or subscription growth; free/low-cost visualization tools remain the principal downside risk.
More News
- All Iranian airlines to be 'shut down' from Wednesday, Bessent tells CNBC
- Taiwan benchmark Taiex rises to record intraday high as tech stocks advance
- AMD joins the $1 trillion club as chip rally surges - our AI Strategy saw it early
- Jamie Dimon says hyperscaler AI spending could hit $1 trillion next year
- Here's who we know is going to the Trump-Xi dinner so far
- UK to refuel Saudi jets to help counter Houthi attacks
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Index and ETF Holdings Data for AI Research
- Capital Intensity as Gravity: The AI Trade Enters Its Industrial Era (Looking at Q3 2025 Earnings in Tech)