
Wireless Zone Franchisee Ieshpal Singh Named 2026 IFA Franchisee of the Year
Source: PR Newswire
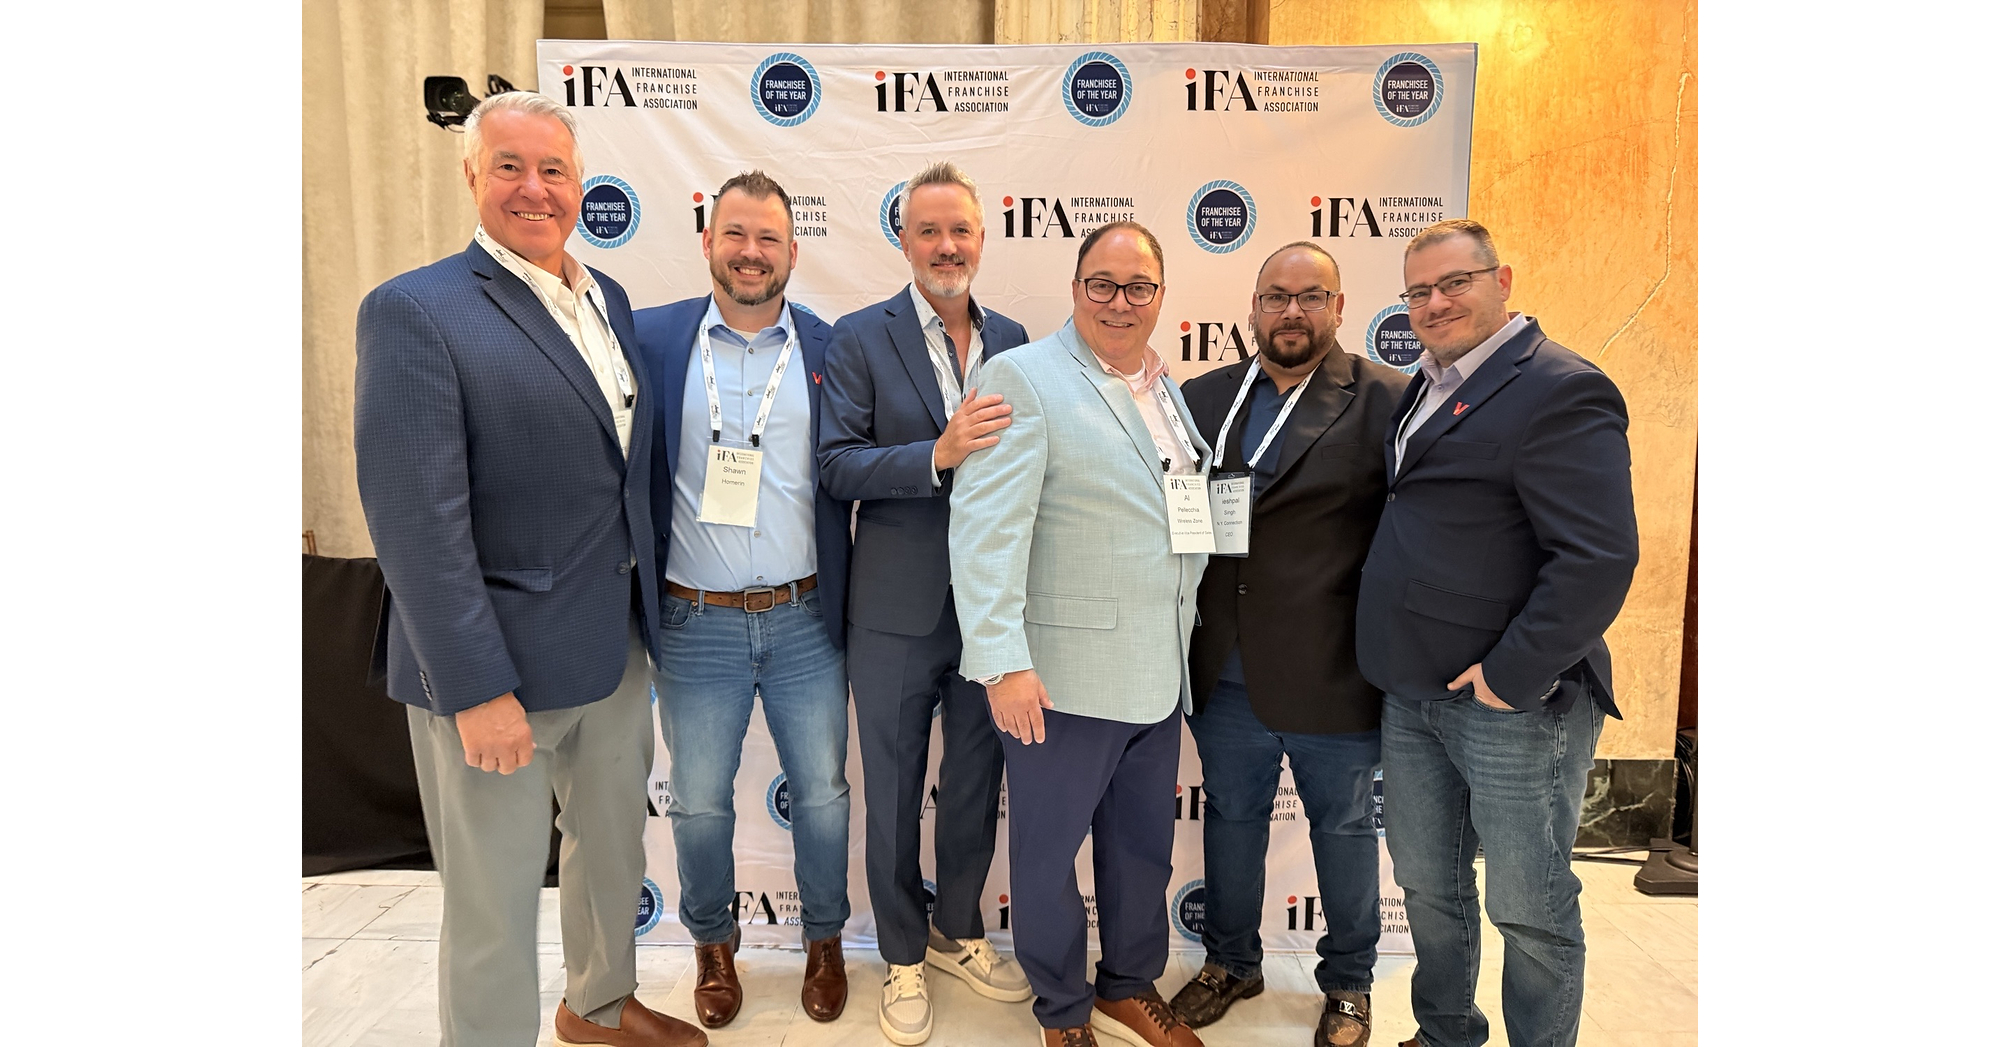
Wireless Zone franchisee Ieshpal Singh was named a 2026 IFA Franchisee of the Year after expanding from three Long Island stores in 2015 to more than 70 locations across six Northeast states, employing over 330 people. The recognition highlights operational growth, workforce development and community engagement, but does not disclose financial results or provide a material catalyst for Round Room or the broader wireless retail market. Wireless Zone operates more than 850 U.S. franchised locations, while parent Round Room has over 1,500 retail locations across 43 states.
Analysis
This is immaterial to Verizon’s consolidated earnings and should not be read as a demand signal: authorized-retailer economics are driven more by carrier commission structures, upgrade activity, labor productivity, and postpaid churn than by franchise recognition. The only modestly relevant read-through is that a large multi-state operator appears operationally stable enough to continue scaling, which supports distribution continuity in smaller Northeast markets where indirect retail remains more important than in dense urban corridors.
The second-order issue for VZ is channel bargaining power. Larger dealers can improve staffing, local marketing, and execution, but they also gain leverage in commission negotiations and concentrate operational exposure if carrier incentives are cut. Over 6-18 months, ongoing indirect-channel consolidation could help VZ lower field-support complexity, while increasing the earnings sensitivity of gross adds to a relatively small group of dealer operators; this is not presently quantifiable from the release.
No near-term catalyst exists for VZ shares. The investable wireless variables remain postpaid phone net additions, upgrade volumes, promotional intensity versus T-Mobile and AT&T, and whether service-revenue growth can outpace handset subsidy and dealer-commission pressure. A constructive channel thesis would be falsified by rising VZ postpaid churn, a material increase in promotional spending, or dealer/distribution expense growing faster than wireless service revenue in upcoming results.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.28
Ticker Sentiment
Key Decisions for Investors
- No standalone trade on this release; its expected impact is below the threshold for a VZ position change.
- Maintain VZ only as a defensive income/relative-value exposure, not a retail-distribution growth thesis; reassess after the next earnings release if consumer postpaid churn or gross-add guidance deteriorates.
- Monitor VZ selling, general and administrative expense and wireless equipment margin over the next 1-2 quarters for evidence that indirect-channel commissions are absorbing more of promotional spend; without that data, do not infer margin benefit from dealer scale.
- For a wireless competitive view, use a VZ versus TMUS pair only around independently verifiable subscriber data: favor long VZ/short TMUS if VZ churn improves while TMUS valuation remains premium; invalidate if VZ requires incremental subsidies to sustain gross additions.
More News
- Oracle Japan shares surge 7% after record fiscal first quarter, bucking selloff of U.S. parent
- Exclusive-How firms linked to sanctioned Chinese cotton giant sell clothes to U.S
- Costco makes progress on a key membership metric. Here's our new price target on the stock
- Akamai secures $11.6B cloud deal with Anthropic for AI workloads
- Here’s the Tesla Semi… again
- Why we like Starbucks’ latest turnaround move — plus, two more wins for Eli Lilly
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AllMind Fixed Income Compass for October 2025: Navigating Policy Divergence and Political Risk
- AI Equity Research Tools for RIAs and Wealth Managers