
Transocean Moves Ahead With $5.8B Valaris Deal After DOJ Nod
Source: zacks.com
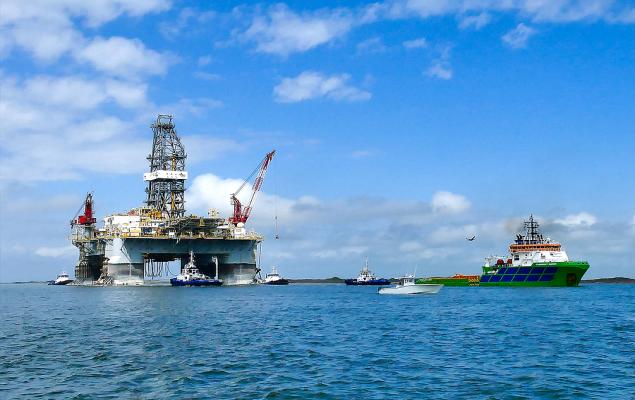
Transocean received U.S. DOJ antitrust clearance for its $5.8 billion all-stock acquisition of Valaris, removing a major hurdle for a transaction targeted to close in Q4 2026. Brazil's CADE remains the final material regulatory approval, following the opening of its review on August 7, 2026. The deal would significantly expand Transocean's offshore rig fleet and could improve utilization, customer reach and cost efficiency, although integration execution and cyclicality in oil prices, day rates and producer spending remain key risks.
Analysis
The principal equity implication is not incremental rig supply but a more disciplined owner of premium offshore capacity. A combined RIG/VAL should have greater ability to retire, cold-stack, or redeploy marginal assets rather than chase utilization at uneconomic day rates; that improves the negotiating backdrop for remaining high-specification floater operators, particularly NE. The benefit to BORR is more limited because jackup economics are driven by a different regional/customer mix, though sector consolidation can still support asset values and reduce the market's willingness to underwrite distressed fleet sales.
Near term, the DOJ outcome should have only modest standalone upside because the closing remains exposed to Brazilian review and a long execution window. The more relevant 1-3 month catalyst is disclosure around CADE remedies, the exchange ratio's implied premium, and any updated synergy or financing assumptions; absent those data, merger-arbitrage sizing is premature. Over 6-18 months, the key contrarian risk is that consolidation is interpreted as a day-rate bull case while the acquirer inherits more operating leverage into a potential offshore capex slowdown; fleet scale does not protect equity holders if Brent weakness causes customers to defer multi-year deepwater commitments.
For RIG, the central question is whether expected cost savings exceed the value dilution from issuing stock and integrating a geographically dispersed fleet. The market should reward demonstrable reduction in uncontracted rig exposure and corporate overhead, not headline fleet count. Thesis failure would be CADE-imposed divestitures, a material widening of the RIG/VAL implied deal spread, lower 2027 floater contract awards or day-rate guidance, or Brent sustaining below a level that leads majors to reduce offshore project sanctions.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Ticker Sentiment
Key Decisions for Investors
- Maintain a constructive 6-12 month relative view on NE versus RIG: long NE / short RIG in equal beta-adjusted dollars after any deal-clearance rally. NE captures improved floater pricing discipline without bearing acquisition integration or stock-issuance risk; exit if NE's floater backlog/day-rate disclosures weaken or RIG publishes credible, quantified synergies sufficient to change the relative FCF outlook.
- Do not initiate a RIG-VAL merger-arbitrage position until the definitive exchange ratio, treatment of dividends, and CADE timing/remedy risk are verified. Set an alert for a deal-spread widening above the estimated annualized return implied by the expected close; the missing terms determine whether a long VAL/short RIG hedge is investable.
- Treat BORR as a secondary consolidation read-through rather than a direct beneficiary. Consider a small 6-9 month long only if jackup utilization and forward contract rates continue rising; use a stop on material contract cancellations or renewed distressed-rig sales, which would show that floater consolidation is not transmitting to the jackup market.
- Monitor offshore-capex leading indicators rather than oil alone: FID announcements from Petrobras, Exxon Mobil and Chevron, plus 2027 tender volumes. A sustained decline in awards over the next two quarters would warrant reducing all offshore-driller exposure despite progress toward closing.
More News
- Trump says Iran war could end after U.S. elections as Hormuz tensions persist
- Mark Ruffalo says Paramount’s $111 billion Warner Bros. deal ‘Will stifle creativity, weaken free speech, and cost people their jobs’
- States, cities sue U.S. agencies over weaker vehicle fuel economy rules
- David Ellison says combined Paramount and Warner Bros. Discovery will be named Skydance
- G7 Leaders’ Statement on global energy security and market stability
- Trump vs Europe as US presses for release of emergency diesel stocks
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Tools for Family Offices: A Stack by Decision Type
- Reading Conviction in the Tape: What Level 3 Order Book Data Really Tells Discretionary PMs