
Creality Unveils K3, SPARKX i8 and Expanded Creative Ecosystem at IFA 2026
Source: PR Newswire
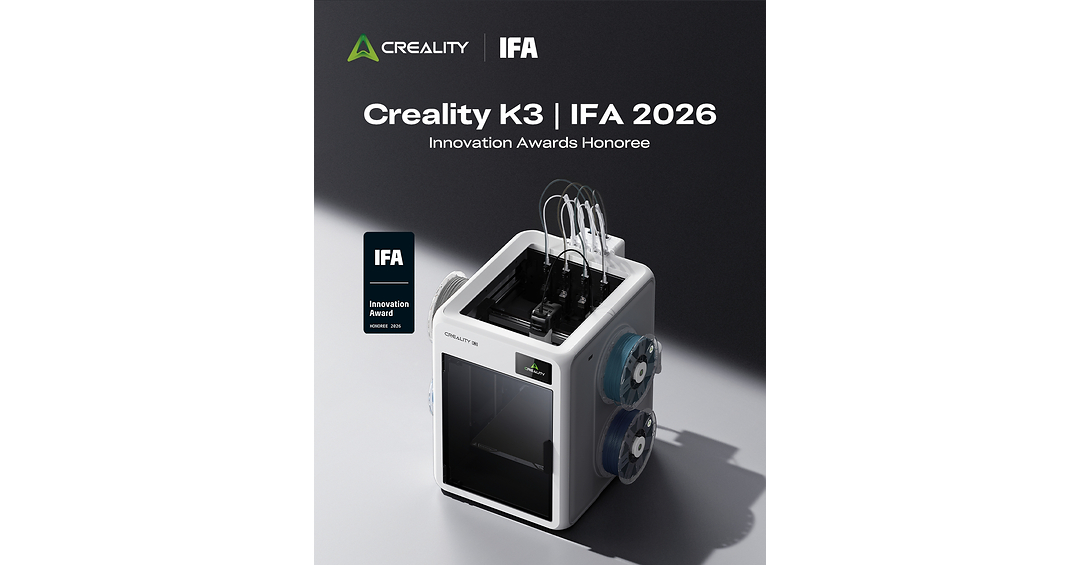
Creality unveiled its IFA 2026 3D-printing portfolio, led by the award-recognised K3 multichannel/multimaterial flagship (KliTek nozzle swaps in 4.8 seconds), claiming up to 80% lower total print time and up to 85% less material waste. The company also launched the IFA Innovation Awards 2026 Winner M1 filament recycling system (with an R1 shredder for turning failed prints into new filament) and expanded its multicolour, resin, scanning, and laser lineup. Overall, the news is innovation- and sustainability-tilted with moderate positive impact for Creality-related sentiment, but no direct financial guidance or pricing was provided.
Analysis
This reads less like a single-product launch and more like a bid to widen the category from hobbyist hardware into a recurring workflow business. If the throughput and waste claims hold in third-party testing, the economic winner is not necessarily the printer vendor itself but the installed-base ecosystem: filament, resin, accessories, and service/software attach should rise as users print more often and in more complex configurations.
The competitive pressure is most acute for public low-end incumbents such as SSYS and DDD, where differentiation on hardware alone is already thin. A credible jump in ease-of-use plus multi-material capability can force price competition at the entry and prosumer tiers, but the bigger second-order effect is that it raises the bar for what "good enough" looks like, which can compress ASPs across the category over 6-18 months if peers cannot match reliability.
The market should not overreact to sustainability messaging: recycling features sound strategic, but near term they are more likely to reduce filament unit growth per print than create a true moat. The real catalyst path is channel sell-through and repeat usage data over the next 1-2 quarters; if early reviews show calibration or reliability issues, the entire thesis deflates quickly because these products only matter if they materially reduce operator downtime. For now this is a modest positive for adoption, not a clean fundamental inflection for public comps.
Contrarian view: consensus may be underestimating how much open-ecosystem positioning limits pricing power. If customers can mix and match materials and accessories, the value capture shifts away from the printer OEM toward consumables and adjacent tooling, which is structurally less exciting for equity holders than the headline innovation suggests.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- Short SSYS on any sympathy rally over the next 1-3 weeks; thesis is that hardware feature parity headlines do not fix weak demand, and the stock can give back 8-12% if no order or margin improvement follows. Stop if the next earnings update shows meaningful system-unit acceleration or gross margin expansion.
- Do not chase DDD on this news; treat it as a watchlist name only. If the stock rallies 5%+ on category enthusiasm without evidence of better channel inventory or recurring consumables growth, use that strength to fade into a 1-2 month horizon.
- Set an alert on PRNT for confirmation rather than anticipation: only consider a modest long if industry checks show prosumer/SMB unit growth and stronger accessory attach over the next quarter. Without that data, the risk/reward is poor because the market is paying for a narrative rather than earnings leverage.
- Track filament/resin volume indicators and third-party reviews over the next 30-60 days; if reliability issues surface, expect the whole 3D-printing basket to derate quickly as the market realizes the claims are more marketing than monetizable demand.
More News
- 'Cannot play hide and seek': Singapore minister's warning over haze sends agricultural stocks lower
- BlackRock, GIC among investors chasing Indian telecom major Jio's IPO as anchor bids top $26 billion
- Nscale, Anthropic Eye $45 Billion Cloud Deal as AI Trade Rebounds
- Volkswagen bet on Xpeng to save its China business. It’s not going to plan
- Gartner analyst behind tech rout: AI returns are not yet large enough to justify neocloud build-out
- Elice shares plunge 28% on debut as investor doubts over AI trade deepen