
Behavior Frontiers Opens First-Ever Orange County ABA Therapy Center in Brea, CA
Source: PR Newswire
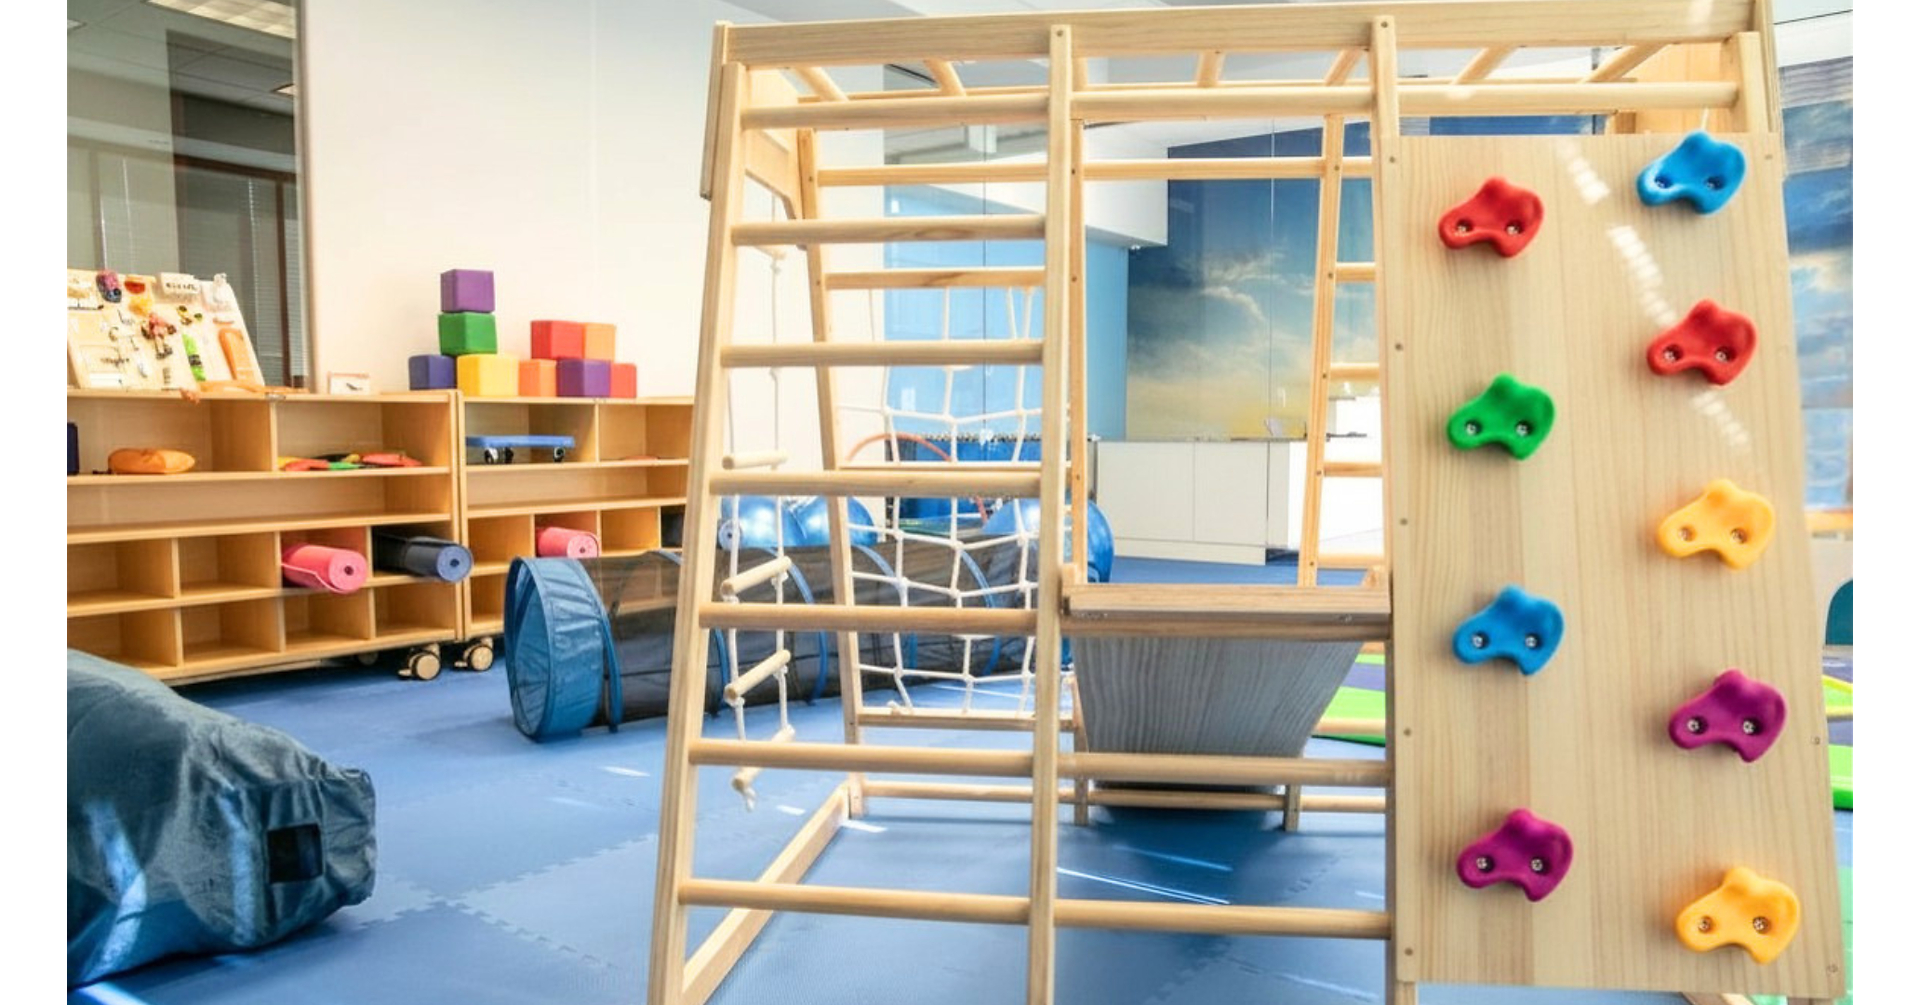
Behavior Frontiers opened its first Orange County center-based autism care location in Brea, CA (500 S. Kraemer Blvd, Suite 100B), serving toddlers and young children with ASD under age 6, with enrollment now open. The facility offers individualized 1:1 ABA early intervention, accepts major insurers (e.g., Anthem Blue Cross, Aetna, Blue Shield of CA, UnitedHealthcare), and uses its PrioraCare platform to track progress in real time and adjust therapy plans quickly. The news is supportive for the company’s expansion and service capacity, but it is largely local/operational with limited immediate market impact.
Analysis
This reads as a local capacity add, not a new-demand shock. The investable signal is that center-based ABA can lift therapist productivity and retention versus purely home-based delivery, but reimbursement remains the binding constraint; any economic benefit accrues mainly to operators with enough referral density and data discipline to keep utilization high. For public markets, the most plausible beneficiaries are the managed-care names with large pediatric behavioral-health books and the claims-management stack around them, not the opening company itself; STT and SCPAF have no obvious direct read-through.
The second-order effect is competitive, not financial: a center format can pull volume away from fragmented in-home providers by offering scheduling efficiency, peer interaction, and easier supervision, which matters in a staffing-constrained niche. That said, this also tends to surface authorization friction faster, because payers get more visible, trackable sessions and can tighten reviews if utilization outruns outcomes. Near term, the market should ignore it; over 1-3 months the catalyst is any payer commentary on ASD utilization trends, and over 6-18 months the key question is whether California capacity additions show margin leverage or merely absorb unmet demand.
Contrarian view: the consensus tends to treat every autism-service expansion as structurally bullish, but that only holds if reimbursement and staffing scale faster than claims scrutiny. If the opening is mainly a geographic expansion into already-known demand, revenue impact is small and the equity implication is basically a marketing datapoint. What would falsify even a mild positive read-through is flat ASD claims growth, rising denials, or evidence that center-based conversion is cannibalizing higher-margin home care rather than expanding the patient funnel.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Key Decisions for Investors
- No direct trade in STT or SCPAF; treat this as non-catalytic unless we see a verifiable exposure channel in filings or segment commentary.
- Set a 1-3 month alert on UNH, ELV, and CI for any commentary on pediatric behavioral-health utilization, prior-auth rates, or autism-related medical cost trends; only act if utilization rises without offsetting MLR pressure.
- Watch CNC as the highest-beta payer proxy if California Medicaid ASD utilization accelerates; positive only if the trend is broad-based and not isolated to one region.
- If you want a relative-value expression, consider a small long UNH / short CNC pair only after confirming ASD utilization is rising in commercial plans faster than in Medicaid; otherwise stay flat.
- Falsifier: if next quarter shows no increase in autism-related claims, or if denial rates rise, fade any bullish interpretation and avoid chasing healthcare proxies.
More News
- Musk says Terrafab chip factory could outperform rivals despite challenges
- Nvidia GPUs are everywhere. Here are the ways companies are accessing them
- Stocks saw new highs and big declines: How the volatile AI trade moved last week's market
- Will Warner Bros. kill Skydance — or will David Ellison kill Warner Bros?
- The world needs Ukraine’s grain. Its farmers are running out of reasons to plant
- Cerebras Is About as Big as Nvidia's Data Center Business Was Nearly a Decade Ago. The Similarities Mostly End There.
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AlphaSense vs Hebbia vs AllMind: Choose by Workflow
- AllMind Discusses Ontario's AI Economy with Minister Stephen Crawford and Supply Ontario CEO James Wallace