
HD Hyundai Heavy Industries to Invest KRW 1 Trillion in Future Engine and SMR Businesses
Source: PR Newswire
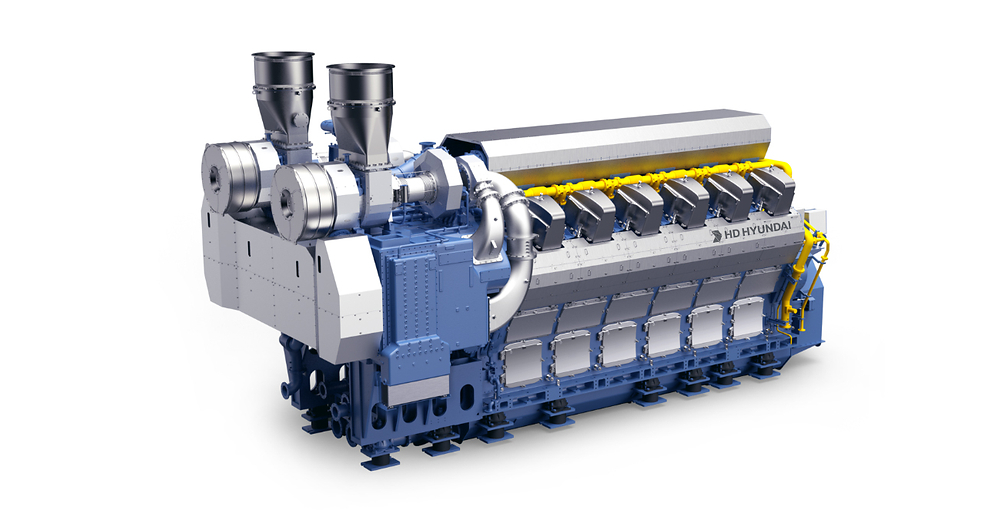
HD Hyundai Heavy Industries will invest KRW 1.0722 trillion to build a 3 GW land-based power-engine plant in Ulsan and a dedicated SMR-equipment manufacturing facility, targeting operations in 2028 and 1H 2029, respectively. The engine expansion is expected to lift total HiMSEN capacity from 3 GW currently to 7.2 GW by 2030, addressing accelerating AI data-center electricity demand. The company is also positioning for an OECD-projected 150 GW global SMR market by 2050, following U.S. data-center power-equipment supply contracts worth KRW 1.5831 trillion signed earlier this year.
Analysis
The near-term equity question is capital allocation, not the AI-power narrative: the investment creates a multi-year FCF drag before meaningful new capacity contributes. For 329180 KS, valuation support will require a visible conversion of announced commercial activity into firm backlog, deposits, and margin-bearing delivery schedules; otherwise the market is likely to capitalize the capex immediately while discounting revenue until 2028. Vertical integration in castings and crankshafts could ultimately improve delivery certainty and gross-margin resilience, a meaningful advantage while reciprocating-engine supply remains constrained.
The more investable second-order effect is substitution: data-center developers facing grid-interconnection delays are increasingly buying dispatchable on-site generation, which favors fast-delivery engine packages over utilities and conventional turbine projects. This is competitively adverse at the margin for CAT and CMI in exported large-generator sets, although their installed base, dealer networks, and North American service capability remain material defenses. The Korean manufacturer’s U.S. penetration should be judged by service-partner buildout and warranty provisions, not contract headlines.
SMR optionality should receive little current earnings credit. Dedicated manufacturing can create a scarce fabrication asset, but demand is contingent on reactor design certification, project financing, and customer offtake; these are likely 2029-2035 catalysts rather than a 12-month earnings driver. The contrarian risk is that AI-load forecasts are overbuilt relative to actual utilization, while gas pipeline constraints and permitting delay generator deployments even when data-center demand is real.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.62
Key Decisions for Investors
- Do not chase 329180 KS solely on the announcement; accumulate only after the next two reporting periods show incremental land-power backlog, customer deposits, and a credible capex/FCF bridge. Thesis horizon: 12-24 months; invalidate if management raises capex again without backlog conversion or guides to material margin dilution.
- Establish a small 6-12 month relative-value watch: long 329180 KS versus short WRT1V FH only if disclosed U.S. power-equipment orders and service capacity accelerate. The trade captures potential share gains in constrained medium-speed generation; stop out if Wartsila order intake outgrows HD Hyundai’s power backlog for two consecutive quarters.
- Maintain exposure to the more immediate data-center power bottleneck through CAT or CMI rather than pricing SMR optionality into 329180 KS. Reassess after U.S. data-center developers disclose 2027 power-delivery schedules; a slowdown in leased MW absorption or generator lead times would weaken the entire on-site-power theme.
- Treat 034020 KS and BWXT as higher-beta SMR manufacturing proxies only after identifiable reactor awards, regulatory milestones, and funded customer projects emerge. Until then, avoid using the facility build as a nuclear-cycle catalyst; the key falsifier is continued project slippage beyond 2029.
More News
- Here’s the ‘core economic flaw’ in the AI bull case as stock and bond trades unravel, according to a top economist
- Israelis hold final rally against Netanyahu ahead of what may be the most consequential election in the country’s history
- Biotech stocks are surging. How investors can play the new drug innovation boom
- AI funding fears rattle Wall Street. Here's how we're adjusting our portfolio
- Braskem creditors, shareholders near deal on $11bn debt restructuring
- Instacart reportedly discussed selling itself with DoorDash and Uber