
Micron: It's Different This Time - Buy At 6x Earnings Before AI Agents Rerate It
Source: seekingalpha.com
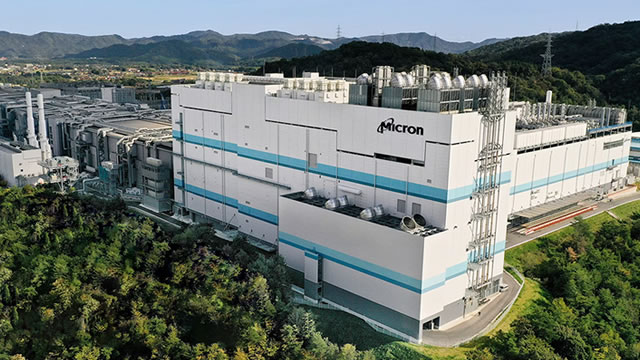
Micron was upgraded to Buy on robust AI-driven demand and a stated valuation of 6x earnings. The article reports Q4 revenue surged 379% year over year to $54.2B, gross margin reached 87%, and net cash totaled $68.3B. Management expects supply-demand conditions to remain tight through 2028, with more than 75% of 2028 shipments already committed.
Analysis
The stated valuation case is not investable until the underlying figures are reconciled to Micron's SEC filings and consensus estimates. The revenue, margin, and net-cash claims imply an earnings-power step change far beyond a normal memory-cycle recovery; if unsupported, the apparent 6x multiple is a denominator error rather than a valuation opportunity. This is particularly important in DRAM/NAND, where peak-cycle margins and forward estimates can reverse rapidly once capacity additions or weaker handset/PC demand emerge.
If verified, the more durable implication would be that high-bandwidth memory (HBM) is changing Micron's mix, reducing commodity-memory earnings volatility and justifying both higher through-cycle margins and a multiple rerating versus prior-cycle norms. The nearer-term risk is that customer supply commitments are not equivalent to non-cancellable revenue: hyperscalers can alter accelerator architectures, qualify Samsung Electronics or SK Hynix supply, or defer deployments. Over 6-18 months, the critical falsifier is not shipment commentary but whether HBM pricing, bit-growth, and gross-margin guidance remain resilient as industry supply responds.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.78
Ticker Sentiment
Key Decisions for Investors
- Do not act on the cited financial metrics until they are matched against MU's latest 10-Q/10-K, earnings release, and consensus EBITDA/EPS; set this as a data-validation alert rather than a Buy recommendation.
- If filings confirm a sustained HBM-led margin inflection, initiate a 1-3 month long MU position only after next-quarter revenue and gross-margin guidance is raised or maintained; target a 15-20% upside rerating, with exit if gross-margin guidance declines by more than 300 bps or HBM qualification timing slips.
- For a cleaner AI-memory expression after validation, consider long MU versus short SOXX in equal beta-adjusted dollars over 3-6 months; this isolates company-specific HBM mix upside while reducing broad semiconductor multiple risk.
- Avoid chasing a single-name move before earnings. A defined-risk alternative is a 6-9 month MU call spread, sized to lose no more than the premium, but only if implied volatility is below the stock's post-earnings realized volatility and verified estimates support the stated earnings base.
More News
- Stocks remain under the thrall of higher yields and higher oil. Here's what's ahead
- Nasdaq Index: Record High as Weak Payrolls Cut Rate-Hike Bets and Yields Fall
- Nvidia is a 'best in breed' stock on sale. Here's why I'm buying
- Micron sees the memory shortage tightening into 2028 after a record quarter
- CLSA raises Micron stock price target on strong memory pricing outlook
- Wall Street sets Micron (MU) stock price for 12 months