
10 Federal Acquires Second Shopping Center This Month With Fort Worth Retail Addition
Source: PR Newswire
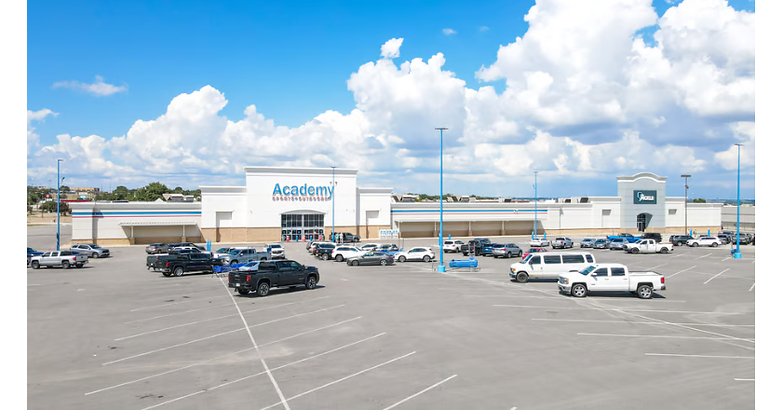
10 Federal acquired a 105,182-square-foot, Academy Sports + Outdoors-anchored shopping center on nearly 11 acres in Fort Worth, Texas, its second retail acquisition in September. The deal expands the company beyond self-storage into complementary commercial real estate, supported by Tarrant County's population, income and economic growth. 10 Federal operates 132 self-storage properties across 15 states and cited durable, necessity-oriented retail demand in the Fort Worth submarket.
Analysis
This is not a meaningful earnings catalyst for ASO: a single landlord transaction does not alter the retailer's store base, sales trajectory, or capital allocation. The marginal read-through is modestly constructive for the durability of well-located, value-oriented big-box retail real estate in Dallas-Fort Worth, where replacement costs and population-led demand can support occupancy and landlord rent-growth ambitions. For ASO, the relevant mechanism is lease economics: stronger local retail demand improves renewal leverage over a multi-year horizon, but may raise occupancy costs when leases roll.
The more investable implication sits with retail REITs exposed to Sun Belt necessity and service retail, notably REG and KIM, rather than ASO. Private acquisitions signal continued bid support for suburban retail centers, which can narrow implied cap rates and underpin NAV estimates; however, one sponsor's purchase offers no price, cap rate, financing, or occupancy disclosure, so it cannot validate sector-wide valuation expansion. At current signal strength, this is a watch item rather than a catalyst.
Contrarian risk: DFW growth is widely recognized and may already be reflected in Sun Belt retail valuations. If consumer spending decelerates or sporting-goods demand weakens, ASO's traffic productivity—not its landlord's asset value—will determine equity performance. Watch ASO same-store sales, gross-margin guidance and lease-expiration disclosures over the next two earnings cycles; a guidance reduction would negate any local real-estate optimism immediately.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Ticker Sentiment
Key Decisions for Investors
- No standalone ASO trade on this announcement. Maintain ASO only if the core thesis is supported by upcoming same-store sales and gross-margin guidance; reassess on any FY2027 earnings-guide cut, which would outweigh this real-estate read-through.
- Add REG or KIM to the 1-3 month watchlist as liquid public proxies for private-market demand for Sun Belt necessity retail. Initiate only if subsequent comparable transactions disclose cap rates below public-implied levels or if quarterly leasing spreads and occupancy accelerate; absent that evidence, risk/reward is insufficient.
- For existing ASO exposure, monitor DFW and broader Sun Belt store productivity against rent renewals over 6-18 months. A pattern of positive comparable sales with stable SG&A-to-sales would support operating leverage; negative comps coupled with rising occupancy expense would favor reducing exposure.
More News
- Broadcom to lend Anthropic up to $42 billion to lease its chips, filing says
- $8.2B acquisition validates AI-picked chip stock: +20% since June
- Nike Warns Sales Slump Will Worsen This Fiscal Year
- Nuveen CEO on Schroders Deal, Plans for Combined Company
- New Mexico wants Meta to pay up to $40 billion in penalties after data privacy trial
- Paramount promised 30 movies a year to win Warner Bros. Losing Miramax if it fails may not scare it