
This Growing Midstream Empire Pays 8.3%
Source: seekingalpha.com
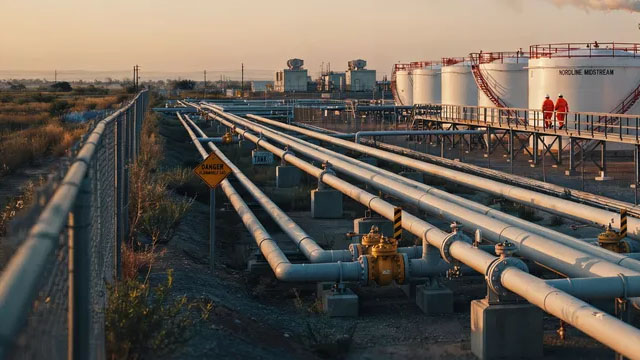
Western Midstream Partners offers an 8.3% yield, supported by fee-based contracts and expanding infrastructure in the Delaware and DJ Basins. Its focus on produced water and expected highly contracted, earnings-accretive projects is presented as supporting targeted mid-single-digit distribution growth.
Analysis
The bullish case is not the headline yield; it is whether incremental produced-water and basin infrastructure earns returns above its funding cost while preserving distribution coverage. If new projects are genuinely contracted, they can reduce volume and commodity-price exposure—but do not eliminate counterparty, renewal, or basin-activity risk. Produced-water assets may also carry permitting, disposal, and execution risks that a simple fee-based label understates. Competitors with established water networks and existing producer relationships could constrain pricing, while weaker producer activity would challenge volumes and project economics across the basin.
Near term (days to weeks), the yield may attract income buyers, but rate moves and risk appetite can dominate a high-yield midstream unit’s price. Over 1–3 months, the key test is disclosed project contract terms, capital spending, leverage, and distribution coverage—not management’s accretion language alone. Over 6–18 months, successful buildout could support cash-flow growth; cost overruns, delayed permits, or weaker basin activity could instead pressure coverage and raise funding risk.
Contrarian point: an 8.3% yield may look like a bargain, but it can also be the market’s required compensation for leverage, capital intensity, or distribution uncertainty. The supplied information does not establish valuation, coverage, debt capacity, or project returns, so it is insufficient to underwrite the yield as safe or to justify an outright relative-value call.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- Keep WES on an income watchlist rather than buying solely on yield. Before initiating, verify distribution coverage, leverage and maturities, project-level capex and contracted volumes, and whether guidance explicitly funds both growth spending and distributions.
- If those checks are satisfactory, consider a staged long position after the next filing or project update confirms coverage and funding; size it as a rate- and energy-activity-sensitive income exposure. Reassess or exit if coverage weakens, leverage rises materially, or project costs/permits undermine expected returns.
- For a relative-value screen, compare WES with established midstream peers on valuation, leverage, distribution coverage, and contract quality; do not assume the yield premium is mispricing until those measures are comparable. A sustained rise in long-term Treasury yields is a near-term thesis risk.
More News
- AI Doubts Spread Cracks in Equities, Credit Markets: Evening Briefing Americas
- US-Iran war, then and now: How the landscape has changed since February
- 10-year Treasury yield drops back to 5% this week as investors seek cover from AI worries
- With earnings in rearview mirror, SpaceX-Tesla merger chatter takes center stage
- Stocks Fall as Oil Rally Keeps a Lid on Treasuries
- Oil Climbs on Threats of a Widening War in Middle East