
ARIDGE and UAE Authorities to Jointly Establish the World's First Personal Flying Car Regulatory Sandbox
Source: PR Newswire
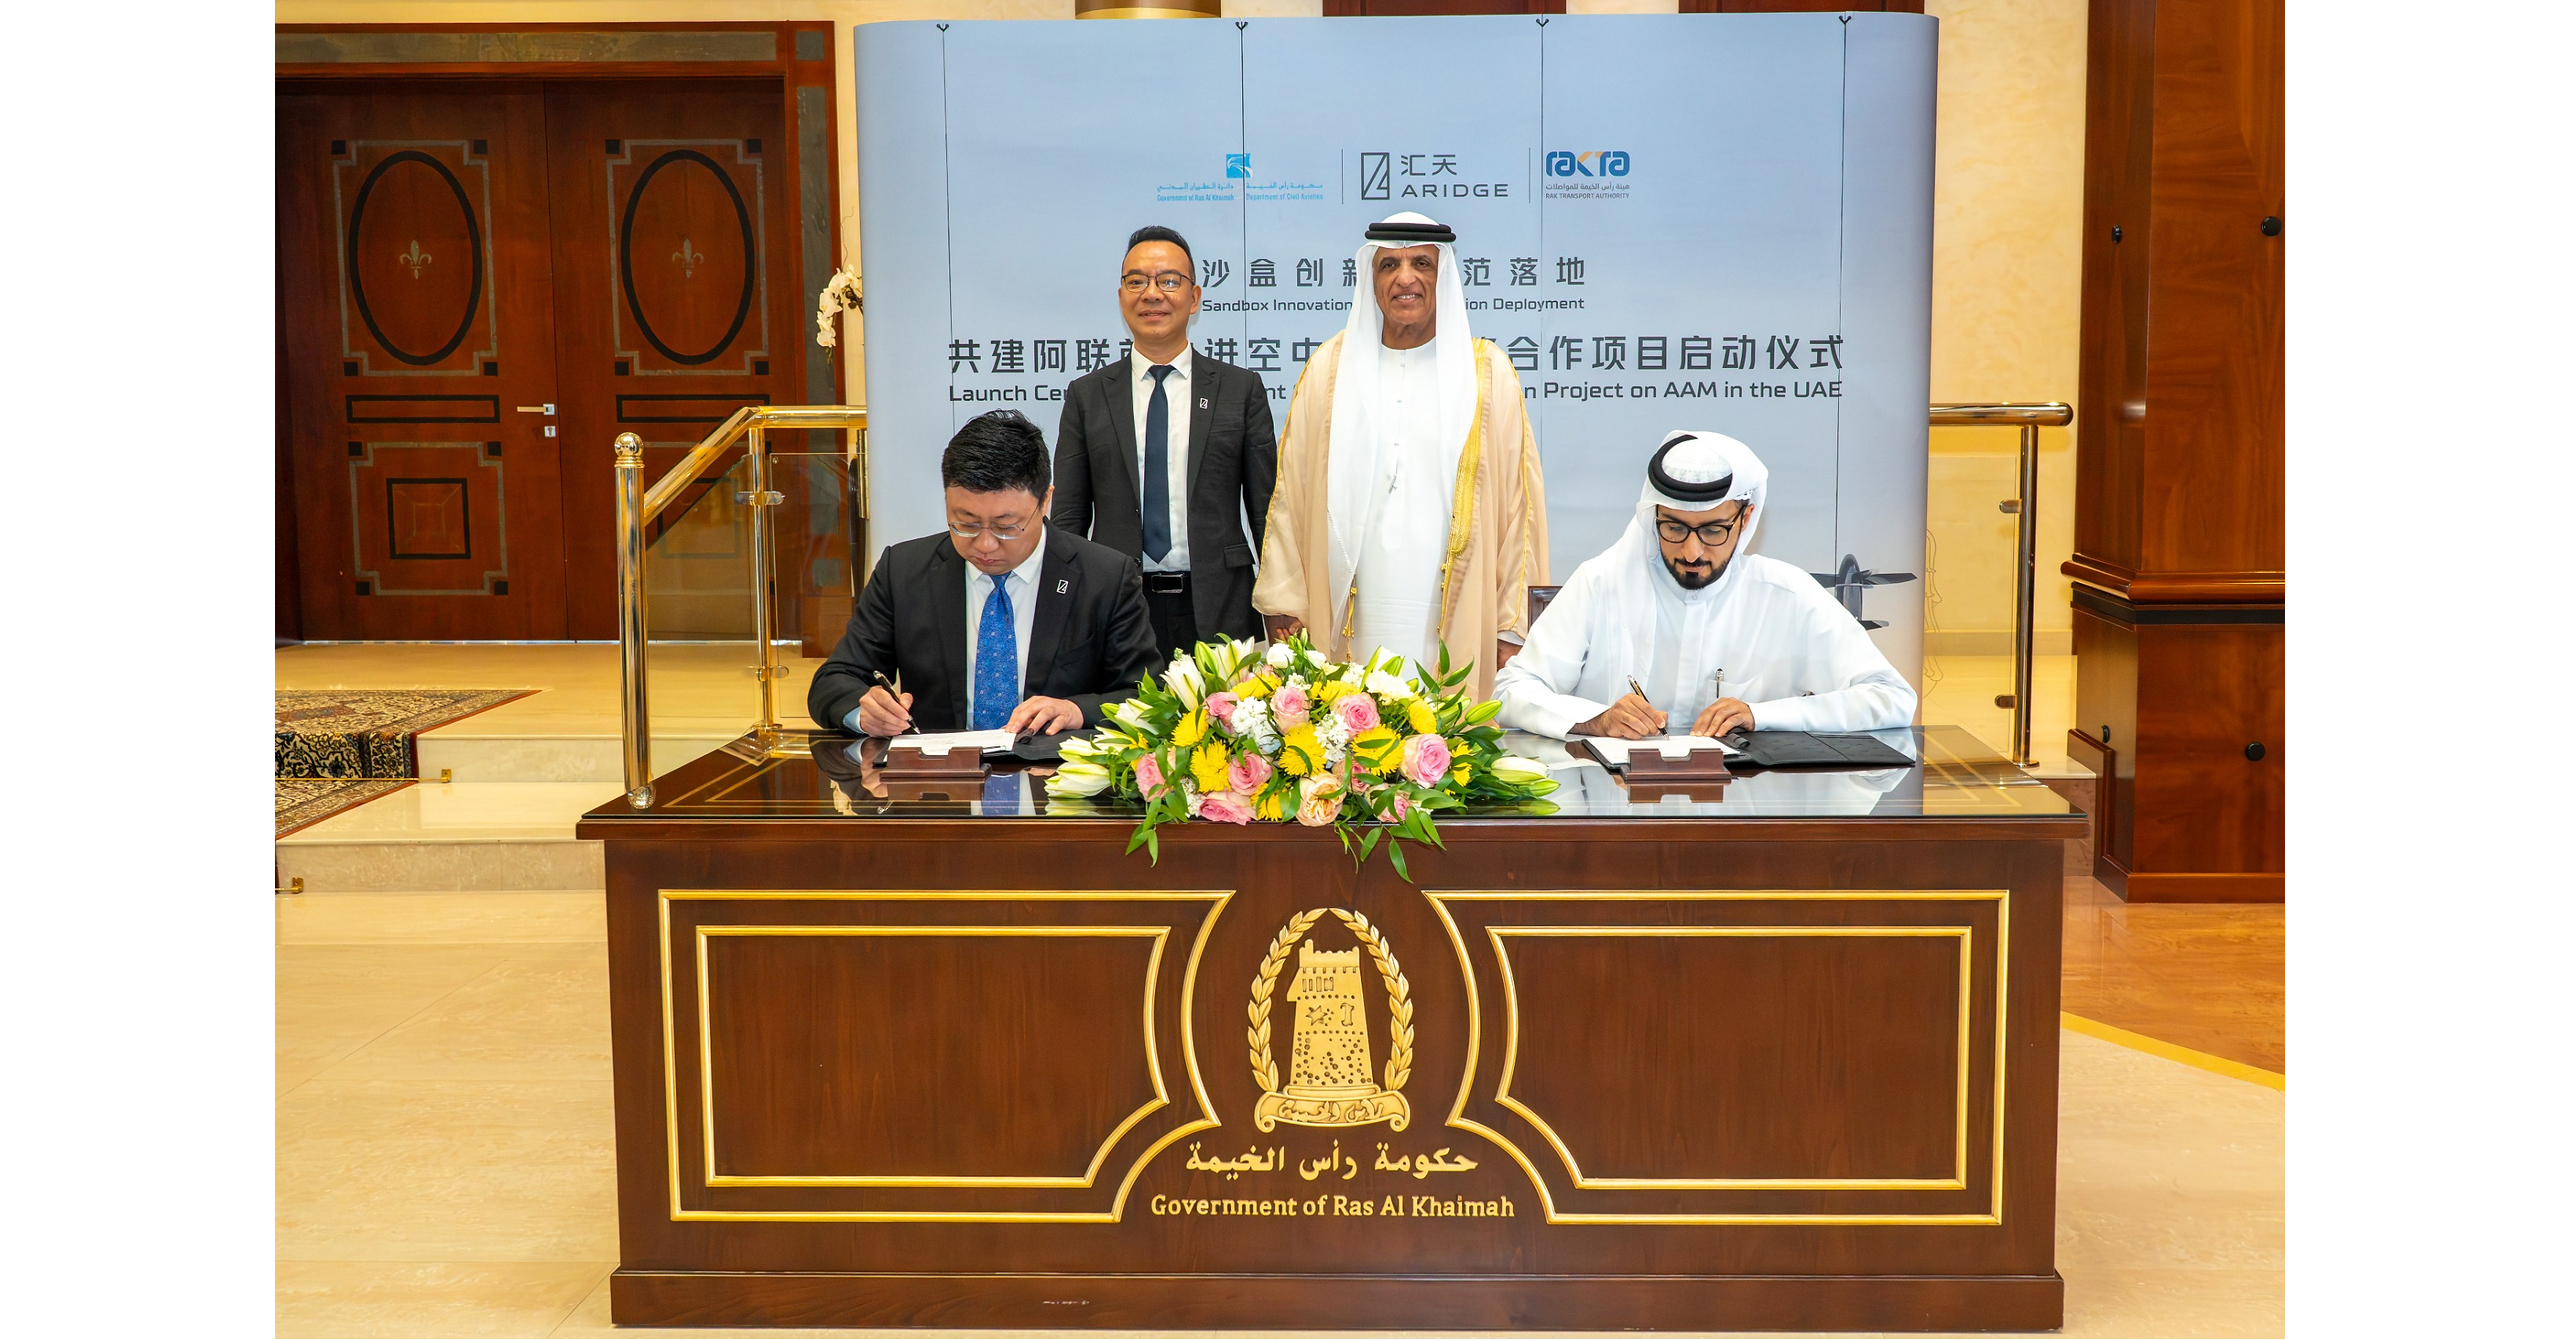
ARIDGE, formerly XPENG AEROHT, signed a strategic agreement with Ras Al Khaimah under UAE GCAA oversight to establish the world's first regulatory sandbox focused on personal flying cars. The program will validate flights in desert conditions and support a planned Abu Dhabi–Ras Al Khaimah inter-emirate advanced-air-mobility demonstration route, testing airspace coordination, ground operations, passenger handling and safety procedures. The agreement gives ARIDGE its first national-level Middle East regulatory-sandbox entry and supports expansion of localized commercial air-mobility services.
Analysis
The market should assign limited near-term value to this for XPEV: the relevant asset remains a capital-intensive, pre-revenue subsidiary whose certification, manufacturing, insurance and operating-capability requirements sit well beyond an EV OEM’s core earnings model. Any initial equity response is more likely a sentiment-driven sum-of-the-parts re-rating than a change to XPEV’s 2026-27 delivery, gross-margin or free-cash-flow estimates. The more material signal is that Gulf regulators may become a lower-friction proving ground for Chinese AAM hardware, potentially reducing the commercialization lead held by US-listed eVTOL peers.
For JOBY, ACHR and EVTL, the competitive implication is mixed: a credible Middle East operating pathway validates the region as an early-adopter market, but it also raises the risk that airport, vertiport, fleet-partner and sovereign-capital commitments become fragmented among competing platforms. ARIDGE’s modular consumer-oriented architecture is not a direct substitute for high-frequency airport shuttle fleets; however, successful operational validation would pressure the narrative that US FAA certification alone confers durable global market access. EH is the closest listed read-through because a Chinese manufacturer gaining overseas operating data could strengthen investor confidence in China-origin aircraft exportability.
Over the next 1-3 months, the key catalyst is whether the program produces independently verifiable milestones—defined flight permissions, a disclosed local operating partner, aircraft orders/deposits, or funding commitments—rather than promotional demonstrations. Over 6-18 months, recurring desert-condition testing data could be strategically useful for battery thermal management and reliability, but it may equally expose endurance degradation, maintenance burden and insurance costs that undermine unit economics. The thesis is falsified if XPEV discloses material incremental funding needs without third-party capital, or if the project does not progress to commercial approvals and contracted demand by 2027.
Consensus may overread national-level regulatory engagement as de-risked commercialization. A sandbox can accelerate learning but does not establish type certification, production certification, route economics, passenger liability frameworks or scalable air-traffic integration; these are the bottlenecks that determine valuation. Accordingly, this is a watch-list catalyst rather than a reason to underwrite a material uplift to XPEV’s EV earnings multiple.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.62
Ticker Sentiment
Key Decisions for Investors
- No standalone XPEV position solely on this development; treat any >5% event-driven rally without disclosed orders, third-party funding or certification milestones as a potential trim/short-term fade opportunity, subject to broader China EV beta.
- Monitor XPEV disclosures through the next two earnings cycles for AAM R&D, capex, subsidiary financing and order metrics. Reassess long exposure only if external capital limits XPEV cash burn while a contracted commercial pathway is disclosed.
- For AAM thematic exposure, prefer a relative-value watch: long JOBY / short ACHR only after confirmation that UAE infrastructure or fleet partnerships favor certified shuttle operations rather than personal-flight products. The pair is invalidated by Archer securing equivalent Gulf commitments or by Joby certification/production timelines slipping.
- Set an alert on EH as the higher-beta China AAM read-through: consider a tactical long only upon independently confirmed overseas commercial approvals or paid orders, not sandbox announcements; cap risk tightly because certification and geopolitical/export constraints can overwhelm operating milestones.
More News
- An unaffordable car market highlights Iran’s cost-of-living crisis
- Flames, smoke seen near Riyadh airport; Houthis claim attacks on Saudi capital
- Polish prime minister warns Russia is planning drone or rocket strikes on European countries supporting Ukraine as ‘Carpathian Eight’ meet
- Trump vows to create an ‘AI Force’ and nods to justice system after rejecting calls to slow down industry. ‘Rather, we will cherish it’
- ‘We’ve been free-riding off Beijing in a weird way’ — Oil prices are high but could be much worse. Trump has China’s Xi to thank for that
- Polymarket fraud concerns mount as company prepares for potential IPO
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Tools for CFA Charterholders: An Evidence Standard
- Weekly Update: Unstructured Data Search, Ask AI, and Advanced Futures Data