
Vedení KUKA navštívilo Centron za účelem výměny zkušeností s inteligentní montážní výrobou
Source: PR Newswire
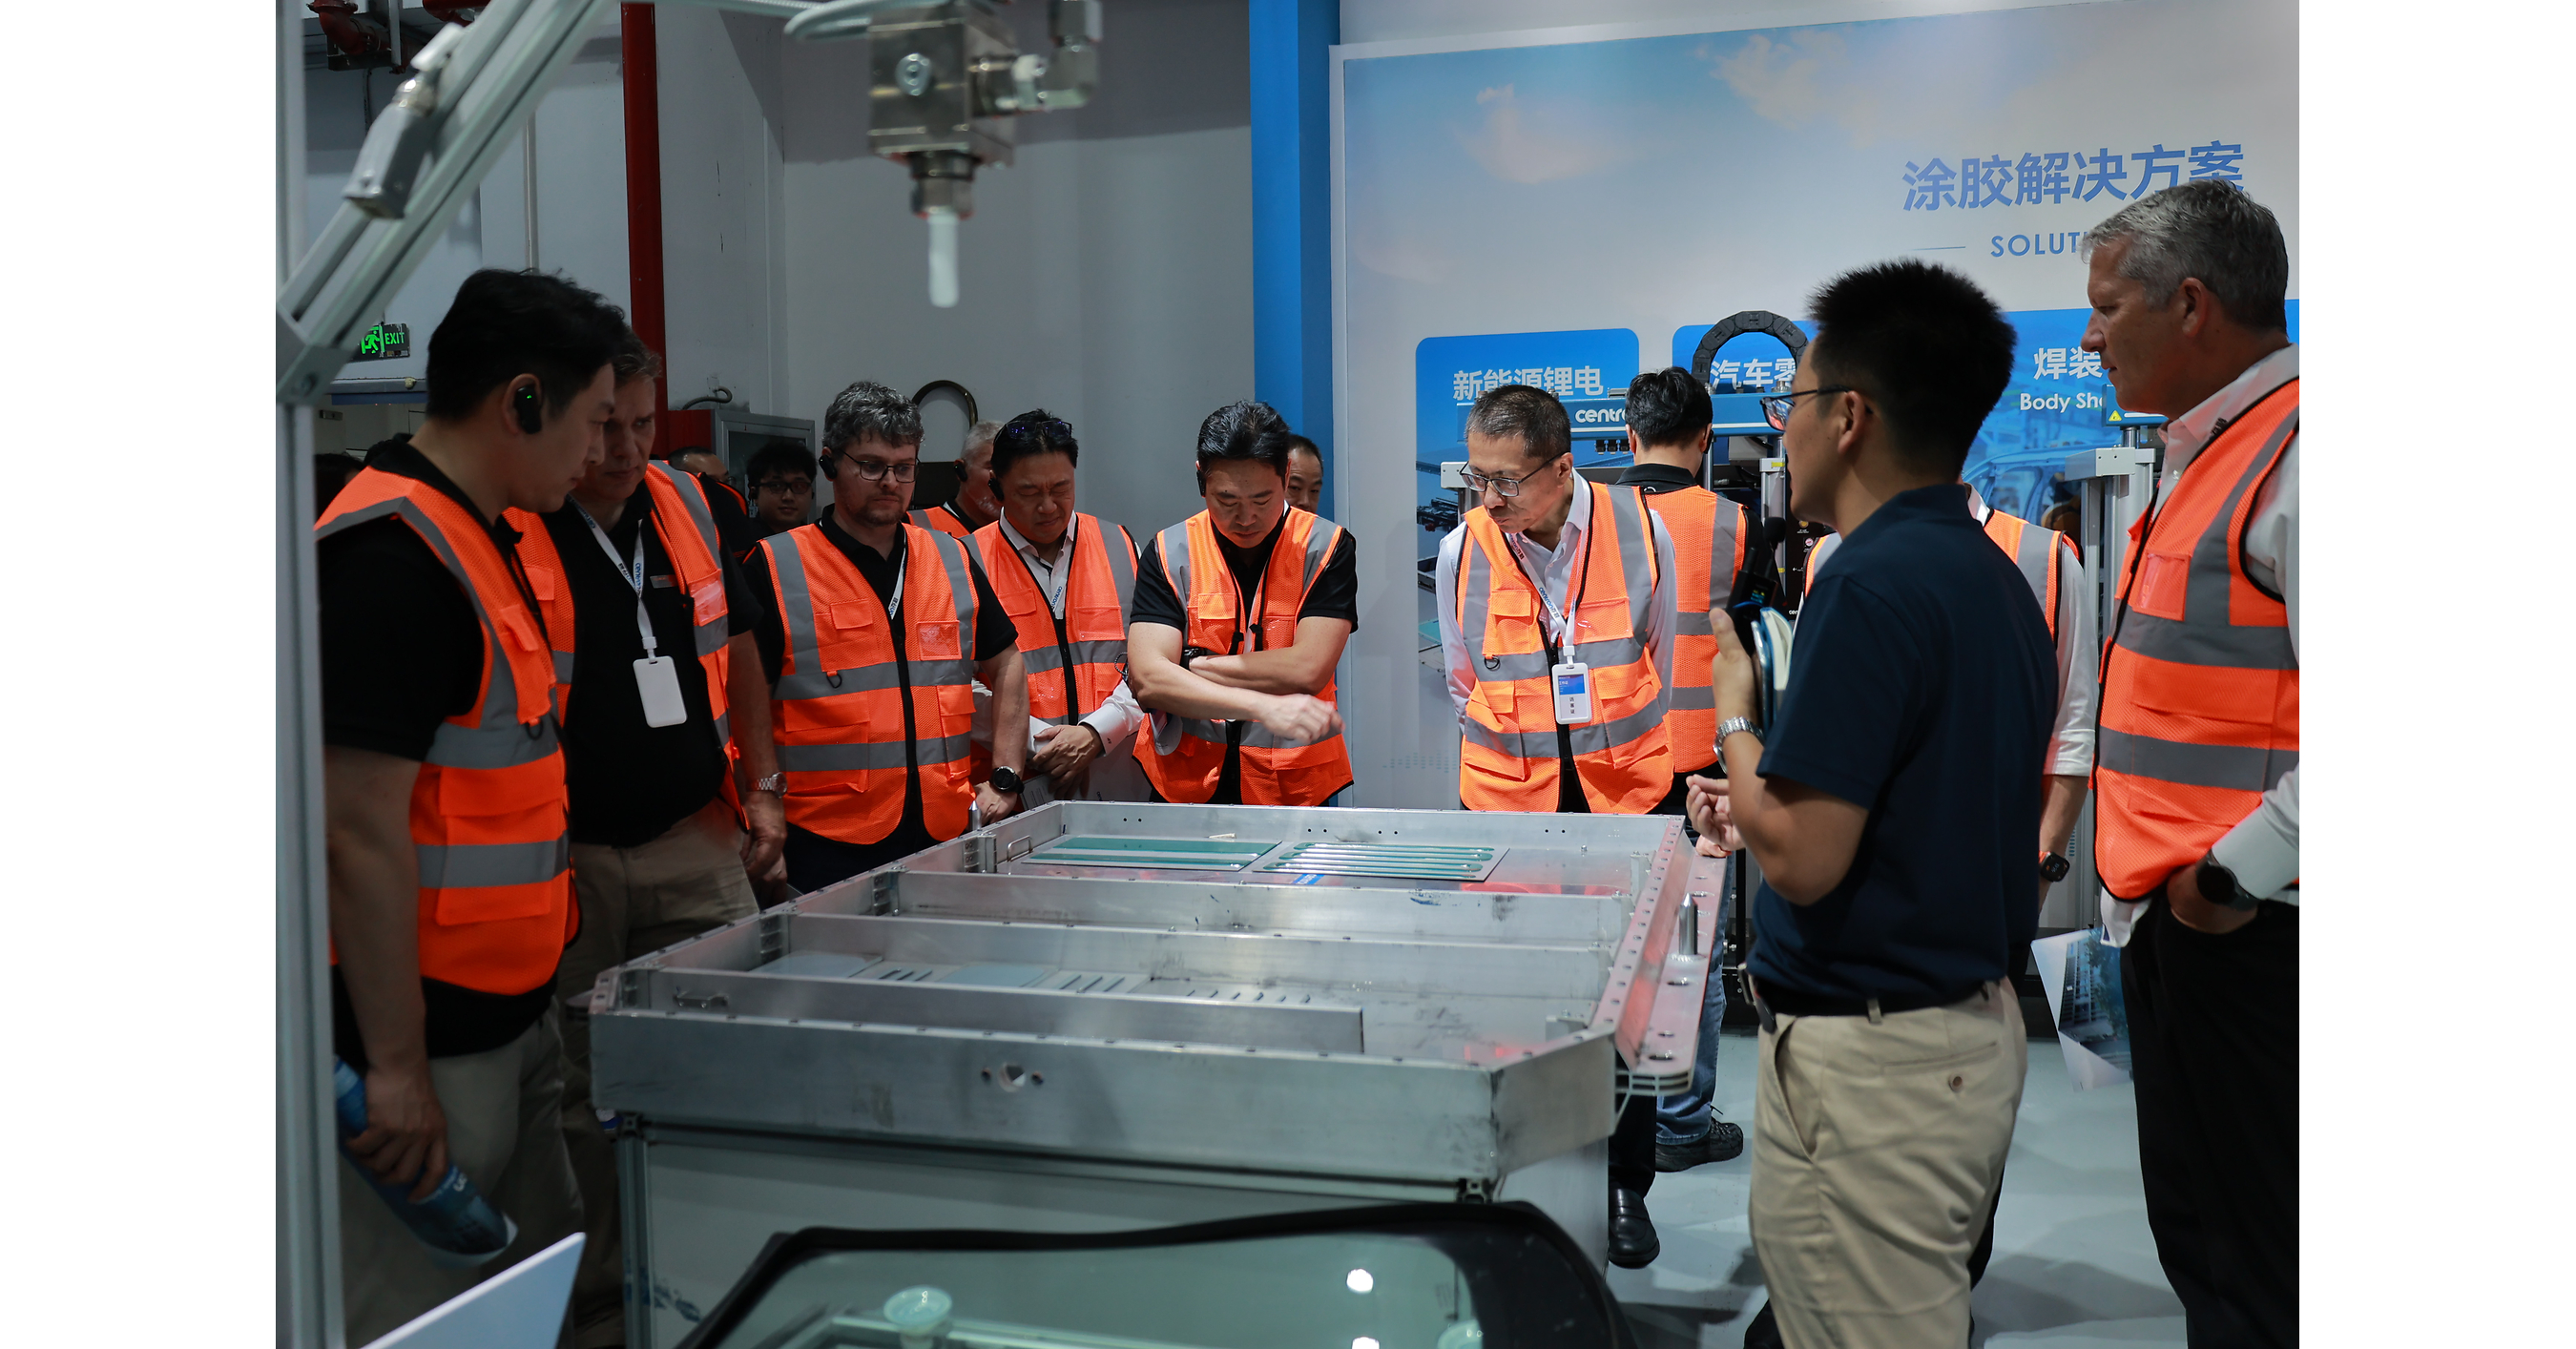
Vedení KUKA, v čele s viceprezidentem skupiny Midea, navštívilo závod společnosti Centron v Číně (1. září 2026) kvůli výměně zkušeností v oblasti inteligentní montážní výroby. Návštěva se zaměřila na produktové portfolio a výrobní kapacity Centronu (přesné dávkování, zalévání a kapková impregnace) a na technologie Leetx včetně utahování, lisování a automatického podávání šroubů. Článek nepřináší finanční výsledky ani konkrétní transakce, spíše potvrzuje oborový trend konvergence průmyslové robotiky a montážních technologií.
Analysis
This is best read as a channel-check on the automation stack, not as a direct earnings catalyst. The actionable implication is that value creation is migrating from standalone robot hardware toward the application layer: dispensing, potting, fastening, traceability, and software integration. That should be modestly supportive for companies with sticky process IP and installed-base service revenue, while pressuring pure-play robot OEMs if pricing remains competitive and integration becomes more modular.
The second-order dynamic is China localization. If a global player is spending time with a domestic integrator, that usually signals either a sourcing/partnering effort or a defensive response to local share loss; in both cases, the risk is that Western incumbents slowly cede the middle of the stack to Chinese vendors with better cost curves. Over 1-3 months, the real catalyst would be follow-through in orders, channel inventory, or disclosed design wins in EV/battery capex. Without that, the market should discount the news as relationship-building rather than revenue visibility.
Contrarian view: consensus may overestimate the breadth of the opportunity and underestimate margin pressure. Intelligent assembly is growing, but it is also becoming a feature set, which means the economic rent may accrue to the lowest-cost integrator and the vendor controlling consumables/service, not to every named automation company. Falsify the bullish read if China industrial capex rolls over, EV/battery equipment orders weaken, or gross margins fail to inflect despite reported partnership activity.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.08
Key Decisions for Investors
- No immediate trade on the PR alone; treat this as an alert item and wait for confirmatory order data over the next 1-2 quarters.
- If China automation spending re-accelerates, go long ABB over Rockwell Automation on a 1-3 month horizon: ABB has better leverage to cross-border process automation and China industrial demand, while ROK is more exposed to a U.S.-centric multiple de-rating if global factory orders soften.
- Use a China automation basket on weakness only if book-to-bill improves: add Inovance (300124.SZ) and Estun (002747.SZ) on a confirmed order-upturn; stop if industry capex or PMI fails to recover within 6-8 weeks.
- For a lower-beta expression, prefer long industrial software / traceability enablers over robot arms; the thesis is that margin accrues to integration and lifecycle service, not commodity hardware.
More News
- Indonesia stocks suffer biggest daily slump since 1998 as MSCI weighs downgrade
- One Singapore ship was sunk, but here's why others are still transiting the Strait of Hormuz
- Order to limit Starshield for Ukraine came from inside White House: Reuters reports
- The IPO drought is driving private equity-owned companies to the debt market to pay investors
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- Taiwan to curb AI chip sales to China for more U.S. alignment- Bloomberg
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- How the 2026 Milan-Cortina Winter Olympics Will Reshape Company Revenues and Stock Performance
- Can Hedge Funds Use ChatGPT? A Control Framework