
Brandywine Realty Trust: The End Of The 3151 Market Saga
Source: seekingalpha.com
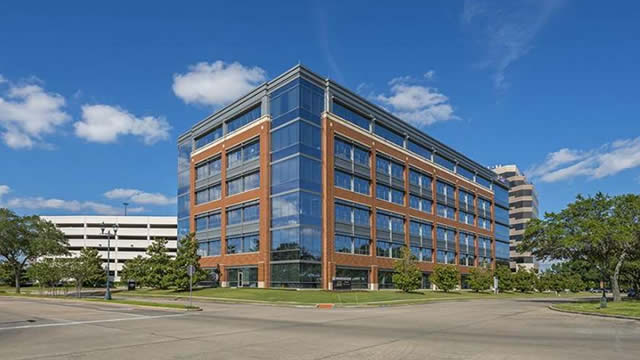
BDN sold its problematic 3151 Market property to Burlington Stores for $240 million, approximately 25% below its original development budget. The deal generates $168 million of net proceeds, adding needed liquidity and reducing balance-sheet risk, but crystallizes a costly multi-year strategic misstep and foregone upside from a stabilized life-science asset.
Analysis
For BDN, the relevant read-through is not the realized loss but the implied liquidity runway: net cash proceeds reduce near-term refinancing pressure and may narrow the discount at which public-market investors capitalize its remaining office portfolio. The offset is that the transaction crystallizes a weak private-market valuation benchmark, which lenders and equity investors can use to demand higher cap rates on comparable non-core dispositions. Over the next 1-3 months, BDN's equity response should depend on whether management directs proceeds toward debt retirement rather than recurring operating deficits or additional redevelopment spend.
BURL acquires a large-format, infill retail location at a basis likely below replacement cost, but the financial impact is immaterial relative with its enterprise value. The more useful implication is competitive: retailers with strong traffic and balance sheets can selectively convert distressed office or mixed-use assets into stores, distribution-adjacent facilities, or parking-supported retail nodes. This favors BURL, TJX, ROST and potentially DG versus leveraged landlords that must sell assets into a thin buyer pool; it is also mildly negative for nearby marginal strip centers if the new location cannibalizes value-oriented apparel traffic.
Contrarian view: a single asset sale should not be treated as proof that BDN's broader portfolio is marked at a comparable discount. Its asset-specific leasing, development and buyer-use issues may make it a poor comp for stabilized CBD office properties. The thesis is falsified if BDN's next debt maturities are addressed at materially wider spreads, if same-store NOI guidance deteriorates, or if further asset sales clear at similarly depressed implied cap rates over the next two quarters.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.32
Ticker Sentiment
Key Decisions for Investors
- Treat BDN as a liquidity-event watch, not a standalone long: revisit only if management commits the net proceeds to debt reduction and confirms no material 2027 refinancing gap. A sustained equity rerating requires stable same-store NOI and secured-debt spreads; absent those, the proceeds are a bridge rather than a catalyst.
- For real-estate shorts, prefer a basket expression via long BURL / short BDN over an outright BURL long for the next 3-6 months: BURL has limited asset-level earnings upside, while BDN remains exposed to office valuation and refinancing dispersion. Exit the pair if BDN demonstrates multiple non-core sales at stronger valuations or materially improves leverage guidance.
- Monitor BURL's subsequent lease, build-out and opening disclosures over 6-18 months. If the site opens without material cannibalization and supports sales productivity near mature-store averages, it would strengthen the case for long BURL versus ROST/TJX; until then, the acquisition is too small to alter estimates.
- Watch BDN's next quarterly guidance for use of proceeds, interest expense savings, occupancy and leasing spreads. A debt paydown large enough to lower annual cash interest meaningfully would support a tactical bounce; redeployment into speculative development would invalidate the liquidity-derisking interpretation.
More News
- Here’s the ‘core economic flaw’ in the AI bull case as stock and bond trades unravel, according to a top economist
- Biotech stocks are surging. How investors can play the new drug innovation boom
- Braskem creditors, shareholders near deal on $11bn debt restructuring
- Instacart reportedly discussed selling itself with DoorDash and Uber
- Nvidia's role as AI financier faces first big test as neoclouds take market hit
- Trump set to announce plan by Audi to build a U.S. factory in Georgia, source says