
Wing Lei Offers Affordable Michelin-Starred Cantonese Classics in Macau
Source: Bloomberg
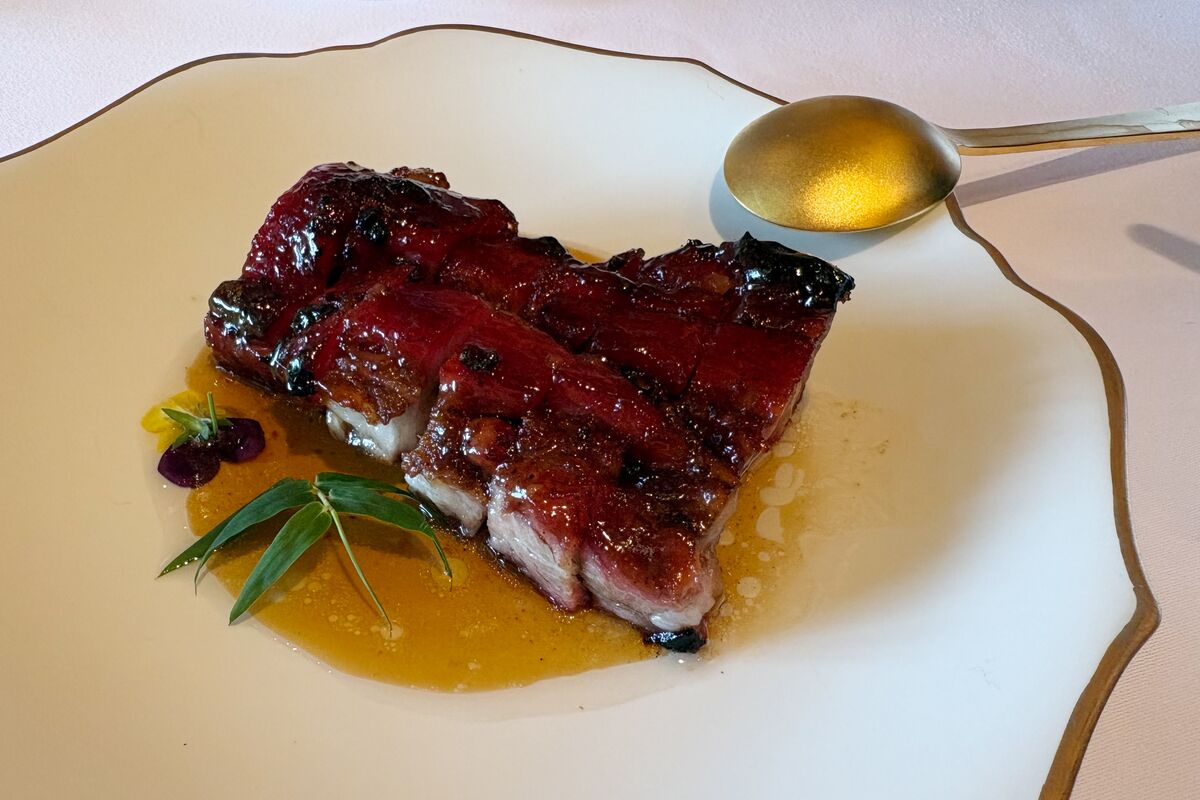
The article reviews Wing Lei, a Michelin-starred Cantonese restaurant in Macau, highlighting its comparatively affordable traditional fine-dining offering and elaborate dining-room design. The excerpt contains no financial results, corporate developments, or market-moving information.
Analysis
This is not a tradable company-specific catalyst. The relevant read-through is modestly constructive for Macau’s premium hospitality ecosystem: sustained demand for high-end dining supports non-gaming spend, which carries higher margin and helps operators diversify earnings away from volatile VIP gaming revenue.
The more investable transmission is through Macau gross-gaming-revenue and hotel occupancy data rather than restaurant reviews. MGM China (2282 HK), Sands China (1928 HK), Galaxy Entertainment (27 HK), and Wynn Macau (1128 HK) benefit only if premium food-and-beverage traffic signals broader overnight-stay and mass-premium visitation; a single venue’s positioning is not independently material to EBITDA.
Over the next 1-3 months, monitor Golden Week booking pace, Macau visitor arrivals, RevPAR, and mass-market GGR versus consensus. A stronger premium-leisure mix could modestly support upward revisions to property EBITDA margins over 6-18 months, while weaker Chinese consumer confidence or renewed travel-policy friction would make dining-led non-gaming growth irrelevant. No incremental trade is warranted from this item alone.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.10
Key Decisions for Investors
- No standalone position: treat this as a qualitative watch signal, not an earnings catalyst.
- Monitor October holiday hotel occupancy and mass-GGR data for confirmation; if both exceed consensus by 5%+ while Macau casino equities have not rerated, evaluate a basket long in 27 HK and 2282 HK.
- Prefer 27 HK over 1928 HK if premium-mass demand strengthens: Galaxy has greater exposure to higher-end customer mix, while Sands China is relatively more dependent on broad mass visitation and convention recovery.
- Falsification trigger for any Macau leisure long: two consecutive monthly misses in visitor arrivals or mass GGR, or renewed deterioration in China discretionary-spending indicators.
More News
- Thai capital Bangkok declared disaster zone amid flooding
- Bank of America says Nvidia and these other stocks are on sale
- PAM wins big in Morocco parliament elections but falls short of majority
- Four American tourists among 6 killed in suspected gas leak blast in Athens
- 27-year-old started a run club to meet new people—now his NYC side hustle brings in $640K a year
- Domino's Pizza Group: Still Attractive Amid Lingering Macro Uncertainty
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: AI-Powered Report Editing, Investor Relations, and Enhanced Search
- Automating Financial Model Updates: A Source-Controlled Workflow