
NORWEGIAN CRUISE LINE® UNVEILS SHOW-STOPPING ENTERTAINMENT LINEUP ABOARD NORWEGIAN AURA™ WITH "WHITNEY: A CELEBRATION OF WHITNEY HOUSTON" TAKING CENTER STAGE
Source: PR Newswire
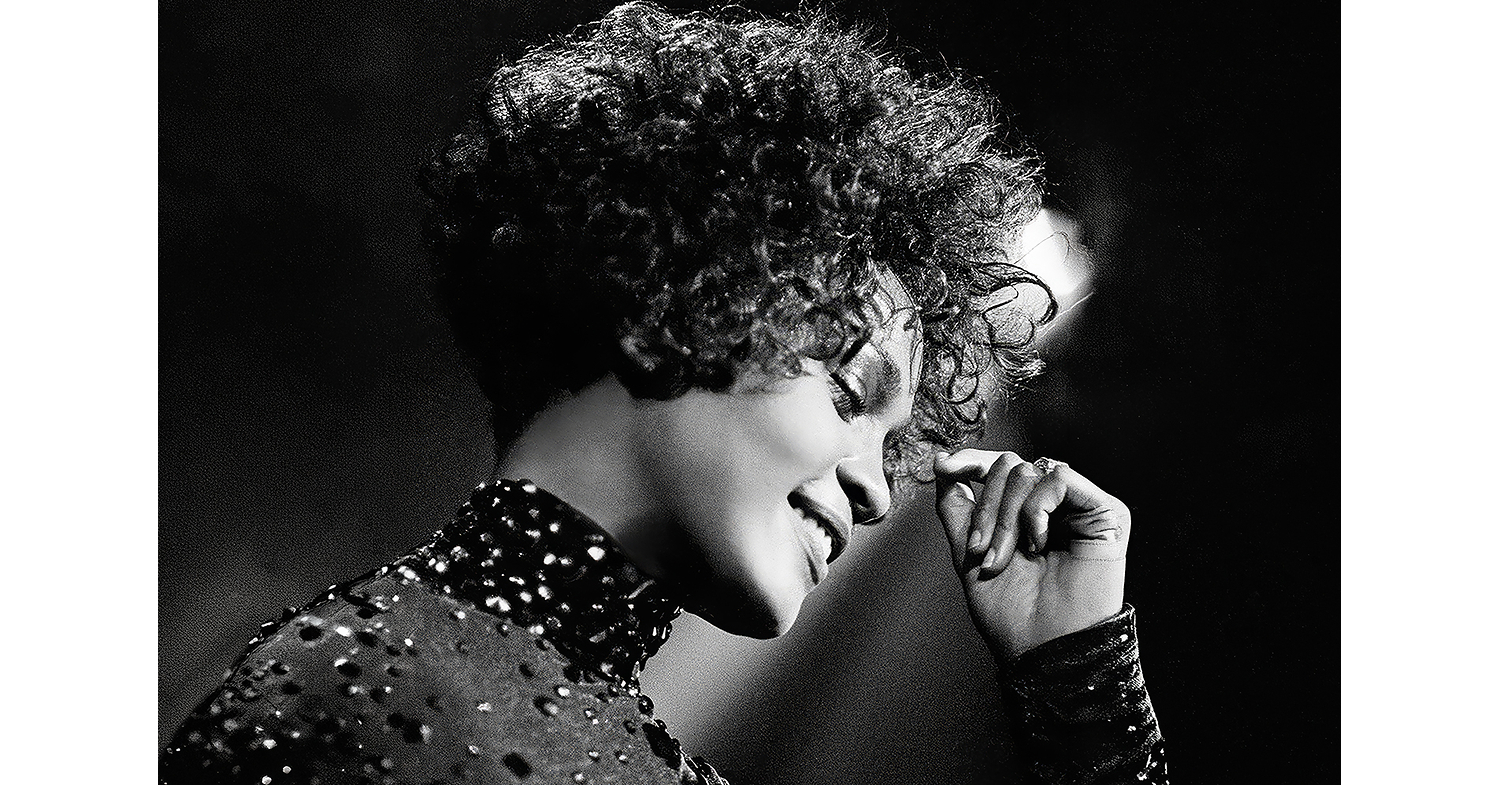
Norwegian Cruise Line unveiled the entertainment lineup for Norwegian Aura, scheduled to debut in May 2027, led by "Whitney: A Celebration of Whitney Houston," developed with Houston's estate and Primary Wave Music. The ship will also launch original productions including "ILLUMINOX" and The Vinyl Republic, while adding LunaTique: Pop Circus as a paid adults-only offering. Aura will begin with a May 21, 2027 Mediterranean sailing before starting seven-day Caribbean itineraries from Miami in June 2027, supporting NCL's premium onboard-experience strategy.
Analysis
This is not a material earnings event by itself; the investable signal is whether Aura’s differentiated onboard product supports a higher net-yield ramp than NCLH’s normal new-ship curve. Entertainment is largely a fixed-cost amenity, so incremental ticket pricing, occupancy, and onboard beverage/spend conversion would carry high contribution margins. The licensed-IP format also targets an older, higher-spending demographic that overlaps with premium cabin and loyalty demand, potentially improving mix rather than merely filling lower-priced berths.
The near-term market impact should be negligible because the revenue realization is more than eight months away and management has provided no booking, pricing, or cost disclosure. Over the next 1-3 months, the useful read-through is Aura’s booking pace versus comparable launch windows and whether Caribbean itineraries command a premium to existing Miami capacity. A strong premium would support 2027 net-yield estimates; weak pricing despite the differentiated product would instead indicate that industry capacity, not product differentiation, is setting the clearing price.
The second-order risk is that NCLH has more earnings sensitivity to Caribbean yield than larger peers because new capacity and private-destination spending require sustained occupancy. Entertainment-heavy offerings can raise guest spend, but royalty, production, and labor expenses may offset the benefit if the shows do not improve retention or pricing. CCL and RCL may face little direct competitive impact: their scale, balance sheets, and private-island ecosystems remain the more important determinants of relative valuation.
Contrarian view: investors may over-credit branded entertainment as a demand catalyst when cruise purchase decisions remain dominated by itinerary, ship hardware, airfare, and promotional intensity. Treat this as a potential confirmation of product execution—not a reason to revise estimates—unless booking data show a measurable price/occupancy premium and management quantifies onboard-spend uplift.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Ticker Sentiment
Key Decisions for Investors
- No standalone trade on the announcement; maintain NCLH as a monitoring name until Aura booking curves are disclosed. Upgrade only if management indicates a sustained pricing premium versus comparable seven-night Miami itineraries during the next two earnings calls.
- For a 6-18 month relative expression, prefer long RCL / short NCLH if cruise demand remains healthy but Caribbean promotional activity rises: RCL’s balance-sheet flexibility and higher-end customer mix should better absorb yield normalization. Reassess if NCLH delivers net-yield guidance materially above peers or demonstrates faster deleveraging.
- Set an alert around NCLH’s next guidance cycle for 2027 capacity growth, Caribbean net-yield commentary, and booking-window trends. A guidance raise tied to pricing rather than occupancy would validate margin upside; discount-driven volume growth would falsify the differentiated-product thesis.
- Avoid pre-launch long-dated NCLH calls solely on Aura. The missing inputs—ticket price premium, occupancy, royalty/production costs, and incremental onboard spend—make risk/reward unattractive until the company provides measurable booking evidence.
More News
- Norwegian Cruise Line Holdings secures $5 billion credit facilities for new ships
- Freedom Broker upgrades Norwegian Cruise stock rating on strong Q3 results
- What Norwegian Cruise Line (NCLH) Said on Its Q3 Earnings Call
- Nasdaq Nears Correction as Amazon, Alphabet, Intel Disappoint Wall Street
- Reddit stock plunges 30% after weak outlook, heads for worst day ever
- Chevron speeds ahead in Venezuela while Exxon urges caution with a ‘little pinch of salt’