
Restaurant Brands International gets lift from Burger King turnaround
Source: proactiveinvestors.com
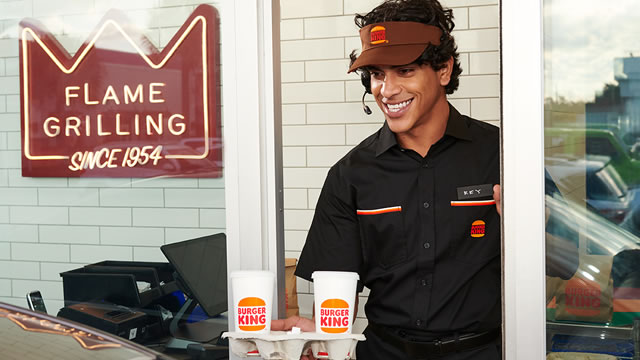
Jefferies raised its forecast for Burger King's US third-quarter same-store sales growth to 6.5% from 5%, citing steady customer footfall and a turnaround gaining traction. The chain reported 8.5% comparable sales growth in Q2, and Jefferies said momentum could extend into 2027.
Analysis
The estimate revision is a near-term sentiment catalyst, not yet proof of a durable earnings inflection. The key market question is whether Burger King’s traffic gains reflect repeatable demand and better restaurant execution, or discounting that lifts visits while weakening franchisee returns. The latter could cap reinvestment and eventually reverse the sales momentum. For Restaurant Brands International, verify the contribution of US Burger King to consolidated results alongside performance at its other brands; a strong single-brand comp should not be extrapolated to the whole company.
Over the next 1–3 months, the next results and any update to comparable-sales guidance should distinguish traffic from average check and show whether momentum is broadening. Over 6–18 months, sustained traffic could improve franchisee confidence and support unit investment, but that depends on restaurant-level economics, not sales growth alone. McDonald’s and Wendy’s are relevant competitive checks: if Burger King gains share through aggressive offers, competitors may respond, converting a demand tailwind into industry-wide margin pressure. The estimate is broker-derived and should be treated as a forecast, not independently verified operating data. Without valuation, segment contribution, and traffic/mix details, the signal is positive but insufficient to justify chasing QSR.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- No immediate directional trade on the estimate revision alone. Keep QSR on a catalyst watchlist and reassess after the next report provides US Burger King traffic, average-check, and comparable-sales detail.
- Consider a modest long QSR only if subsequent disclosures confirm traffic-led growth and no deterioration in franchisee economics; size against the risk that discounting is buying sales at the expense of returns. Do not infer consolidated acceleration from Burger King US alone.
- Monitor McDonald’s and Wendy’s promotional activity as an early warning of a competitive response. A shift toward heavier discounting, or Burger King sales growth driven mainly by average check rather than visits, would weaken the thesis.
- Falsifiers: Burger King comparable-sales guidance rolls over, traffic turns negative, or management commentary indicates sales gains are not translating into sustainable restaurant-level economics. Reconsider the bullish view if any of these emerge.
More News
- Anthropic's third-quarter revenue is said to hit $16.8 billion ahead of IPO
- SK Hynix seeks U.S. chip equipment exports to China tied to new factory
- Dell stock plunges 11%, leading data center sell-off on concerns about 'enterprise AI timing'
- Why is Rocket Lab stock tumbling today?
- AI infrastructure stocks tumble. Here's a few reasons for the sell-off
- Fed may now have to hike twice or increase by a half point in December, traders bet
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Reading Conviction in the Tape: What Level 3 Order Book Data Really Tells Discretionary PMs
- AI Tools for CFA Charterholders: An Evidence Standard