
Lippincott to acquire brand and innovation studio Athletics
Source: PR Newswire
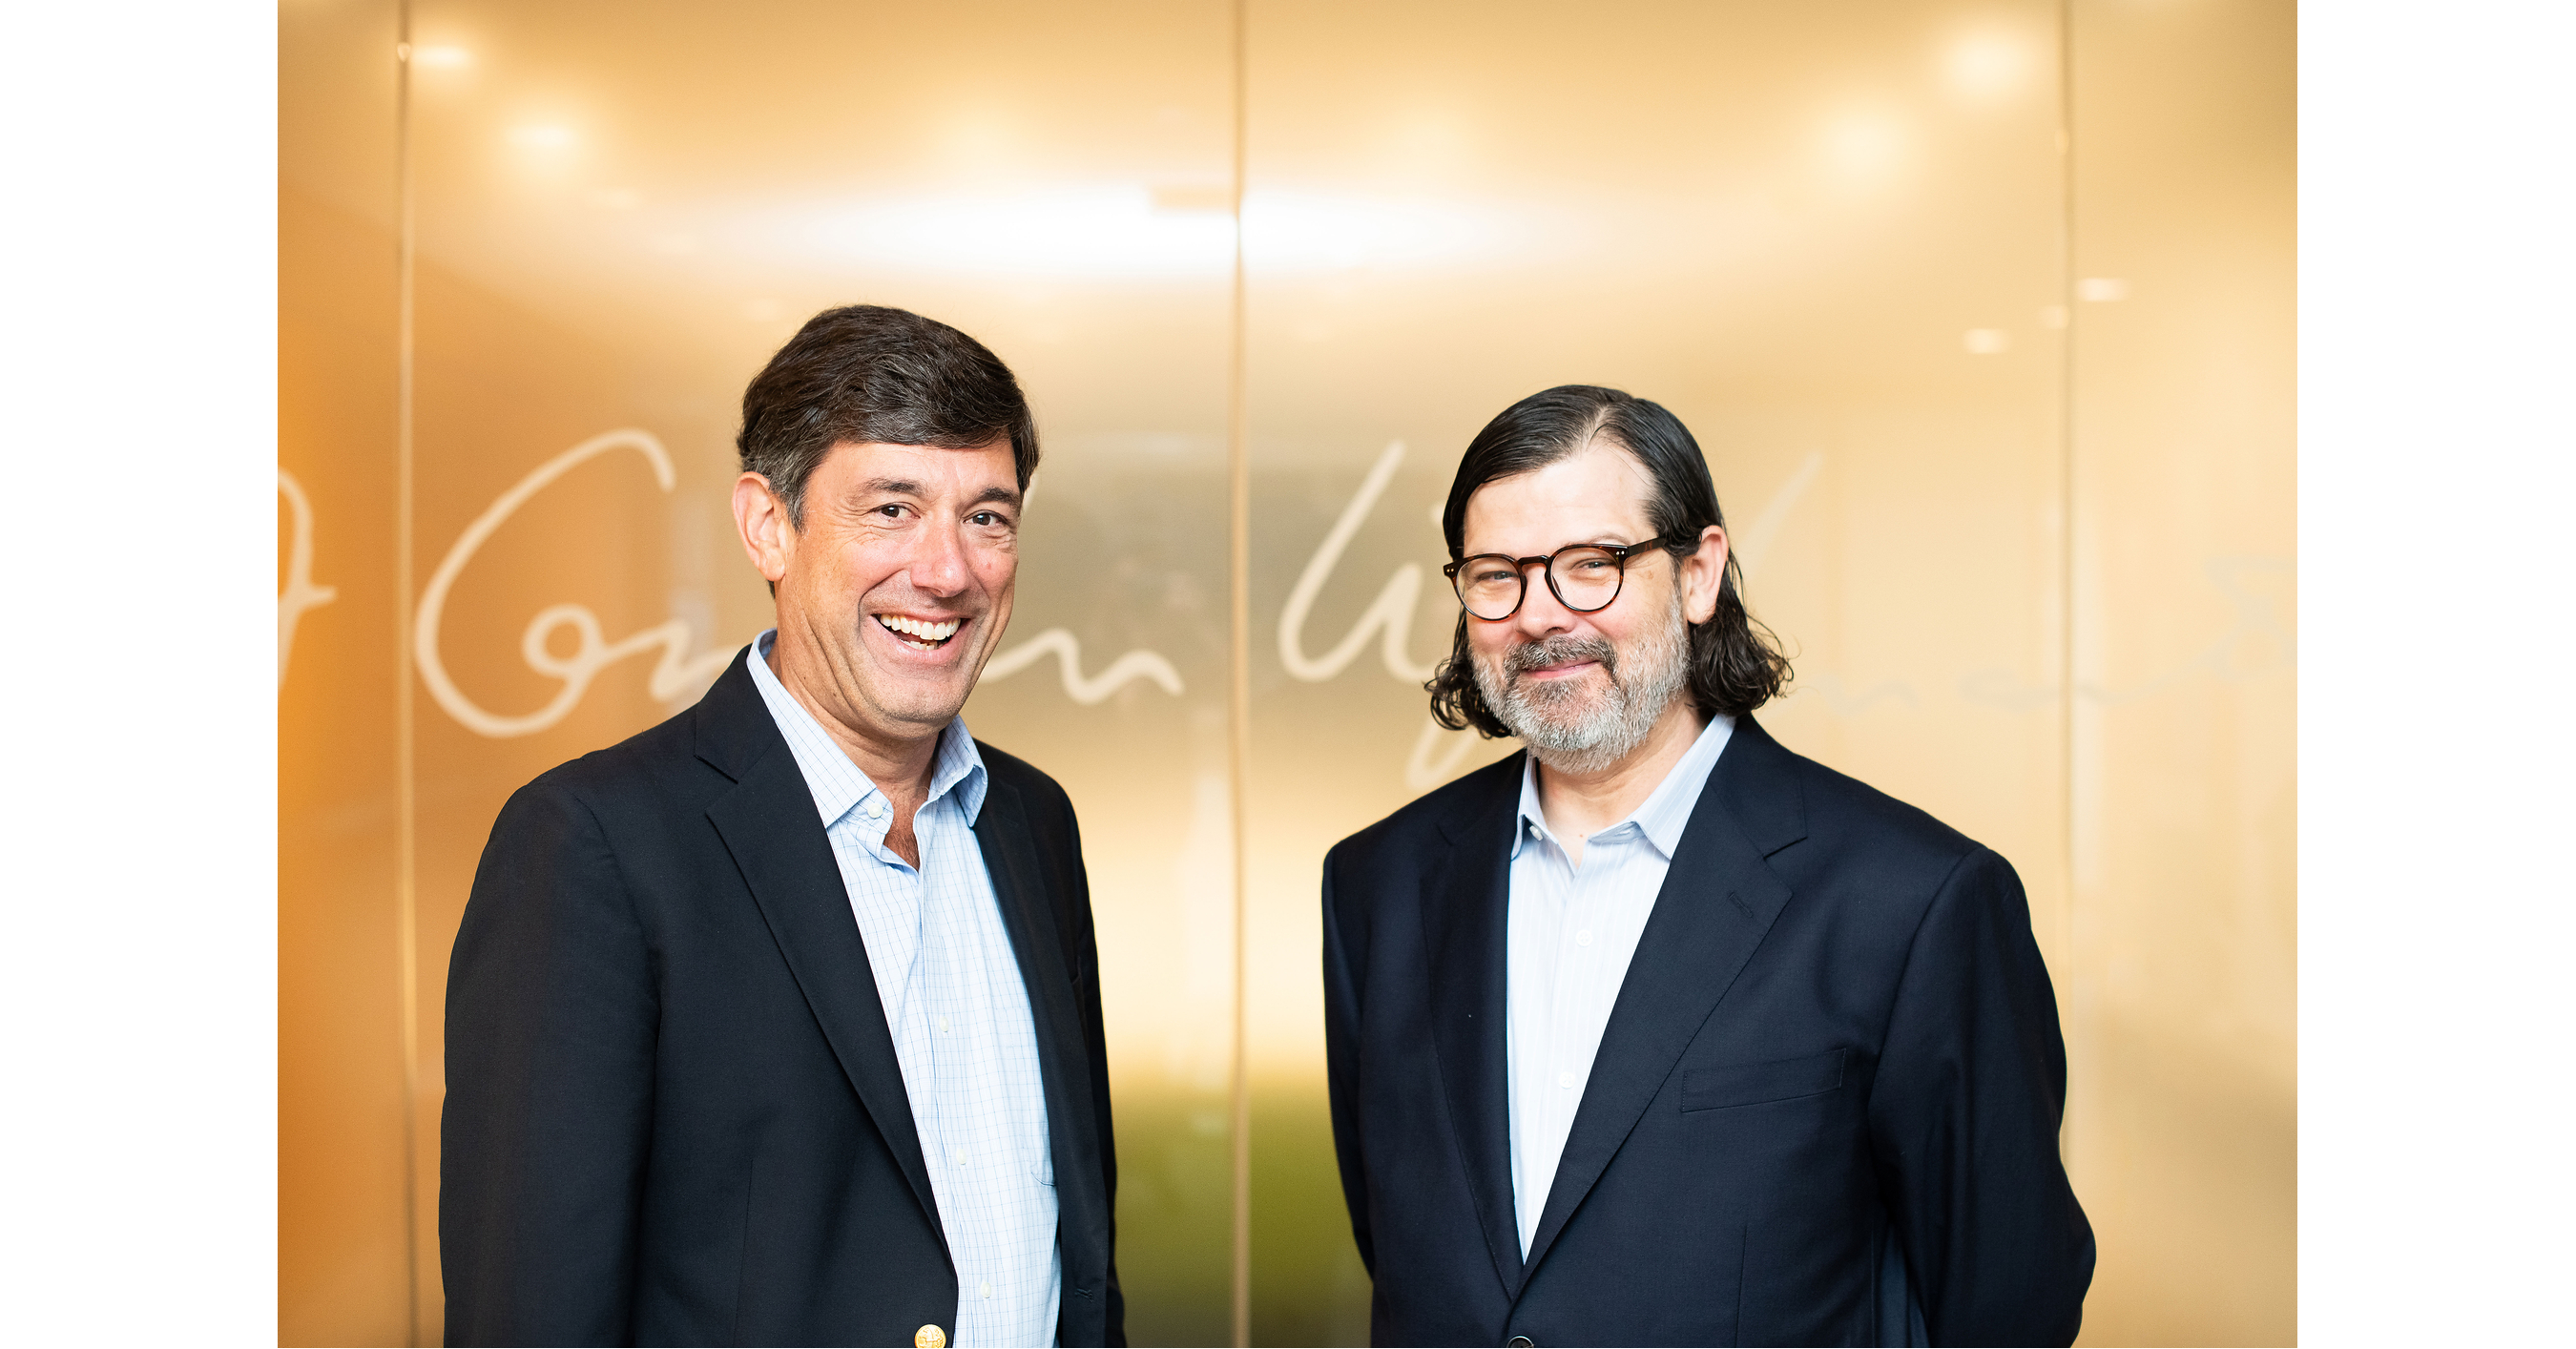
Lippincott agreed to acquire New York-based Athletics, a brand and innovation studio with proprietary AI software Sesame, to expand its design, digital and creative-technology capabilities. The transaction is expected to close November 2, 2026; approximately 25 Athletics employees will join Lippincott, and the studio will retain its Brooklyn offices. The companies say the combination will help them take on larger client challenges and move from brand strategy to activation more quickly.
Analysis
The investable signal is strategic positioning, not near-term earnings: Lippincott is adding execution capacity to reduce the handoff between brand strategy and digital/physical delivery. If that improves project capture or expands wallet share, the benefit accrues to the consultancy parent, Marsh McLennan, but a 25-person team is unlikely to move consolidated results absent evidence of broader acquisitions or material client wins. The countervailing risk is integration: a small creative studio’s speed and talent proposition can be diluted by a larger consultancy’s processes, while proprietary AI tools may be less defensible than the release implies. Named client work for Salesforce, IBM, Google and Amazon is not evidence of incremental contracts or endorsement, so no read-through to CRM, IBM, GOOG or AMZN fundamentals is warranted.
Over the next days, the announcement is unlikely to support a standalone listed-equity catalyst. Over 1–3 months, verify closing, leadership/talent retention and whether Lippincott announces cross-selling wins or scaled AI deployments. Over 6–18 months, the strategic test is whether integrated work lifts client retention and project economics versus competitors such as Accenture, Deloitte Digital and large advertising groups. A contrarian risk is that clients increasingly buy AI-enabled execution directly from software vendors or specialist studios, weakening the premium for bundled consulting. No direct trade is justified on this announcement alone; falsification of the integration thesis would be talent departures or no evidence of larger mandates, while demonstrable client wins and repeatable tool adoption would strengthen it.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- No event-driven position: the acquisition is small in disclosed headcount, private, and lacks transaction value or quantified revenue contribution.
- Treat Marsh McLennan as a watch item rather than a recommendation; reassess only if subsequent disclosures show meaningful consultancy growth, cross-selling, or acquisition spending.
- Do not trade CRM, IBM, GOOG or AMZN on the cited client relationships; verify any new contract or revenue disclosure before assigning company-level impact.
- Track closing and post-close retention through the next 1–3 months, then look for repeatable AI-tool adoption and larger integrated mandates over 6–18 months; talent loss or absent commercial traction would undermine the thesis.
More News
- US stock market hits all-time high as investors bet big on AI
- What Marvell's rosy long-term guidance means for our AI chip stocks
- U.S. stock futures steady after tech rally lifts S&P 500, Nasdaq to records
- Meta Muse gives AMD a boost as AI momentum shifts to personal agents
- Why is Broadcom stock rallying today?
- Google teams with nuclear power giant to give reactors a tune-up
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- What Is an AI Research Agent?
- Bitcoin's 52% Crash Proves It's a Tech Stock: Here's What That Means for Portfolio Construction