
Angel Yeast Marks 40th Anniversary, Setting Its Sights on Becoming a Global Biotech Powerhouse
Source: PR Newswire
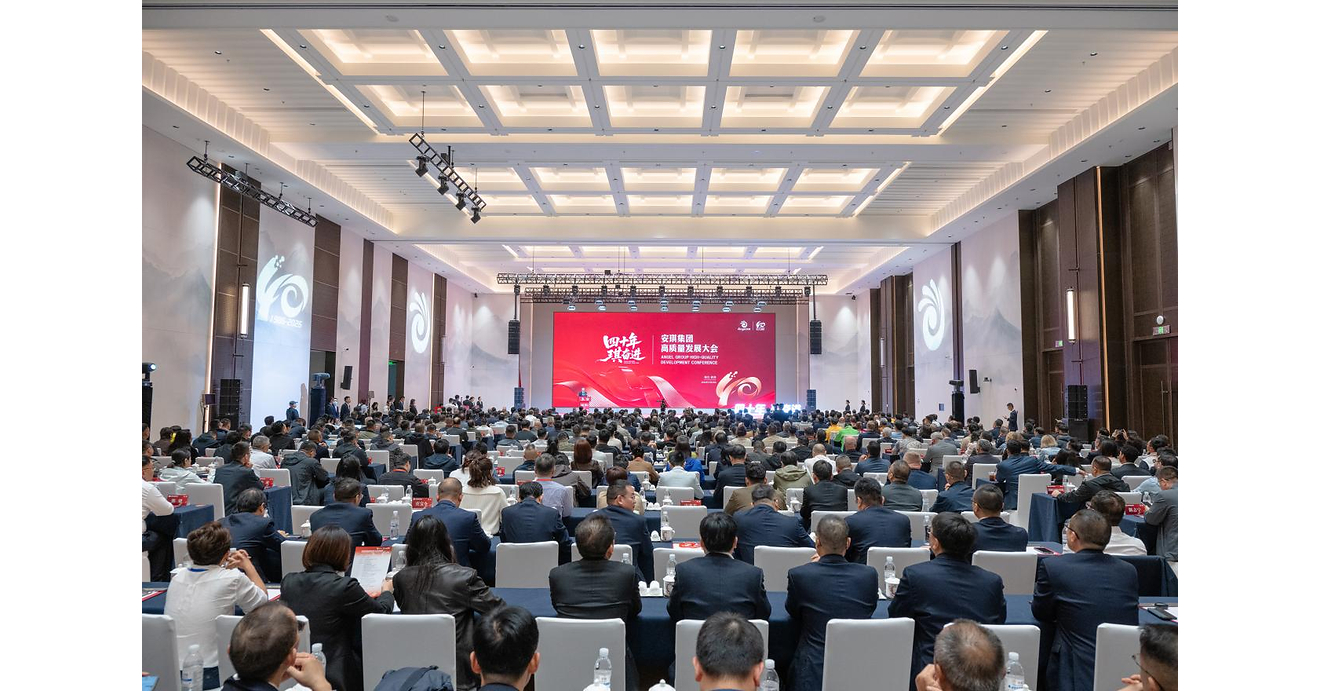
Angel Yeast said it serves more than 30,000 customers in 170+ countries and regions, with over 20% market share, and spends more than $149.8 million annually on R&D. The company reported 534 authorized invention patents, five National Green Factories and a zero-carbon factory; its new Indonesia plant is expected to begin production in Q1 2027. Chairman Xiong Tao said the company plans to expand synthetic biology applications and build a biomanufacturing industrial cluster.
Analysis
Angel Yeast: capacity is more investable than the synthetic-biology story
The event itself is not an earnings catalyst: it adds no disclosed orders, capacity economics, or financial targets. The investable question is whether overseas production improves delivered cost and customer access enough to offset ramp-up costs and potential regional pricing pressure. Indonesia’s planned start in Q1 is the nearest operational checkpoint; commissioning delays, low utilization, or weaker-than-expected customer qualification would turn geographic diversification into near-term margin drag. Egypt and Indonesia also increase exposure to local input availability, utilities, FX, and logistics, so production footprint alone does not establish a cost advantage.
The longer-dated upside is strategic optionality: strain-engineering and fermentation capabilities could support higher-value ingredients beyond conventional yeast. But R&D scale, patents, and conference participation are inputs—not evidence of commercial returns. Codex involvement may help standardize products and lower adoption friction over time, while also making standards-setting influence a slow-moving moat rather than a near-term catalyst.
Contrarian read: investors may over-credit the synthetic-biology narrative and underweight execution and utilization. Conversely, if new capacity is absorbed without discounting and higher-value products contribute materially, the market may be valuing Angel Yeast mainly as a mature food-ingredient producer. Verify plant ramp, utilization, volume/price mix, capex, and segment-level margins before underwriting either case.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Key Decisions for Investors
- No event-driven position: treat the symposium and anniversary claims as low-signal until reported financials or customer wins validate commercial impact.
- Place Angel Yeast on an operational watchlist through Q1 and the subsequent ramp. Positive evidence: on-time commissioning, rising utilization, and stable or improving price/mix; falsification: delay, discounting, or weaker margins as capacity comes online.
- Do not capitalize synthetic-biology optionality as near-term earnings. Reassess only when the company discloses product-level revenue, customer adoption, or returns on R&D; absent those data, avoid paying a thematic premium.
More News
- AI Doubts Spread Cracks in Equities, Credit Markets: Evening Briefing Americas
- With earnings in rearview mirror, SpaceX-Tesla merger chatter takes center stage
- Looters hit 3,000 French businesses. Within hours, the haul was trending on Vinted under the riot’s date
- Apple’s $2,000 iPhone Duo Debuts With Limited Supply
- Are global oil reserves sufficient to withstand renewed US-Iran war?
- Boeing 777 freighter output halted for two months over supplier row