
Alurion Launches Amargosa PFS Program to Advance a Scalable Atlantic-Basin Bauxite Project
Source: globenewswire.com
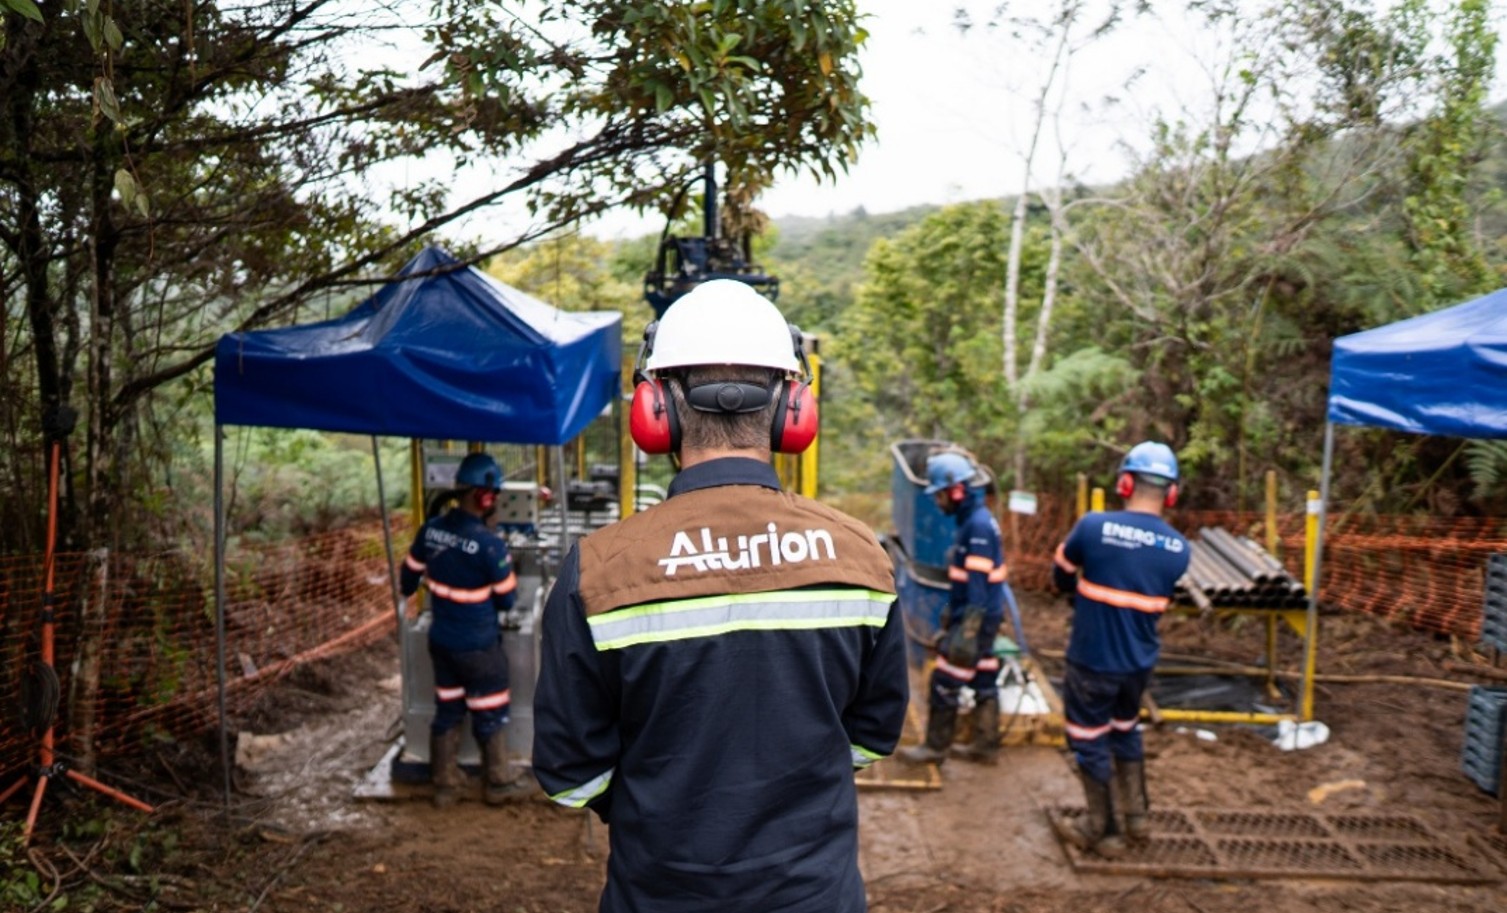
Alurion Resources has started infill drilling and bulk-sample trenching at its Amargosa bauxite-gallium project to support a direct-ship-bauxite PFS, including 203 auger holes (2,436m) plus 20 diamond twin holes (800m) and up to 16 bulk-sample trenches. The program is intended to upgrade Measured and Indicated resources feeding mine planning. The Central District is set as the development anchor for a staged pathway from resource scale to field-based development.
Analysis
This is not a near-term revenue story; it is a de-risking step that mainly changes the probability distribution of a future financing event. For a junior resource name, infill drilling and trenching matter less for commodity exposure than for valuation: each increment in resource confidence can reduce the discount rate investors apply, but only if the project ultimately clears metallurgy, permitting, and capex hurdles. The market should treat any rally as an option on a future PFS rather than as evidence of bankable economics.
The second-order winner, if the gallium credit is real and recoverable at scale, is not the miner itself but downstream buyers looking for non-China supply optionality in semis, optics, and defense. That said, gallium byproduct economics are fragile: if recoveries are low or processing complexity is high, the gallium angle becomes promotional rather than economic, and the project reverts to a generic bauxite story competing against lower-cost producers. In that case, the main competitive effect is on speculative capital flows, not on global supply curves.
The key risk over the next 1-3 months is financing dilution: early-stage drilling progress often precedes a capital raise, and any placement at a discount can erase paper gains quickly. Over 6-18 months, the falsifier is simple: if the PFS does not show a credible path to low-cost direct-ship bauxite with meaningful byproduct value, the market will likely re-rate the name back to exploration optionality. Watch for metallurgy, strip ratio, and payability assumptions—those will matter far more than hole count.
Contrarian view: the market may be underestimating how much of the current enthusiasm is driven by the word "gallium" rather than project quality. If the resource upgrade is modest, the move should be faded after the initial drill-phase excitement. The right trade is probably to wait for the PFS or financing terms, because that is where the real economic signal will arrive.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.12
Key Decisions for Investors
- No immediate catalyst trade: avoid initiating a position until the PFS addresses recoveries, capex, and operating cost assumptions; for a microcap resource name, drilling news alone is usually not a durable re-rating event.
- If ALU remains liquid enough for a tactical expression, consider a small speculative long only after the next resource update confirms material upgrade in Measured/Indicated ounces/tonnes and no near-term placement overhang; set a hard stop at the first sign of discounted equity issuance.
- Watch for a financing event over the next 1-3 months; if management raises capital before PFS economics are disclosed, treat that as a short-term fade signal rather than confirmation of project quality.
- For investors seeking the strategic gallium theme, prefer downstream supply-chain beneficiaries with real earnings sensitivity to non-China sourcing over the miner itself; the mining optionality is higher beta and much lower visibility.
- Falsifier to the bull case: if the PFS shows weak payability, high strip ratio, or metallurgical complexity that pushes the project into high-capex territory, exit the thesis and expect the stock to revert toward exploration valuation.
More News
- US forces disable ship ‘attempting to run’ Iran blockade in Gulf of Oman
- Musk says Terrafab chip factory could outperform rivals despite challenges
- Stocks saw new highs and big declines: How the volatile AI trade moved last week's market
- Will Warner Bros. kill Skydance — or will David Ellison kill Warner Bros?
- How Supreme Court justices are leaning in major 401(k) case over private funds and underperformance
- Ship captains and crews transiting the Strait of Hormuz make so much danger pay that they’re ‘almost being viewed as mercenaries’