
Introducing the MoneyGram Card: Giving Customers More Freedom to Use Their Money, Wherever Life Takes Them
Source: PR Newswire
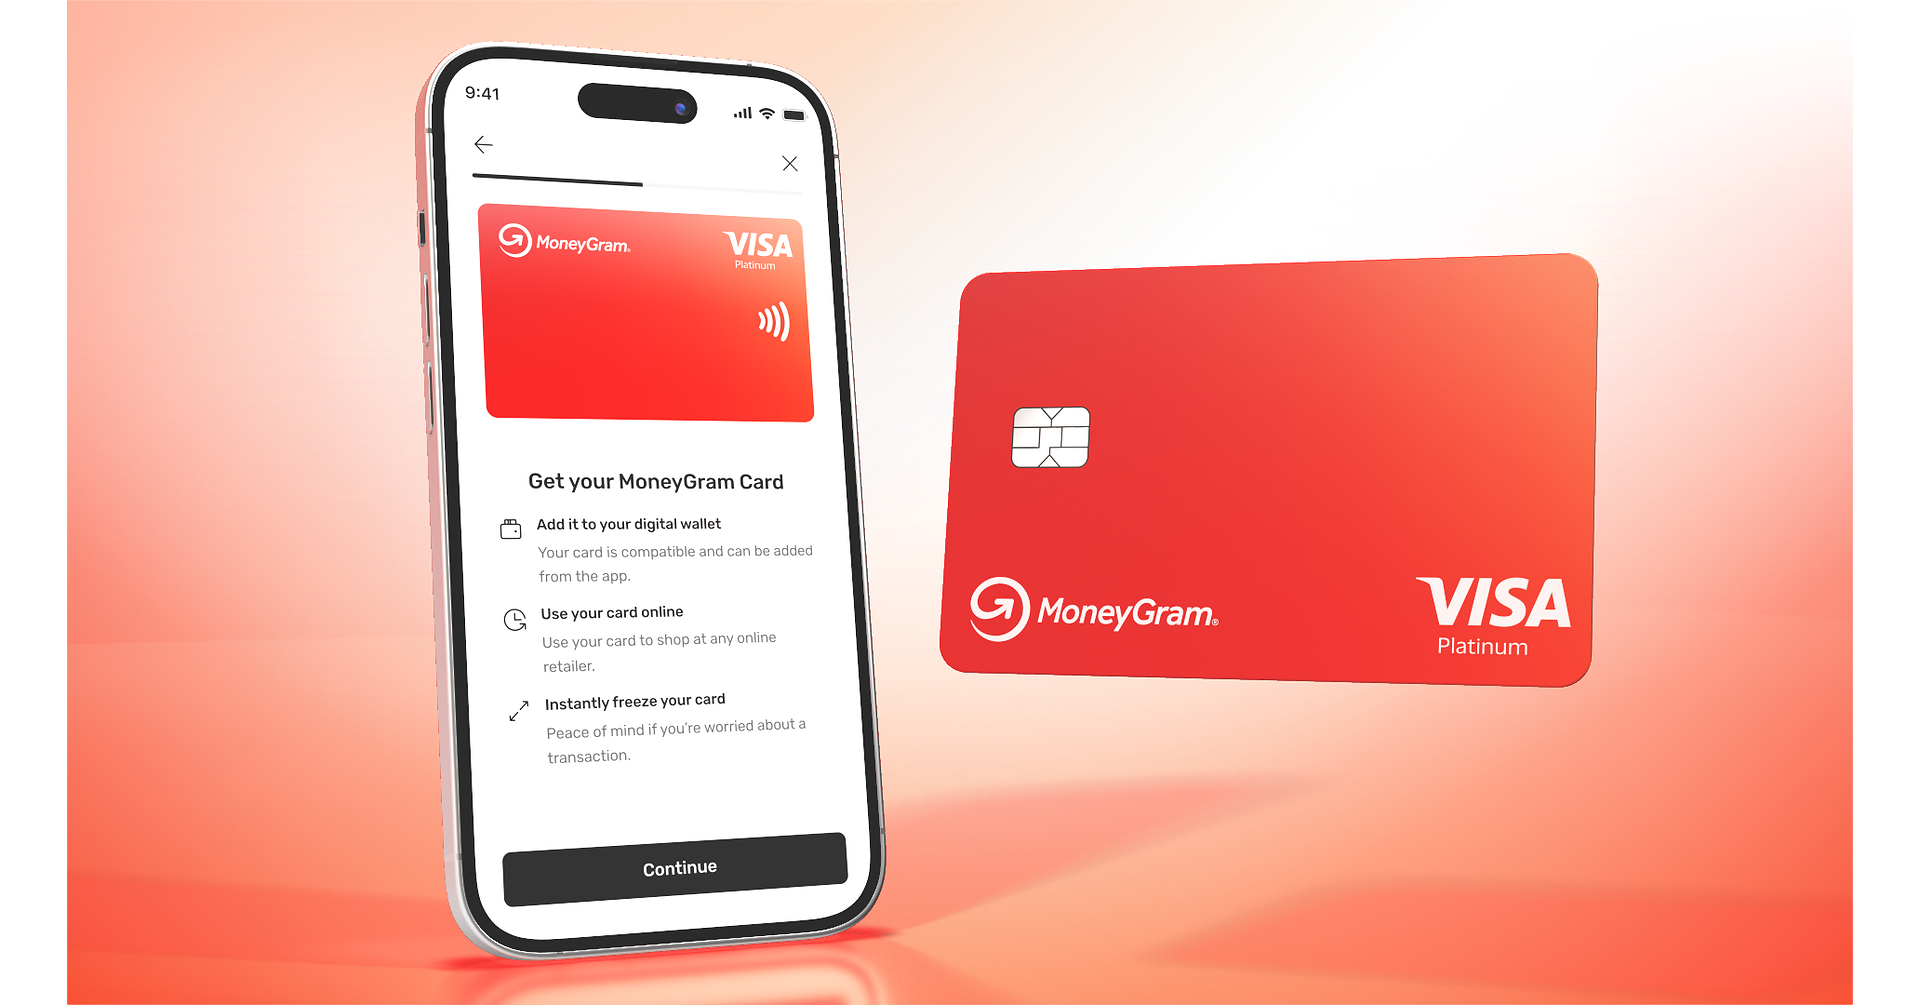
MoneyGram launched a stablecoin-backed MoneyGram Card in Colombia, enabling eligible customers to hold stable-dollar balances, spend anywhere Visa is accepted and access local-currency cash through its network. The product integrates Rain's stablecoin payment infrastructure, Crossmint wallets and the Stellar network, leveraging MoneyGram's 60 million active customers, presence in more than 200 countries and nearly 500,000 retail locations. Expansion to additional markets is planned in coming months, with a physical card and ATM withdrawal capability targeted for late 2026.
Analysis
The investable read-through is concentrated in Visa (V), but the near-term revenue effect is immaterial: card-network economics accrue only when stored-value balances convert into purchase volume, and Colombia alone cannot move consensus estimates. The strategic value is validation that stablecoin balances can be monetized through existing card acceptance rather than requiring a new merchant network. If conversion costs and FX spreads are meaningfully lower than traditional remittance payout, this could pressure Western Union (WU) and Remitly (RELY) in high-inflation, dollar-demand corridors over 6-18 months, particularly where recipients increasingly retain rather than immediately cash out transferred funds.
Apple (AAPL) and Alphabet (GOOG) gain negligible direct economics from wallet provisioning, but their payment wallets become more important distribution gates if stablecoin-linked cards proliferate. The key competitive question is whether MoneyGram can use its cash-out network to solve the last-mile liquidity problem more effectively than crypto-native platforms; if so, it could reduce the advantage held by Coinbase (COIN) and fintech wallets in emerging markets without necessarily taking meaningful Visa share. The press release provides no disclosed issuer, interchange split, stablecoin reserve economics, customer incentives, or transaction-volume targets, so adoption claims should not be capitalized.
Near-term catalyst risk is regulatory and operational rather than demand-driven: a Colombian supervisory restriction, KYC failure, or wallet/settlement outage would limit expansion before physical-card rollout. Conversely, evidence of repeat spend rather than one-time remittance conversion—especially disclosure of active cardholders, monthly purchase volume, and cash-out frequency over the next 1-3 months—would validate a broader remittance-to-wallet model. The contrarian view is that cash access may cannibalize the higher-margin payout transaction without generating sufficient card spend, leaving the product strategically defensive rather than economically additive.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Ticker Sentiment
Key Decisions for Investors
- No standalone directional trade in V on this launch; maintain V as the preferred large-cap payments exposure, but require evidence of multi-market rollout and measurable stablecoin-linked purchase volume before attributing any earnings upside. The thesis is falsified if regulatory constraints prevent expansion beyond Colombia or if usage remains primarily cash withdrawal.
- Place WU and RELY on a 6-18 month competitive watchlist rather than shorting on announcement: monitor take rates, digital customer acquisition cost, and Latin America corridor volumes. A sustained deterioration in corridor revenue growth or increased promotional spending after rollout would support a relative short WU or RELY versus long V.
- For crypto exposure, treat COIN as a potential second-order loser only if stablecoin balances demonstrably migrate into remittance-led consumer wallets; do not initiate a short without data on wallet balances and repeat spending. COIN's broader trading, custody, and USDC economics make this single corridor launch insufficient.
- Monitor V commentary on stablecoin settlement, cross-border payment volume, and credentialed wallet transactions through the next two earnings cycles. A disclosed expansion of stablecoin settlement into high-remittance markets would be a more actionable catalyst than card issuance itself.
More News
- Goldman says these top tech stocks have plenty of upside ahead of earnings
- Will AI expose the rickety infrastructure of the internet?
- The UK is investing $134 million into an AI Biosecurity Lab
- In Brazil’s elections, big techs’ transparency and cooperation policies translate as governance washing, according to this expert
- The AI graveyard: a running list of projects and startups that didn’t make it
- Block’s new voice model sounds eerily human