
There's So Much AI Debt That The Credit Market is Struggling to Cope With It
Source: Bloomberg
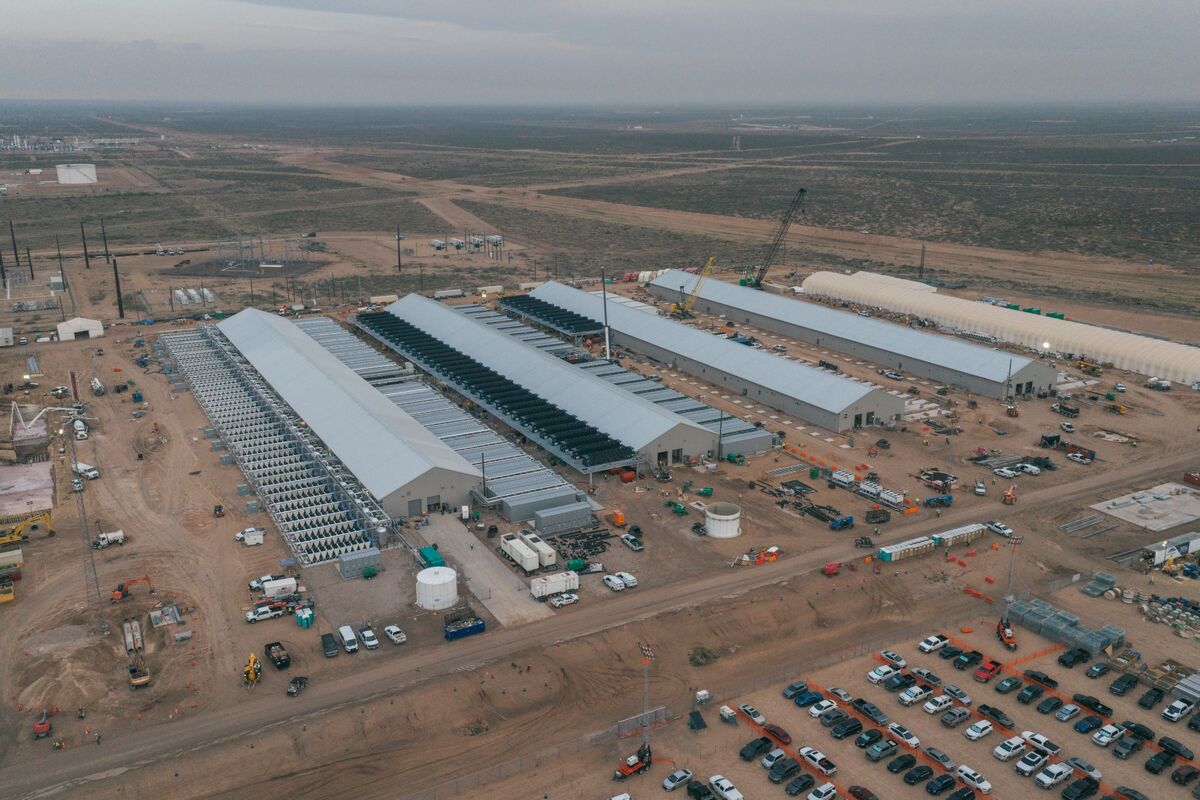
Rising demand for AI-linked financing is increasing insurers’, pension funds’ and direct lenders’ exposure to data center debt. Public credit markets are showing early signs of strain in absorbing the issuance, raising concern that financing risk is spreading through the financial system.
Analysis
The key risk is not “AI debt” in aggregate but a maturity and underwriting mismatch: long-lived data-center assets may be financed against fast-changing chip economics, concentrated tenant demand, and power constraints. If public markets become less receptive, refinancing risk can migrate to private lenders and long-duration holders before it appears in reported defaults. That creates potential mark-to-model lag and correlated selling across private-credit portfolios, insurers, and pension allocations—not necessarily immediate losses on every loan.
Near term (days), watch for wider spreads or weaker terms on new data-center financings; a broad AI-equity short would be an imprecise expression. Over 1–3 months, issuance pricing, covenant protections, leverage, tenant concentration, power availability, and committed-versus-speculative capacity will show whether lenders are being paid for risk. Over 6–18 months, slower AI monetization or tighter refinancing could expose projects dependent on a small number of customers or continuing capital access.
Contrarian: financing demand also reflects real infrastructure buildout, and contracted cash flows or strong collateral could support senior loans. A generalized credit panic may therefore overprice risk in diversified, well-secured exposures while missing weaker structures. The article provides no issuance, spread, or loss data; confirm these before sizing a directional position. Thesis weakens if deal terms remain disciplined, project revenues are contracted and diversified, and refinancing markets stay open.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.25
Key Decisions for Investors
- Avoid a blanket short of AI equities on this signal. As a near-term hedge, consider reducing lower-quality credit exposure or using broad high-yield protection only if spreads begin widening alongside deteriorating new-issue terms; define risk against spread stabilization and avoid treating this article alone as a trigger.
- For a relative-value watchlist, favor diversified, investment-grade infrastructure financing over speculative, single-tenant data-center exposure, conditional on verifying tenant credit, power contracts, loan seniority, and refinancing schedules. Do not assume all data-center debt has comparable risk.
- Track monthly issuance volume, pricing concessions, covenant quality, lender concentration, and insurer/pension exposure. A sustained deterioration in these measures would support increasing credit hedges; stable terms and contracted utilization would argue against escalation.
- Falsifiers: continued market access without weaker covenants, diversified contracted demand, and stable credit spreads. Escalation signals: failed or delayed financings, material spread repricing, rising refinancing needs, or evidence that projected AI demand is not converting into customer commitments.
More News
- What investors need to know about Alphabet's stock-busting earnings report
- Our next steps for Alphabet stock after earnings disappoint at nearly every turn
- Budget 2026 speech
- Federal Reserve issues FOMC statement
- Microsoft's Big Bets on AI Start to Pay Off
- Asian shares fall as Alphabet earnings miss drags Wall St futures lower