
SkinMedica® Adds Barrier Calming Cream to its Collection of Regenerative Skincare Offerings
Source: PR Newswire
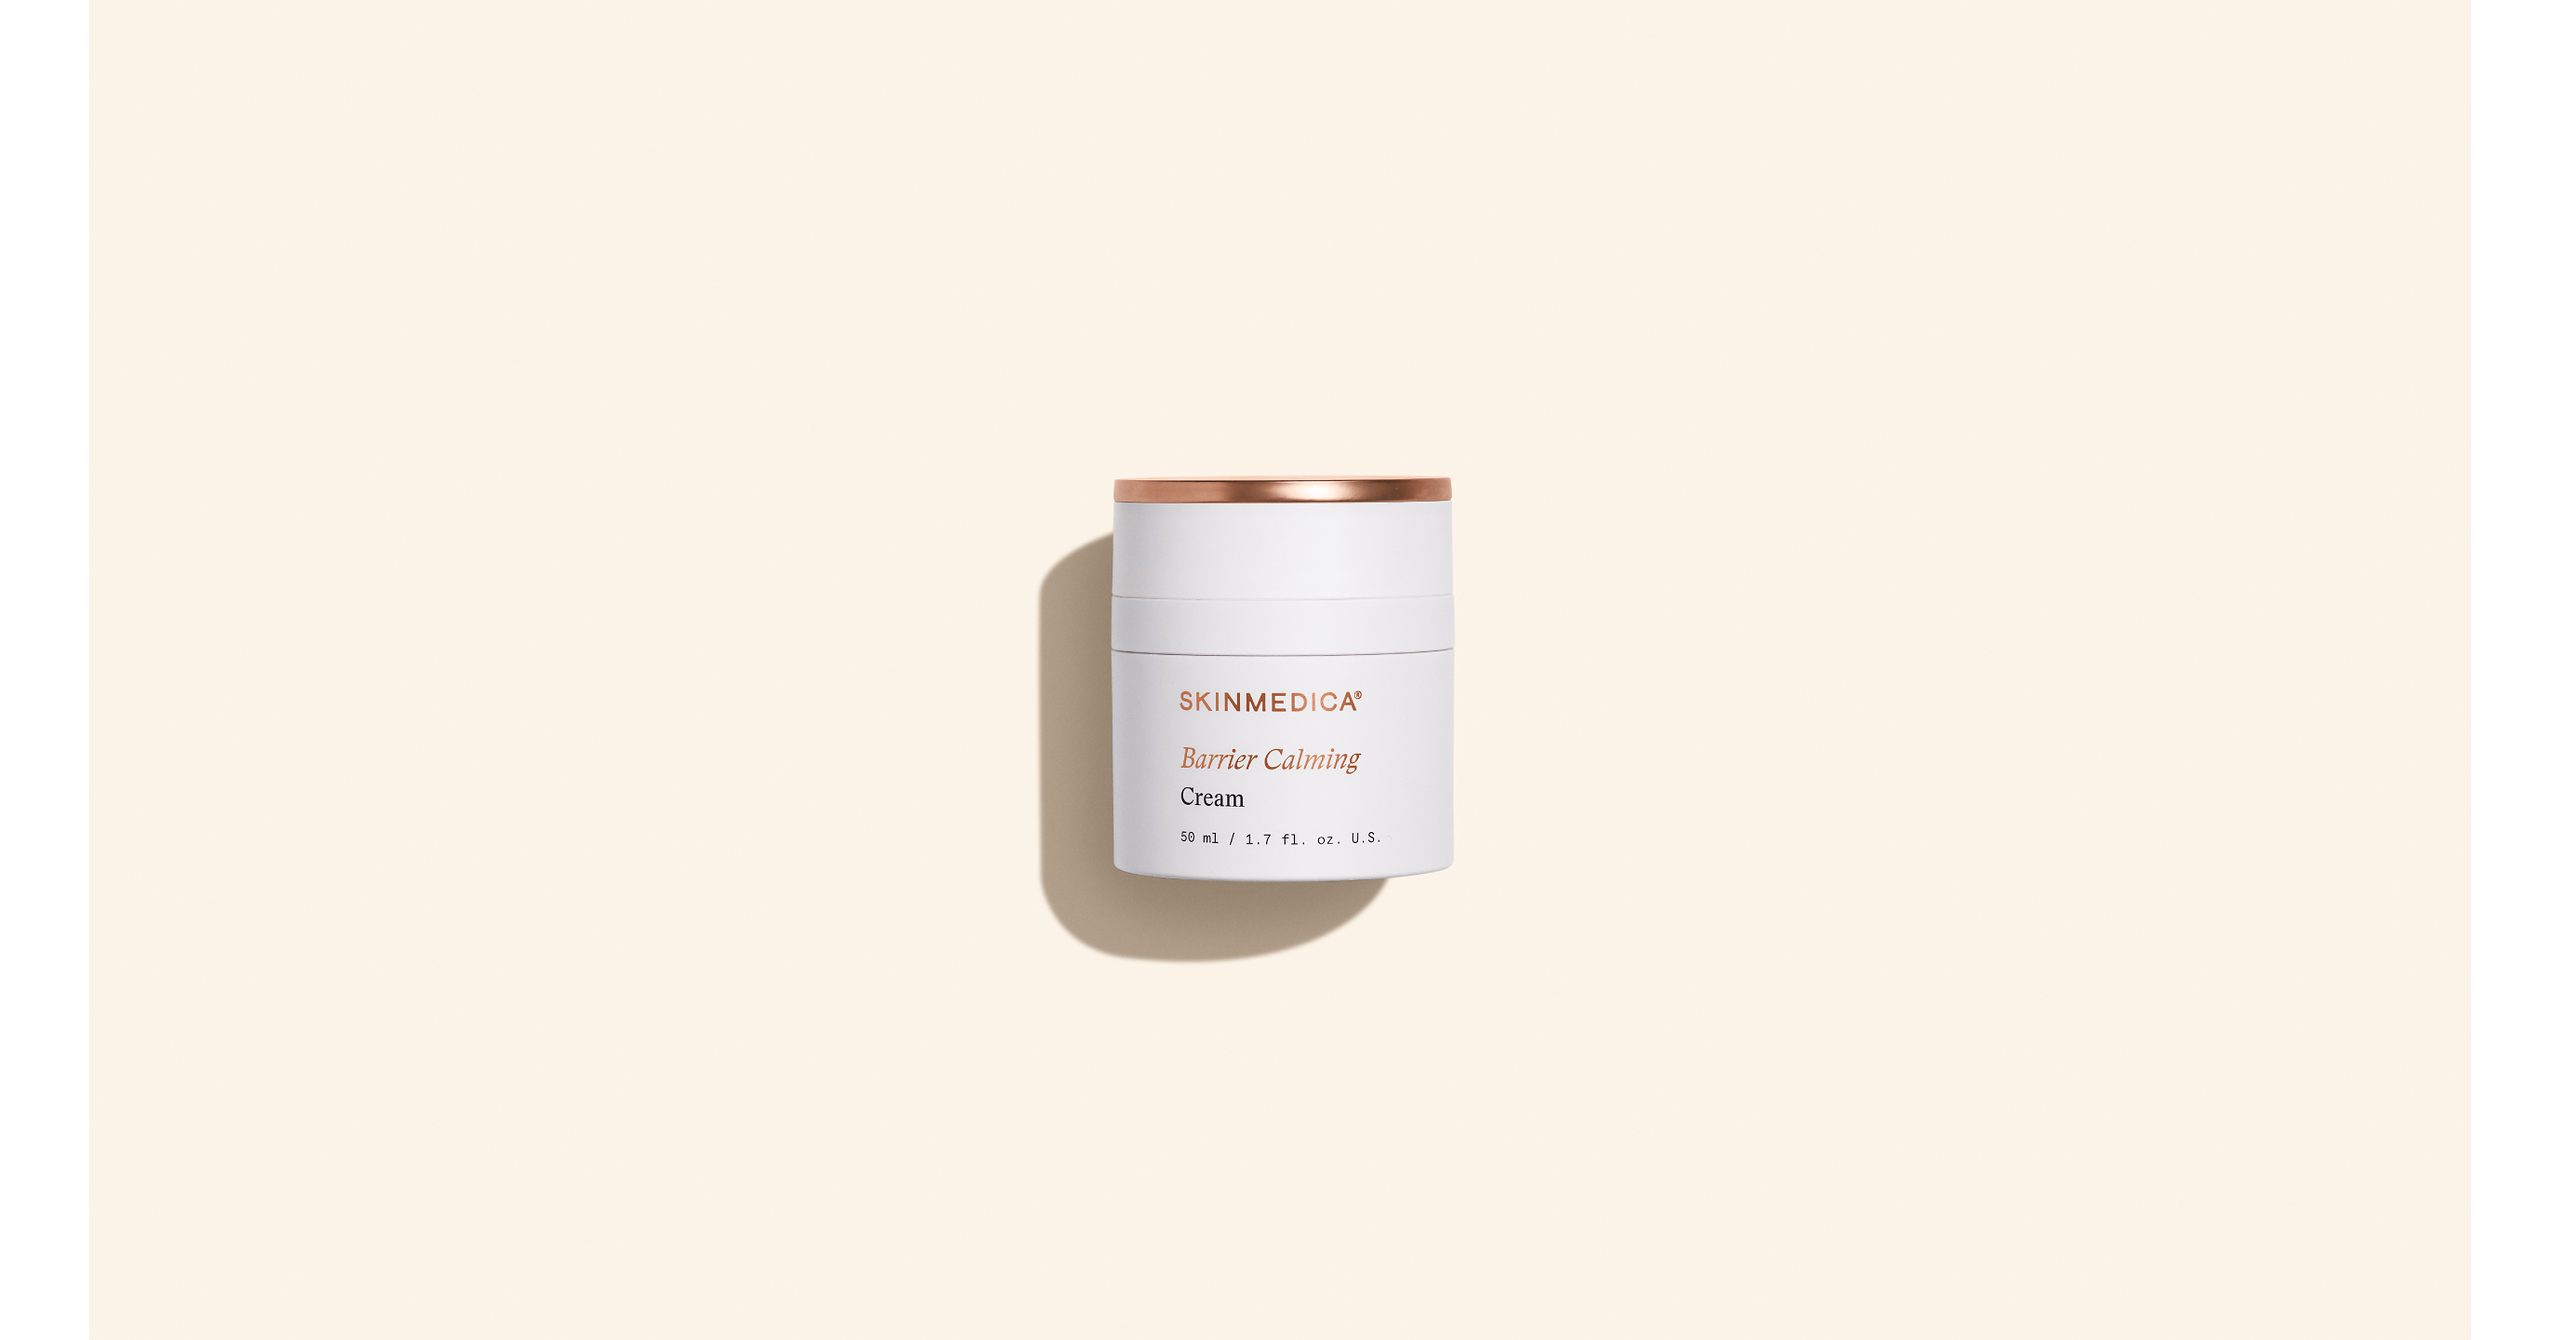
AbbVie’s Allergan Aesthetics launched SkinMedica Barrier Calming Cream ($140) and SkinMedica HA5 Hydra Collagen Facial Mist ($58), highlighting clinical improvements of 30% less skin dryness after two weeks and 31% higher hydration (immediate) with the mist. While this is a positive product expansion supported by efficacy claims, it appears more like incremental portfolio news rather than a scale financial catalyst.
Analysis
This reads more like franchise defense than incremental growth. The economic value is in deepening physician/spa channel lock-in around a broader aesthetics workflow, which can raise attach rates for injectables and device-driven visits more than it moves skincare revenue on its own. That matters because the highest-margin part of the portfolio is often the consultative relationship, not the product SKU; any product that increases repeat clinic traffic can improve lifetime value even if the launch is modest at first.
Near term, the stock should not rerate meaningfully from a cosmetic launch alone unless channel checks show meaningful pull-through. The more relevant 1-3 month catalyst is management commentary on whether aesthetics demand is holding up in a discretionary spend environment; if consumers are trading down, premium physician-dispensed skincare can stall even with strong branding. Over 6-18 months, proof that the aesthetics platform can consistently monetize the patient journey would support a higher quality multiple for ABBV's non-immunology assets.
The contrarian point is that "barrier care" is a crowded claim and may be more category marketing than differentiated science. If reorders are weak, this becomes promotional noise rather than a durable growth vector, and the market should not pay up for it. The main falsifier is softness in Allergan Aesthetics segment growth or margin compression on the next couple of prints despite the launch cadence.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.18
Ticker Sentiment
Key Decisions for Investors
- No standalone event trade in ABBV here; treat as a low-materiality brand-defense action and wait for the next quarterly aesthetics print before adding risk.
- If ABBV sells off on this news with no change to segment guidance, buy the dip for a 1-3 month mean-reversion trade; stop out if aesthetics revenue or operating margin disappoints next quarter.
- Relative-value idea: long ABBV / short EL over 3-6 months if channel checks show physician-dispensed skincare gaining share versus prestige skincare, with ABBV benefiting from procedure attach and EL more exposed to discretionary beauty cycles.
- Watch for any management evidence of higher repeat purchase rates or cross-sell into injectable visits; if confirmed, consider increasing ABBV weight against the S&P 500 healthcare basket.
More News
- Big pharma stocks near all-time highs as tech selloff pushes investors toward safer bets
- AI Capex, Gamble or Jackpot?: Market Snapshot
- ‘I told you so’: China’s chip sector is making breakthroughs—and U.S. export controls are the reasons why
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- The IPO drought is driving private equity-owned companies to the debt market to pay investors
- Hybe shares jump 10% as K-pop sensation BTS' tour lifts earnings hopes