
SpaceX Offers Exponential Upside And Extreme Risk
Source: seekingalpha.com
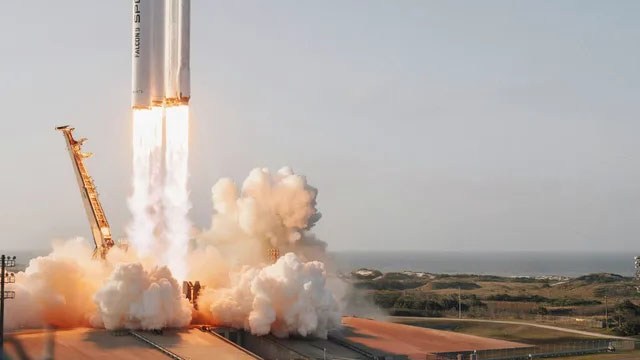
The article frames SpaceX/Starlink as having exponential upside across Space, Connectivity, and AI, with Starlink’s cash generation funding capital-intensive Space and AI. It highlights exceptional execution and capital risk, with valuation described as highly uncertain—$110–$120 viewed as an attractive entry zone, while $140–$150 is fair but not compelling. The key investor takeaway is that position sizing and timing are critical given the risk-adjusted uncertainty.
Analysis
The market is still pricing SpaceX like a platform compounder, but the real variable is not top-line growth — it is whether Starlink can keep funding the rest of the stack without forcing repeated external capital or partner concessions. If that flywheel works, the beneficiaries are the suppliers and channels that can scale with LEO demand; if it breaks, the winners shift to incumbent connectivity providers that can absorb a few more years of overbuild and pricing pressure.
Second-order, the most vulnerable public names are the legacy satellite cash cows and weaker rural connectivity proxies: IRDM and GSAT would face both valuation compression and slower monetization if Starlink keeps improving mobility use cases. By contrast, the telecoms are not obvious losers immediately because they can pass through some of the competitive pressure via higher capex and bundle strategy, but the margin hit shows up over 6-18 months if wholesale partnerships expand faster than legacy share buybacks can offset.
The contrarian point is that consensus may be underestimating execution risk while simultaneously overpaying for optionality. The catalyst path is milestone-driven over the next 1-3 months: launch cadence, reusability proof, and any hard data on subscriber economics; any miss there would likely compress private valuation marks quickly. Conversely, if Starship and mobile partnerships keep de-risking, the trade is not to chase the private asset, but to own the public secondaries that benefit from broader LEO adoption without carrying the same capital intensity.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.05
Ticker Sentiment
Key Decisions for Investors
- No direct SpaceX trade in public markets; treat this as a watch item until there is verifiable data on Starship cadence and Starlink unit economics.
- Relative-value short IRDM / GSAT basket into any incremental positive Starlink mobility headlines; thesis is 10-20% multiple compression over 1-3 months if competitive pressure keeps building.
- Use T or VZ only as a defensive hedge, not a directional short: the cleaner setup is that they can absorb a modest LEO threat, but if rural churn or capex guidance worsens, the downside is in margins rather than revenue.
- Set a falsification alert around any launch or service-disruption miss: a slip in repeat launch cadence or evidence Starlink cash flow is not self-funding would invalidate the bullish optionality case quickly.
More News
- 'Cannot play hide and seek': Singapore minister's warning over haze sends agricultural stocks lower
- BlackRock, GIC among investors chasing Indian telecom major Jio's IPO as anchor bids top $26 billion
- Nscale, Anthropic Eye $45 Billion Cloud Deal as AI Trade Rebounds
- Volkswagen bet on Xpeng to save its China business. It’s not going to plan
- Gartner analyst behind tech rout: AI returns are not yet large enough to justify neocloud build-out
- Asia stocks slump as AI jitters hammer Korean chipmakers ahead of tech earnings
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- The Great Divergence: North American Banking at the Crossroads of Monetary Policy and Agentic AI (Q4 2025 Bank Earnings)
- AI for M&A Target Screening: From Universe to Deal File