
Pudu Robotics présente la série PUDU GT et ses solutions intelligentes d'entretien des espaces verts au salon GaLaBau 2026
Source: PR Newswire
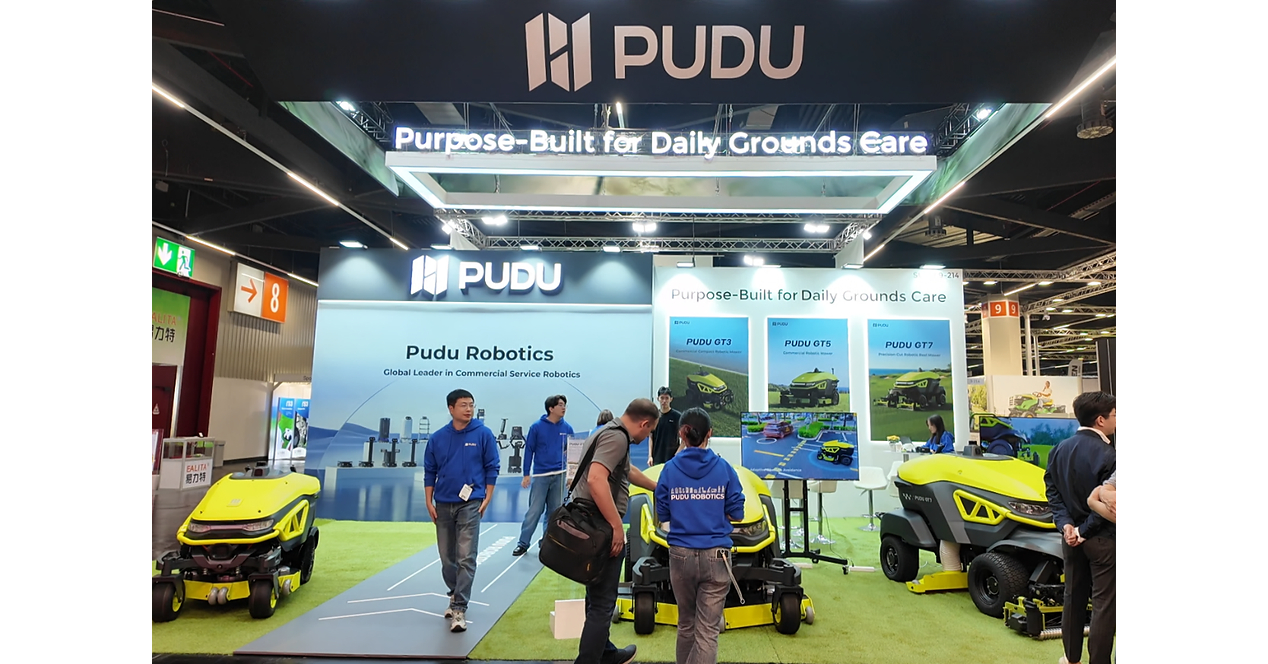
Pudu Robotics debuted its PUDU GT commercial autonomous lawn-mower series at GaLaBau 2026, comprising the GT3, GT5 and GT7 for fragmented properties, large green spaces, and precision applications such as golf courses and professional sports fields. The GT5 features a 60-inch (152 cm) cutting width and autonomous operation, while the GT7 uses a 62-inch (160 cm) triplex roller system with high-precision autonomous navigation. The launch expands Pudu's commercial-service robotics portfolio into outdoor grounds maintenance, with an Australian market presentation planned for October.
Analysis
This is a private-company product-marketing event rather than a disclosed order, pricing, or channel-development milestone, so it is not independently investable today. The relevant public-market read-through is modestly negative for incumbent commercial turf-equipment vendors—Toro (TTC), Deere (DE), Husqvarna (HSQVY), and Stanley Black & Decker (SWK)—only if autonomous systems begin converting labor-constrained landscaping contractors from pilot programs to fleet purchases. The economically meaningful disruption is not the mower itself but recurring fleet-management software, maintenance contracts, and lower operator-hours per acre, which could pressure equipment replacement pricing before it materially affects unit volumes.
Over the next 1-3 months, the critical diligence item is whether Pudu identifies North American/European dealers, financing partners, warranty infrastructure, or binding commercial deployments. Without those, demonstrations are unlikely to alter incumbent FY27 estimates: professional buyers prioritize uptime, parts availability, liability coverage, and service response over navigation specifications. A more immediate beneficiary of broad adoption would be landscaping operators with high labor intensity, including BrightView (BV), if autonomous equipment lowers seasonal labor costs; however, savings will likely be competed away in contract bids unless operators secure exclusivity or meaningfully improve crew throughput.
The contrarian view is that autonomous mowing remains structurally harder to monetize than indoor service robotics. Outdoor terrain variability, theft/vandalism exposure, weather downtime, safety compliance, and fragmented dealer service make total cost of ownership the gating variable. Incumbents can also bundle autonomy into entrenched dealer networks, limiting a new entrant's ability to translate technical visibility into share gains; therefore, any knee-jerk weakness in TTC or DE on this narrative would likely be overdone absent evidence of large fleet displacement.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Key Decisions for Investors
- No directional position based on this release. Create a diligence alert for disclosed distributor agreements, enterprise fleet orders, pricing, and service/warranty terms; reassess only if evidence supports a credible 2027 revenue ramp.
- Monitor TTC and DE commentary over the next two earnings cycles for autonomous commercial-turf order intake, dealer inventory, and gross-margin guidance. A cut to commercial-equipment margin guidance attributable to autonomous price competition—not merely weak end demand—would validate a short catalyst.
- Watch BV as a second-order labor-productivity beneficiary over 6-18 months, but require evidence that robotic capex produces measurable labor-hours-per-route savings without contract-price giveback before establishing a long.
- If TTC underperforms the S&P 500 by more than 10% on unverified autonomous-mower headlines while dealer-channel commentary remains intact, consider a tactical long TTC versus short XLI; thesis is incumbent distribution and aftermarket economics outweigh early-stage entrant publicity.
More News
- Wall Street’s Nasdaq hits all-time high as AI frenzy gathers pace
- Data-Center Bet Makes ESDS One of India’s Best New Listings
- Asia stocks ride tech wave higher, oil stays subdued
- South Korean solar stocks jump as curbs on Chinese sector expected to remain in place
- Trump Says US Team Met With Iranians at UNGA
- How Kevin Warsh’s rate hike exposed a 2-speed U.S. economy, with AI and housing at the poles