
PNK Group Considers Sale of Industrial Portfolio Valued at Approximately $1 Billion
Source: PR Newswire
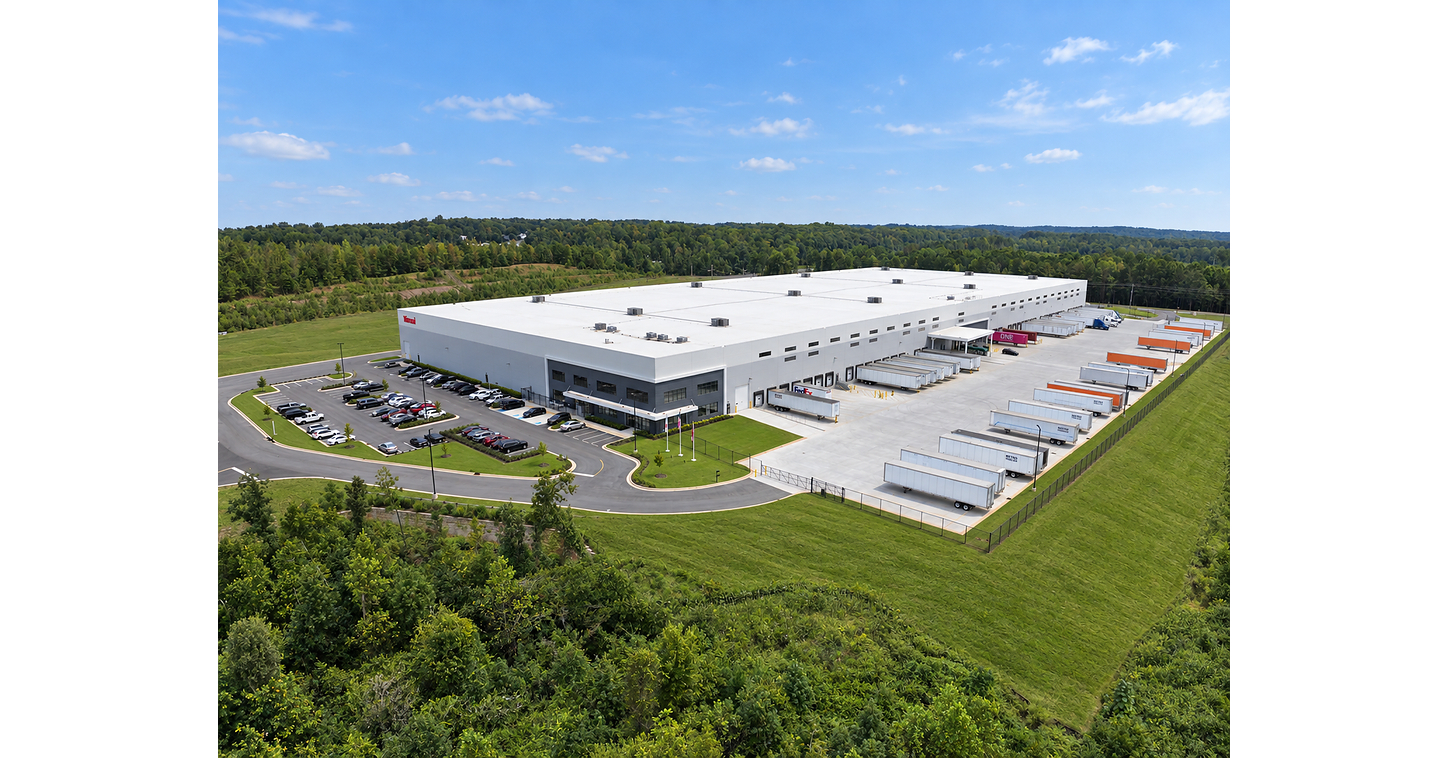
PNK Group is considering selling a 12-building industrial-property portfolio totaling approximately 7 million square feet, with a potential value of about $1 billion. More than 75% of the area is under long-term leases with highly rated blue-chip tenants; the remaining properties would be marketed once rental income stabilizes. PNK Group retained JLL as exclusive sale adviser; no completed transaction or buyer was announced.
Analysis
This is a weak, transaction-specific signal—not evidence by itself of a broad industrial-property recovery. For JLL, the mandate is directionally positive for capital-markets activity, but the fee contribution cannot be assessed from the release and is unlikely to change the equity thesis absent evidence of a larger pipeline. The more useful read-through is potential price discovery: a completed sale could establish a comp for comparable assets, but the portfolio’s geography, net operating income, lease rollover profile, buyer, and financing are undisclosed, so extrapolation to industrial REIT valuations is premature.
The marketed leased portion may appeal to core buyers seeking contracted cash flow; the portion still awaiting stabilization shifts lease-up and execution risk to whoever buys it. That split can narrow the buyer pool or widen pricing differences across the portfolio. Long leases and blue-chip tenants reduce some credit risk, but do not resolve tenant concentration, rent-versus-market, or renewal risk. The construction and versatility claims are seller positioning, not independently verified evidence of lower operating costs or superior resale value.
Near term, watch for a signed transaction and disclosed pricing/NOI rather than treating the announcement as a sector catalyst. Over 1–3 months, a strong bid would support liquidity and valuations only for assets with comparable location and cash-flow quality; a delayed or repriced process would point to financing or underwriting friction. Over 6–18 months, the broader implication depends on rates, industrial supply, and lease demand. The thesis weakens if the deal stalls, pricing implies a material discount to comparable assets, or stabilization requires meaningful concessions.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.00
Ticker Sentiment
Key Decisions for Investors
- No standalone trade in JLL: treat the mandate as a modest activity indicator, not an earnings catalyst. Reassess only if JLL reports broader capital-markets momentum or the transaction is completed with evidence of repeatable fee activity.
- Set an alert for a signed sale and disclosure of geography, price, NOI/cap rate, lease expiries, and the stabilized portion’s occupancy. Without these, do not use the headline valuation as a comp for Prologis or other industrial property owners.
- If pricing is strong, consider it a conditional positive for comparable industrial assets, not a blanket sector signal; verify local supply, rents, and lease terms first. A failed process or material repricing would falsify the liquidity-positive interpretation.
More News
- Marvell to buy Lumentum in $115 billion deal in AI data-center bet
- Statement by the Monetary Policy Board: Monetary Policy Decision
- Marvell, Lumentum tout historic $115B deal to create ‘category leader' in AI connectivity
- Kimberly-Clark closes its acquisition of Tylenol maker Kenvue. What to expect next
- In one of the largest deals in tech history, Marvell buys Lumentum for $115B
- Marvell to buy Lumentum in all-stock deal, a massive bet on AI connectivity