
Trump y China chocan por petróleo y deuda de Venezuela
Source: Bloomberg
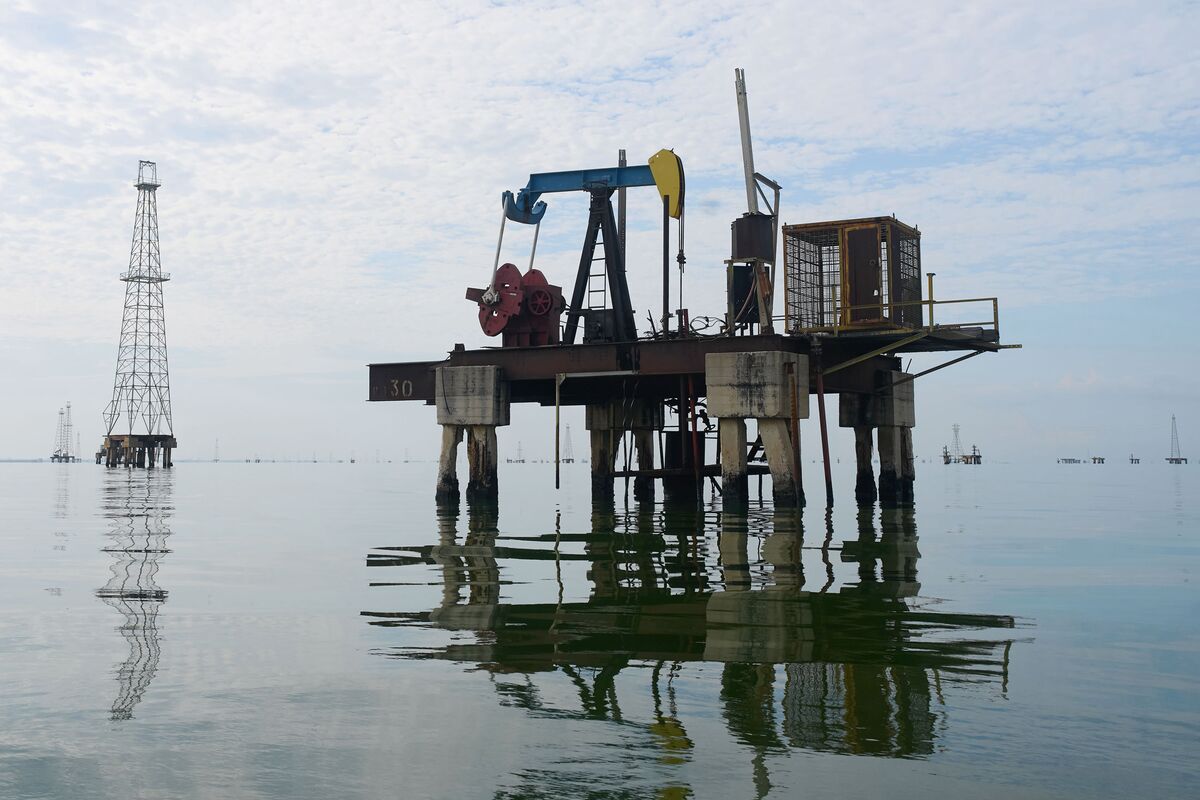
Venezuela emerge como un nuevo foco de tensión geopolítica en la rivalidad entre Trump y China, ligado a energía y deuda. La noticia no aporta cifras, pero sugiere mayor riesgo de desalineamientos y volatilidad potencial en exposiciones relacionadas con el país y sus variables de crédito/energía.
Analysis
This is less a direct oil beta story than an optionality-on-policy story. Venezuela matters because it can swing the availability of heavy sour barrels into the US Gulf Coast, so the first-order winners are refiners with coking capacity, not upstream producers; the market should care more about Maya/HEM spreads and crack margins than about spot Brent on day one.
The second-order effect is on relative value inside energy: if Washington moves toward limited sanctions relief or debt-for-oil accommodation, VLO and MPC should outperform integrateds and E&Ps over 1-3 months as feedstock costs ease and utilization rises. Conversely, if the administration uses Venezuela as an anti-China lever and tightens enforcement, Chinese credit exposure and any price-sensitive heavy crude substitutes become vulnerable, while Gulf Coast refiners lose the most optionality.
The sovereign-debt angle is binary and probably over-discussed. Venezuela bonds and PDVSA claims only rerate meaningfully if there is a credible path to asset protection, sanctions relief, and payment mechanics; otherwise the trade is mostly headline noise. The contrarian view is that the market may overprice a Trump-driven regime shift: political constraints make a full reset unlikely, so the best expression is spread compression in heavy crude rather than a broad commodity rally.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.15
Key Decisions for Investors
- Watch, don’t force: no immediate Brent/XLE trade until there is explicit US policy action on Venezuela sanctions or licensing; the current signal is too thin for a clean directional commodity bet.
- If sanctions relief probability rises over the next 1-3 months, go long VLO or MPC vs short XLE on a 2-4% relative-performance target; thesis is heavy sour feedstock cost relief and crack-spread expansion, with a stop if Gulf Coast differentials do not tighten.
- Treat CVX as a policy-optionality name only if there is evidence of expanded operating licenses in Venezuela; otherwise avoid a long before clarity because the political headline risk can swamp fundamentals.
- Keep Venezuela sovereign debt/PDVSA claims on alert status, not as a recommendation: only consider small distressed optionality if there is a verified debt-restructuring or sanctions-waiver framework; falsifier is continued sanctions rigidity and no improvement in legal recoveries.
More News
- Putin reportedly suggests summit with Trump and Xi to decide fate of Ukraine
- Ukraine launches over 1,000 drones at Russia, setting oil facilities ablaze
- Trump defends Russian sanctions relief, lashes out at Zelenskyy
- China’s Coal Output Drops as Concerns Build Over Winter Supply
- Asian stocks skid, Wall Street and bonds aided by oil slip
- Brent crude hovers near $109 a barrel as Ukraine resumes energy strikes, tankers attacked in Middle East
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AllMind Discusses Ontario's AI Economy with Minister Stephen Crawford and Supply Ontario CEO James Wallace
- AI Research Tools for SEDAR+, UK and ASX Filings