
BOE Chief Economist Pill Fears Central Bank Push to Finance Government Deficits
Source: Bloomberg
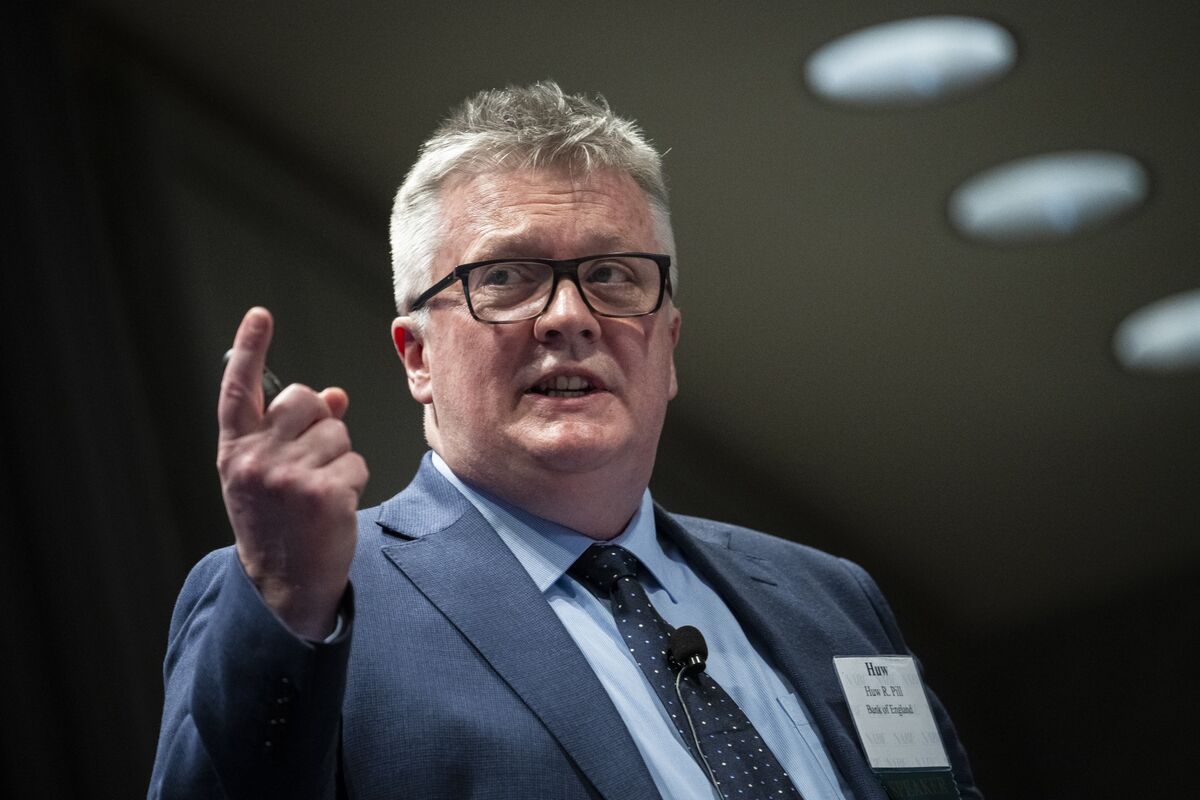
The article warns that proposals linked to the BOE’s “Pill” could be used to finance government deficits, raising concerns about central bank independence. It notes that momentum for reform has been weakened (“hit by sting”), with political criticism of central banks referenced from both the US and UK. Overall, the risk to credibility could be a headwind for gilt and broader rates sentiment even without a specific announced policy size.
Analysis
The market mechanism is not a direct earnings hit so much as a higher UK term premium: if investors start to price even a modest erosion of central-bank independence, long-duration assets should reprice first, then the currency, then domestic equity multiples. The immediate winners are UK multinationals with overseas revenue and balance sheets naturally hedged to a weaker pound; the losers are domestic rate-sensitive businesses and anyone implicitly short sovereign duration, especially pension-heavy financials and insurers that mark long gilts to market.
The second-order risk is contagion to funding costs. Even without policy change, persistent chatter about fiscal-monetary coordination can widen the gap between gilt auctions and swaps, which feeds into mortgage pricing and UK consumer confidence with a 1-3 month lag. That is more important than the headline noise: if the market demands a few extra basis points of term premium, domestic UK equities can underperform despite benign global growth.
Contrarian view: this may be more of a credibility tax than a regime shift. If inflation data softens and the BoE communicates forcefully, the trade can reverse quickly; the key falsifier is a stable or tightening 10Y gilt spread versus swaps after the next policy communication. Over 6-18 months, though, repeated political pressure can become self-reinforcing, and the cheapest expression is likely not via cash equities but via duration and FX.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.25
Key Decisions for Investors
- Short FXB vs long UUP over 1-3 months: monetize a higher UK policy-risk premium if rhetoric persists; cover if GBP stabilizes after the next BoE communication.
- Underweight UK domestic rate sensitives and overweight FTSE 100 exporters, using EWU as the broad wrapper if single-name liquidity is poor; the thesis is a weaker pound and lower domestic multiple, not a recession call.
- Watch IGLT or UK long-gilt futures as the cleanest market signal; if 10Y gilt yields back up 15-20 bps without a growth shock, add to duration short exposure.
- Avoid forcing a bank short unless credit spreads widen: the first-order effect is FX/curve, while banks only become meaningful losers if mortgage spreads or deposit betas reprice for several weeks.
More News
- China’s Q3 GDP growth accelerates to 4.5%, beating forecast
- Why hedge funds could be making a bond market shock more likely
- 'MASSIVE ECONOMIC DAMAGE': 17 States FIGHT Wall Street's ESG standards
- Fuel prices dominate midterm election discussions, but spiking utility bills may be the difference maker
- While consumers are angry about high-tech ways to set prices, a study of dynamic pricing found half the U.S. changes it recorded were decreases
- France Faces Unrest Over Rising Living Costs
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: Sector Analysis, Improvements on Research Data, and Performance Enhancements
- Choosing an AI Copilot for Equity Research