
Agthia annonce une croissance de son chiffre d'affaires malgré un contexte économique difficile
Source: PR Newswire
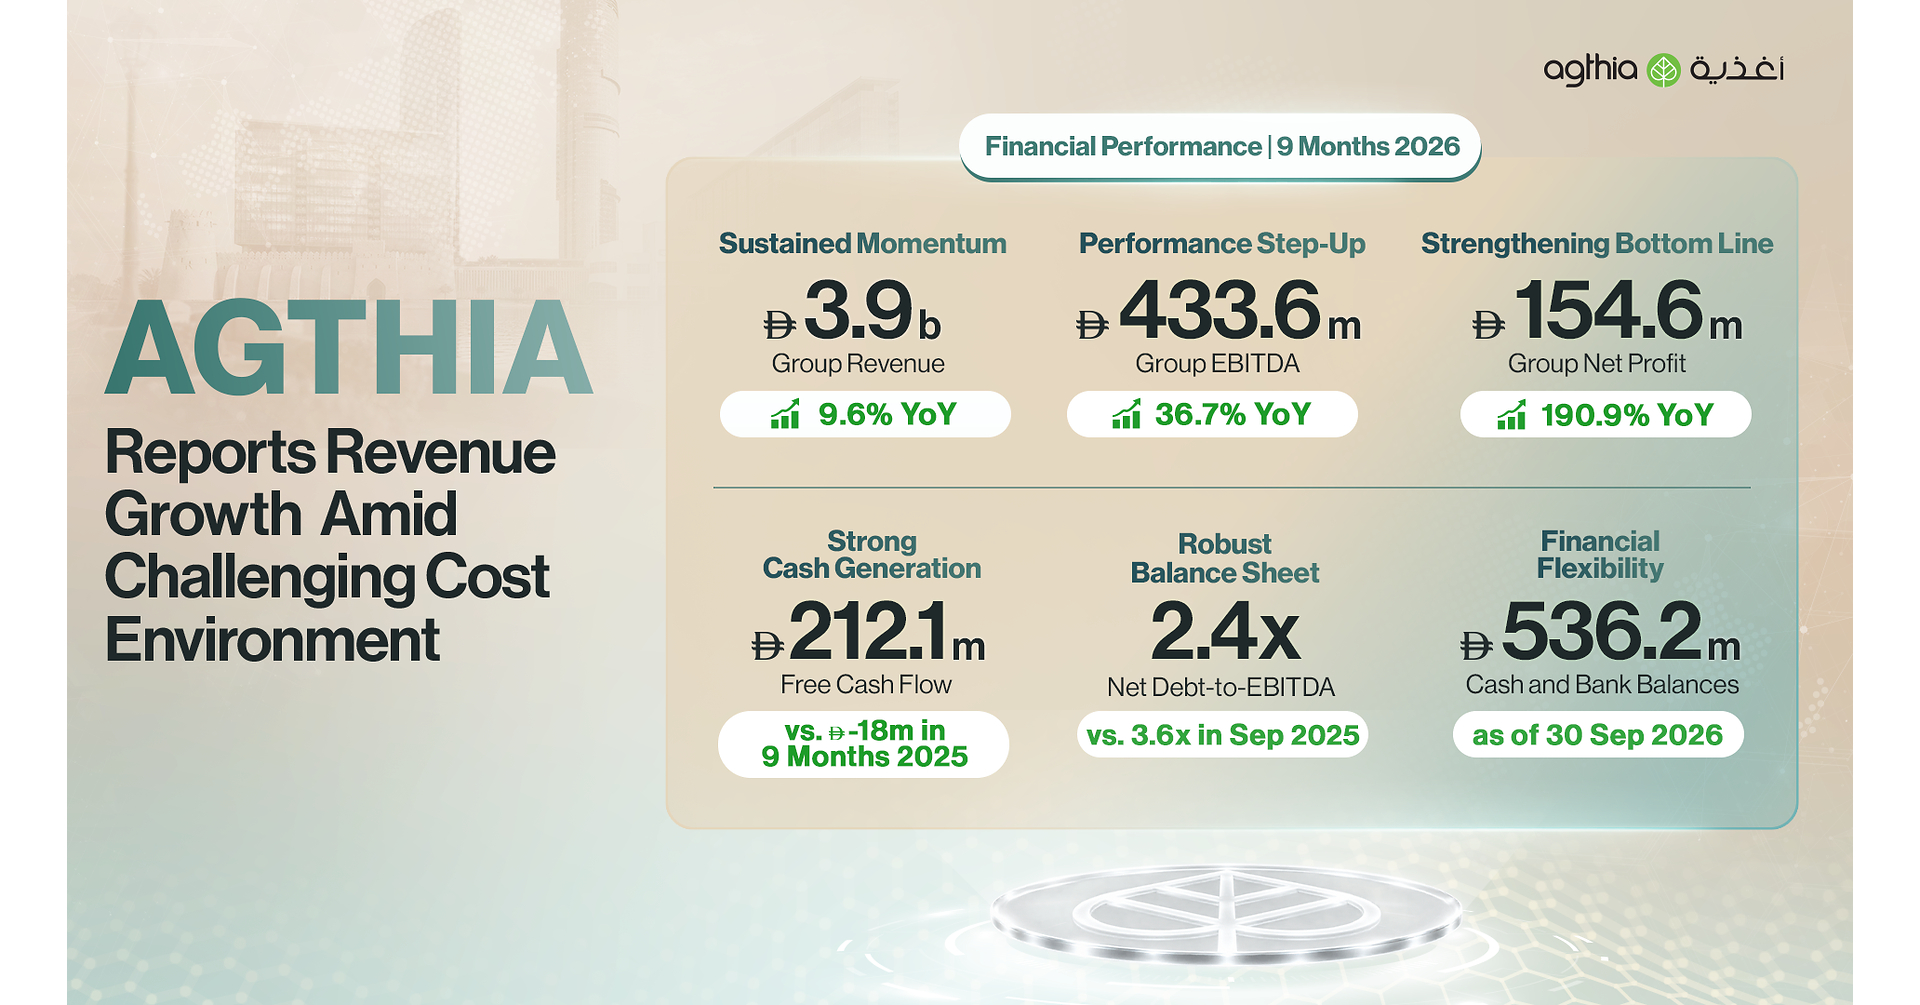
Agthia’s Q3 2026 revenue rose 14.4% year over year to AED 1.3 billion, including AED 104.7 million in one-off sales; underlying growth was 5.2%. EBITDA increased 39.0% to AED 123.1 million, while nine-month net profit nearly tripled to AED 154.6 million and free cash flow reached AED 212.1 million. Results also showed segment-level pressure: agribusiness EBITDA fell 39.3% to AED 31.4 million as input and distribution costs rose, while higher PET, freight and logistics costs weighed on other operations.
Analysis
The headline earnings acceleration overstates the change in underlying momentum: one-off sales inflate reported growth, while the prior-year comparison is clouded by a Snacking impairment. The more useful signal is modest underlying top-line growth alongside sharply divergent segment economics. That raises the risk that group-level margin gains are concentrated in the Snacking reset and do not yet demonstrate durable pricing power across the portfolio.
The key second-order exposure is input-cost transmission. PET and distribution costs pressure water economics; feed and other input inflation plus logistics are already compressing Agthia’s agribusiness profitability. If price increases lag costs, stronger sales volumes can still dilute earnings. Regional supply-chain disruption also creates asymmetric risk: food-security demand may support near-term orders, but those sales may not recur, while export interruptions can delay recovery in transformed businesses.
Over 1–3 months, the catalyst is evidence in the next update that organic growth converts to cash earnings and that agribusiness margins stabilize. Over 6–18 months, Saudi protein capacity and Snacking’s reset offer operating leverage, conditional on utilization and repeat demand. The contrarian opportunity is that the market may either over-credit the reported profit rebound or underweight the value of improving balance-sheet flexibility. Without valuation, share-price reaction, and segment-level cash conversion, the print alone does not establish an attractive entry.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Key Decisions for Investors
- Do not chase the earnings headline. Before initiating a position in Agthia, verify the market reaction and valuation, and separate recurring sales from one-off food-security revenue and impairment-related comparison effects.
- Set a 1–3 month watch for segment EBITDA and gross-margin trends, especially agribusiness. A stabilization alongside continued underlying sales growth would support a conditional long; further margin contraction despite price actions would falsify it.
- Track PET, feed-input, freight and distribution costs, plus regional export logistics. These are the near-term variables most likely to determine whether sales growth translates into cash earnings; deterioration would argue against adding exposure.
- Treat Saudi protein expansion and the Snacking reset as 6–18 month optionality, not yet proven earnings drivers. Seek evidence of repeat demand, capacity utilization and sustained cash conversion before underwriting those gains.
More News
- Tech stocks are suffering their biggest selloff since Covid, as investors see premature end to AI datacenter boom
- Elon Musk's Tesla and SpaceX lose over $420 billion in combined market cap after midterms
- Iran says tankers struck in Hormuz amid fears of new US attack
- The Iran war has cost U.S. households nearly $2,000 each. New strikes could keep the bill climbing
- Qualcomm slides 9% after earnings, leading post-election chip stock sell-off
- Costco is taking aim at its May record high — how it got here and where's it going