
VEVOR Concludes IFA Berlin 2026 Debut, Looks Ahead to Further European Expansion
Source: PR Newswire
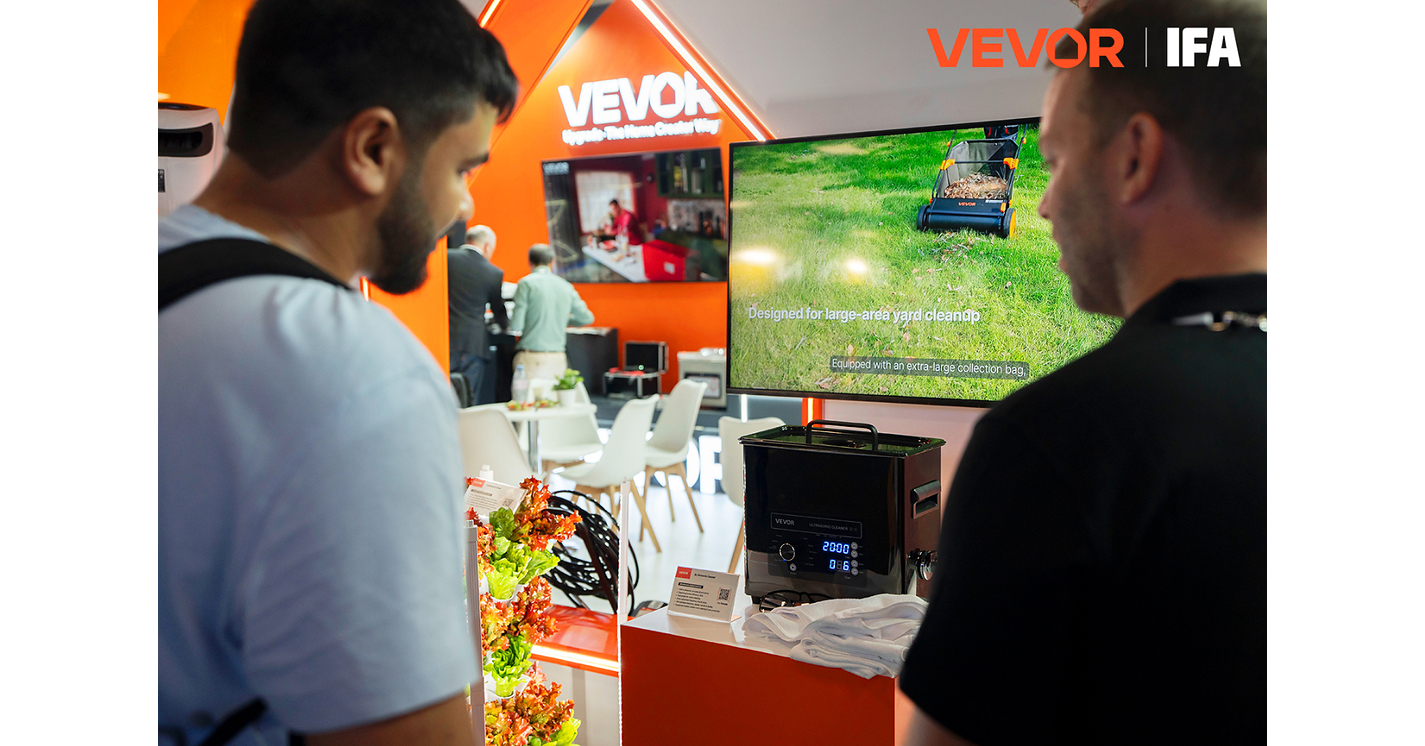
VEVOR concluded its IFA Berlin 2026 debut and outlined European expansion plans, including its first European physical store in France in 2027. The home-improvement retailer currently offers about 15,000 SKUs in Europe and operates 22 European warehouses, with further investment planned in logistics, customer service, after-sales support and offline retail. The announcement supports VEVOR's long-term omnichannel growth strategy but is unlikely to materially affect broader markets.
Analysis
This is not independently investable news: VEVOR is private, and the announcement provides no European revenue, store-level economics, customer-acquisition cost, return-rate, or profitability disclosures. A single physical location is more likely a brand-validation and returns/service experiment than a near-term volume disruptor; its significance depends on whether the company can convert marketplace demand into lower-cost direct customer relationships.
The relevant public read-through is modestly negative for value-oriented European home-improvement and tool retailers if VEVOR uses its regional inventory footprint to compress delivery times and price aggressively. Kingfisher (KGF.L), Hornbach (HBM.DE), Bauhaus-adjacent private operators, and ManoMano-facing marketplace sellers have more exposure to entry-level tools, storage, garden, and kitchen categories where private-label substitution is easiest; premium brands such as Stanley Black & Decker (SWK) and Techtronic Industries (0669.HK) are less exposed initially, but their lower-priced accessory and DIY lines could face promotional pressure.
Over the next 1-3 months, there is no clear catalyst for listed equities. Over 6-18 months, the key transmission mechanism is not one store but whether cross-border fulfillment, local returns, and after-sales support allow VEVOR to raise conversion while holding a structurally lower price point; that would pressure gross margins and marketing spend for incumbents rather than immediately impair reported sales. The thesis is falsified if European DIY demand recovers strongly enough to offset share loss, or if customer-service/quality costs prevent VEVOR from sustaining its advertised price advantage.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Key Decisions for Investors
- No immediate position: treat this as a competitive-intelligence alert rather than a trade, given the private-company source and absence of disclosed sales or pricing data.
- Monitor KGF.L and HBM.DE quarterly for online sales growth, gross-margin commentary, private-label mix, and France-specific promotional intensity; a 100-200bp unexpected gross-margin deterioration alongside weak transaction growth would support a tactical underweight over the following 3-6 months.
- For broad European discretionary exposure, prefer premium/professional tool franchises over mass-market DIY retail: maintain relative preference for SWK or 0669.HK versus KGF.L only if channel checks show sustained VEVOR price gaps and accelerating European web traffic. Avoid initiating the pair solely on this release.
- Watch French retail launch details in 2027: store count, local pricing, return policy, and any logistics-service commitments are the missing data needed to assess whether this becomes a scalable omnichannel competitor rather than a marketing flagship.
More News
- What investors need to know about Alphabet's stock-busting earnings report
- Our next steps for Alphabet stock after earnings disappoint at nearly every turn
- Fortinet’s stock is taking a dive after earnings. Here’s why.
- Wendy's shares jump 15% as Nelson Peltz's Trian offers $1.4 billion to buy burger chain
- Microsoft's Big Bets on AI Start to Pay Off
- Google's Gemini 4 Carbon looks like a diamond in the rough