
Next Africa: IPO Catapults Nigeria’s Dangote Up the Ranks of Ultra-Wealthy
Source: Bloomberg
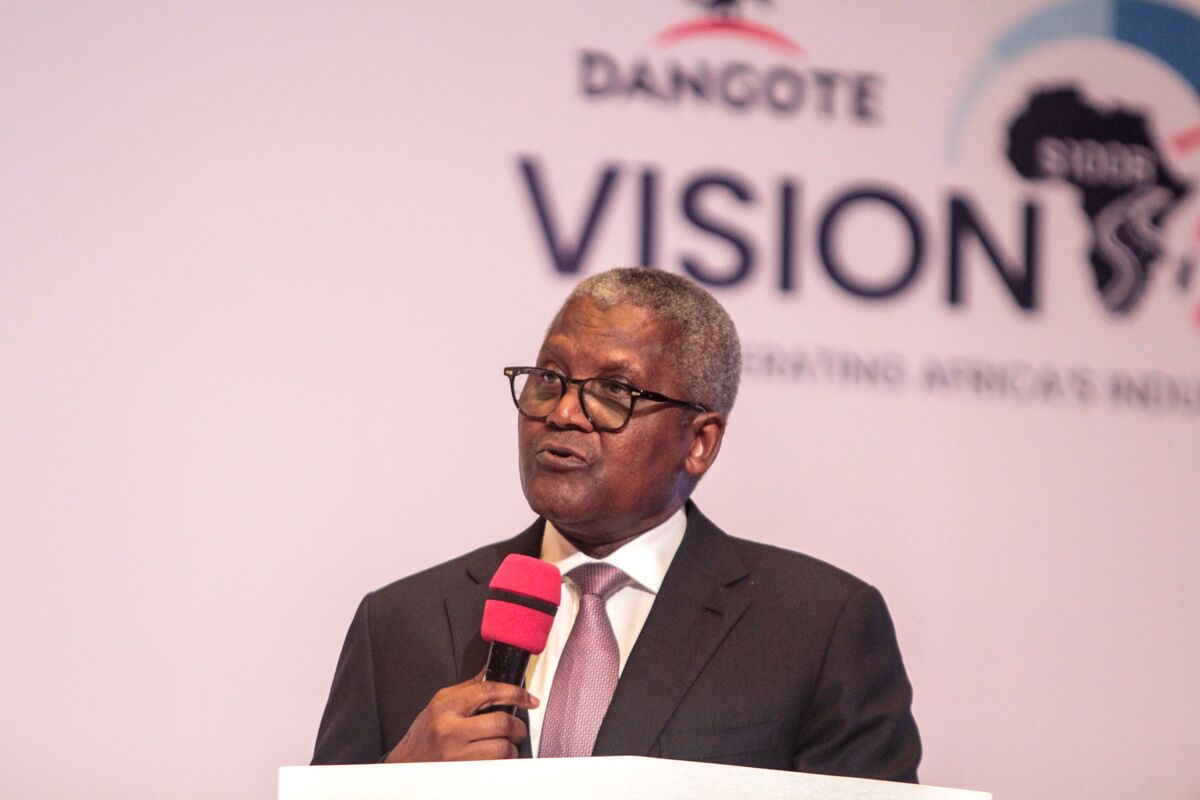
A landmark IPO of Dangote’s Nigerian refinery is expected to establish a market value for the giant asset and materially increase Africa’s richest man Aliko Dangote’s paper wealth. The listing is a notable capital-markets event for Nigeria and could draw investor attention to African energy infrastructure, though the article provides no valuation, offer size, or timing.
Analysis
The investable implication is less the founder’s marked wealth than the creation of a transparent valuation benchmark for Nigeria’s largest private industrial asset. A successful public float could lower perceived country and governance risk for large domestic corporates, supporting a rerating in NGX bellwethers—particularly DANGCEM, GTCO and Zenith Bank—if it broadens local institutional participation and attracts offshore EM flows. The near-term constraint is FX: foreign investors need credible repatriation liquidity, not simply a high-profile listing, before a Nigerian-equity rerating can persist.
For refined-products markets, local conversion capacity can compress the import-parity premium over 6-18 months, shifting profit pools away from fuel importers, offshore trading intermediaries and firms dependent on arbitrage around supply shortages. The second-order beneficiary is Nigeria’s sovereign external account: lower dollar demand for fuel imports would ease pressure on the naira and potentially reduce bank asset-quality stress tied to FX shortages. That macro channel matters more for listed Nigerian financials than any direct refinery ownership effect.
Consensus may overvalue the symbolism of a landmark transaction. Valuation, free float, dividend policy, related-party disclosures, crude supply terms and the ability to secure hard-currency earnings determine whether this becomes an institutional-quality asset rather than a scarce, locally bid-up security. A weaker naira, regulated domestic fuel prices, delayed logistics buildout, or a return of subsidized imports would quickly impair refinery-margin assumptions; these are the key 1-3 month diligence items before treating the event as a durable EM catalyst.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.45
Key Decisions for Investors
- No direct position until listing terms disclose free float, foreign-ownership access, audited earnings and dividend policy; treat the transaction as a watch item rather than a standalone IPO allocation.
- Build a 1-3 month watchlist for NGX financials GTCO and Zenith Bank: consider a small long basket only if FX-market spreads narrow and the naira remains stable for 4-6 weeks after the transaction, validating the external-account transmission. Exit on renewed material FX rationing or a sharp parallel-market premium widening.
- For investors able to trade Nigeria locally, prefer a paired expression long GTCO/Zenith versus DANGCEM if the catalyst is accompanied by improved dollar liquidity: banks capture lower system FX stress, while cement remains more exposed to domestic demand and energy-cost pass-through. Reassess after the next earnings cycle rather than relying on headline momentum.
- Avoid extrapolating the event into a broad long oil-refining trade. Monitor Nigerian domestic pump-price policy and realized refinery utilization over the next two quarters; regulated pricing or sub-70% utilization would falsify expectations of sustained import substitution and margin capture.
More News
- Budget 2026 speech
- Asian shares fall as Alphabet earnings miss drags Wall St futures lower
- China’s tech darlings are losing their shine. Here’s what’s behind the sell-off
- Can Southeast Asia pitch itself as an ‘all-in-one’ chip hub?
- Aker BP Q3 profit tops forecast on $870 million writedown reversal
- Wall Street looks past Fed pause to tech earnings and AI rebound