
Jay Rouse Joins ConstructConnect as EVP, Chief Revenue Officer to Accelerate Next Phase of Growth
Source: PR Newswire
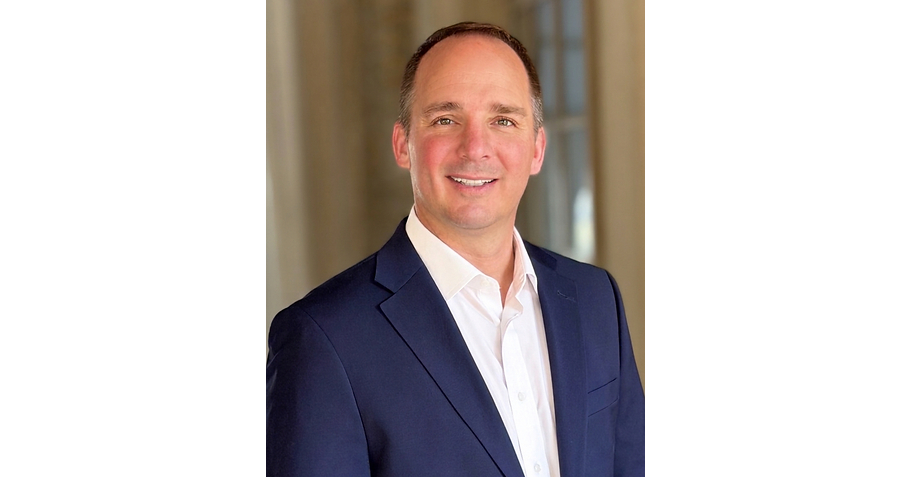
ConstructConnect appointed Jay Rouse as EVP and Chief Revenue Officer, tasked with leading sales, customer success, and go-to-market. The company highlighted AI-driven preconstruction tooling, including Takeoff Boost that delivers first-draft takeoffs up to 95% faster than manual work. The hiring and product emphasis suggest a continued push to scale revenue and expand AI capabilities, though no financial targets or results were disclosed.
Analysis
This reads as an execution-quality signal, not a demand signal. For ROP, the investable question is whether a seasoned revenue operator can lift conversion, channel productivity, and expansion in a sticky vertical workflow asset enough to justify continued premium multiple support over the next 2-4 quarters. The AI narrative matters only if it translates into higher win rates or lower sales intensity; otherwise it is just marketing noise with limited P&L impact.
Second-order, the most plausible benefit is to the incumbent data/workflow stack versus point solutions: better sales discipline can widen the gap versus smaller construction-tech vendors that cannot match bundled data + estimating + workflow depth. The flip side is that AI features can also compress differentiation across the category, forcing more discounting from peers like Procore-adjacent workflow tools and Autodesk Construction Cloud-style bundles if customers view the feature set as interchangeable. PAYX is not a fundamental beneficiary or loser here; this is more a talent-output transfer than a business read-through.
Catalyst timing is medium-term. The next two earnings cycles should tell us whether this hire is producing measurable improvement in bookings quality, net revenue retention, and CAC payback; absent that, the market will treat this as a routine management update. Contrarian view: investors may overestimate how quickly a CRO change changes growth rates in enterprise software, especially in a niche with long sales cycles and entrenched workflows. The thesis is falsified if ROP fails to show even modest expansion in growth or margin metrics by the next 1-2 quarters.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Ticker Sentiment
Key Decisions for Investors
- Own ROP on pullbacks as a 6-12 month quality compounder: modestly constructive if the hire improves sales efficiency, but do not pay up ahead of evidence. Falsify if next two quarters do not show better bookings/NRR or margin leverage.
- Consider a tactical long ROP / short IGV pair over the next 1-3 months if you want to isolate execution upside from software multiple risk; target modest outperformance rather than a large alpha event.
- No direct trade in PAYX on this headline. Treat it as a talent-source read-through only; any weakness there would be an overreaction unless broader retention concerns surface.
- Set an alert for ROP commentary on channel mix and AI monetization at the next earnings call. If the company cannot tie AI to conversion, ARPU, or CAC payback, fade the enthusiasm.
More News
- FDA approves Enspryng for thyroid eye disease treatment
- FDA Approves Genentech’s Enspryng, a First-in-Class IL-6R Inhibitor, as the First and Only At-Home Subcutaneous Treatment Option for Thyroid Eye Disease (TED)
- AI Capex, Gamble or Jackpot?: Market Snapshot
- ‘I told you so’: China’s chip sector is making breakthroughs—and U.S. export controls are the reasons why
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- The IPO drought is driving private equity-owned companies to the debt market to pay investors