
Color Me Mine Hits Its Stride: 150th Studio Opens as Brand Invests in Technology and Franchise Equity Across the System
Source: PR Newswire
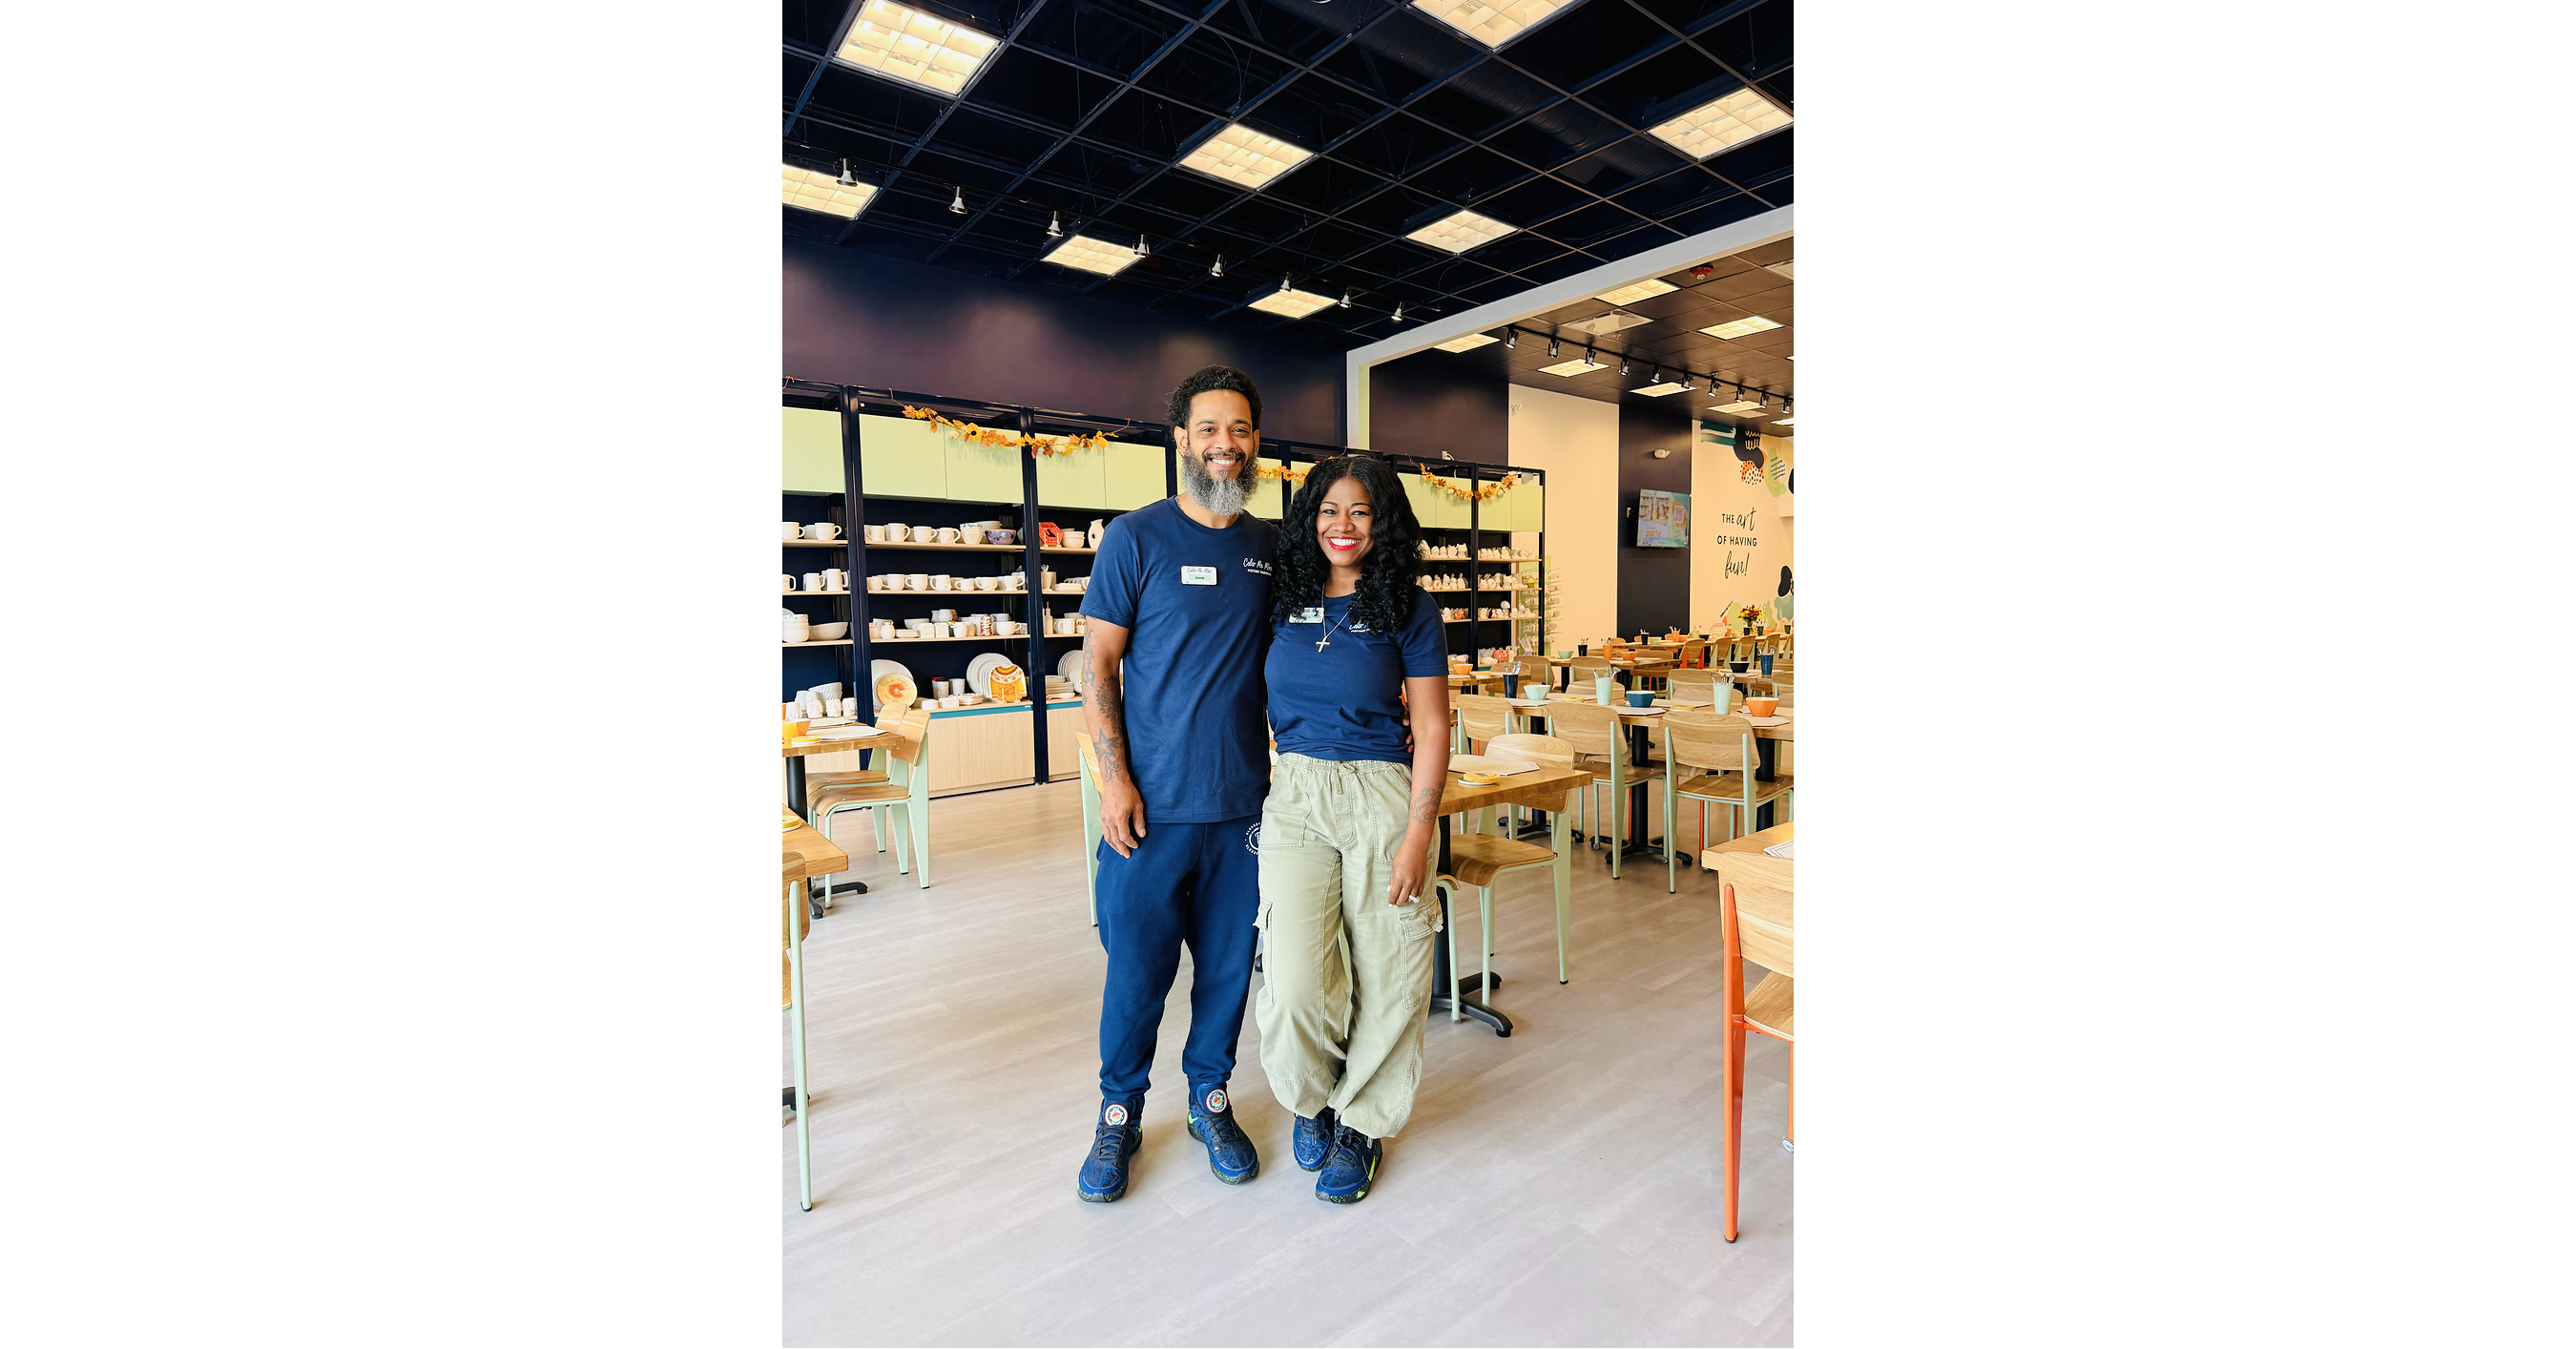
Color Me Mine reported a record studio sale of $737,000, alongside 12 new studio openings in 1H 2026 (7 new franchise agreements signed; 150th location opened in Marietta, GA). The brand is rolling out its proprietary KIN technology to ~80% of the system with completion targeted by end-September, and adding financial benchmarking to improve profitability drivers (rent, labor, and cost of goods sold). Overall momentum suggests owner confidence and supports a stronger 2H 2026 outlook, though the impact is primarily franchise-specific rather than market-wide.
Analysis
This reads as a modest positive signal for the franchise-financing ecosystem rather than a direct equity catalyst. The important mechanism is that a higher resale price and continued unit additions improve lender confidence in cash-flow durability, which can widen access to SBA and conventional financing for similar experiential concepts. That supports a broader tailwind for private franchisors, but the public-market impact is likely limited because the data are promotional, not audited systemwide unit economics.
Second-order winners are landlords and adjacent family-entertainment landlords in secondary malls and power centers: if this format is expanding, it can help absorb small footprints with relatively sticky traffic. The main competitive risk is substitution, not direct competition — any slowdown in discretionary spend would hit low-ticket experiential categories first, and tech rollout only matters if it translates into measurable labor/COGS compression over the next 2-4 quarters. In other words, the market should discount the launch headline and focus on whether franchisee payback periods actually shorten.
The contrarian view is that the resale number may be more a scarcity/optics datapoint than a true valuation benchmark, and 12 openings is not yet evidence of scalable acceleration. If same-store traffic softens into the holidays, the growth narrative can reverse quickly because these concepts are highly dependent on birthday/event frequency and mall footfall. The thesis would be falsified if broader consumer discretionary indicators roll over, if new-unit openings slip below plan in 1Q26, or if franchise disclosures show payback periods stretching despite the tech rollout.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.35
Key Decisions for Investors
- No direct trade in EUBG/STBK/TBHC/TSTS/WWRL on this release; treat the read-through as too diffuse and too promotional to underwrite a near-term earnings revision.
- Watchlist: XLY vs XLP over the next 1-3 months for a mild risk-on discretionary bid, but only if holiday spending data stay firm; downside if retail traffic weakens.
- Monitor public franchise/lifestyle operators with experiential exposure, especially PLAY and FUN, as secondary beneficiaries if consumer spending rotates toward experiences over goods; wait for confirmation in same-store sales before adding.
- Set an alert on consumer spend and mall traffic prints into the holiday season; if those weaken, fade any enthusiasm for small-ticket experiential franchises and avoid buying into the private-market multiple story.
More News
- Order to limit Starshield for Ukraine came from inside White House: Reuters reports
- The IPO drought is driving private equity-owned companies to the debt market to pay investors
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- China’s National Team Signals Return With Heavy ETF Inflows
- FDA approves Enspryng for thyroid eye disease treatment
- Giant Taiwanese chipmaker TSMC confirms it’s in talks with Elon Musk to join ‘Terafab’ complex in Texas: ‘The AI market continues to be very strong’