
ALEX JONES RETURNS TO FORMER INFOWARS STUDIO
Source: PR Newswire
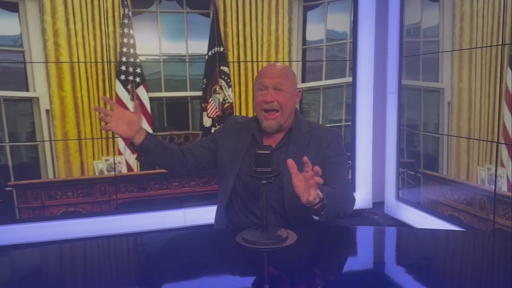
A Texas appeals court reduced Alex Jones' exemplary damages award to $1.5 million from about $45.2 million, lowering the total Texas Sandy Hook judgment to roughly $5.5 million from approximately $50 million; compensatory damages remain intact and the separate Connecticut judgment is unaffected. Jones is returning to the former InfoWars Austin studio through a new independent Alex Jones Show media and commerce platform, rather than restoring Free Speech Systems or the prior InfoWars corporate structure. The underlying InfoWars assets remain subject to continuing disputes following the rejection of The Onion parent company's proposed bankruptcy-auction purchase.
Analysis
This is not a public-equity earnings catalyst; the immediate investable read is confined to private/direct-response media, digital advertising, payments, and platform-liability ecosystems. A rebuilt audience-to-commerce funnel could create incremental spend for alternative-video infrastructure such as RUM and potentially payment/fulfillment vendors, but the addressable revenue pool and merchant relationships are undisclosed, making any near-term financial contribution immaterial to listed-company estimates.
The more relevant second-order effect is that the operating structure appears designed to ring-fence future cash generation from legacy liabilities. That may improve continuity of the new venture, but it also raises counterparty and regulatory diligence risk: advertisers, payment processors, app stores, and hosting providers could impose restrictions if litigation, asset-ownership, or brand-use disputes re-escalate. Such restrictions would impair conversion economics far faster than they would affect audience reach.
Over the next 1-3 months, watch for independently verifiable distribution, payment, sponsorship, and asset-rights announcements rather than promotional claims. The key contrarian point is that a return to a recognizable production location is not evidence of monetization recovery; direct-to-consumer media businesses require reliable payment acceptance, fulfillment capacity, repeat purchase behavior, and low customer-acquisition costs. Until those metrics emerge, there is no basis for a public-market trade.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mixed
Sentiment Score
-0.05
Key Decisions for Investors
- No directional public-equity position: the disclosed developments lack a measurable revenue, margin, or valuation linkage to any listed issuer.
- Place RUM on an event-driven watchlist for confirmed exclusive distribution, paid-content, or advertising agreements; require evidence of material traffic/revenue impact in quarterly disclosures before establishing a position.
- Monitor payment-processor and hosting-platform policy actions over the next 1-3 months as a read-through for alternative-media merchant risk, but do not extrapolate to PYPL, SQ, GOOGL, or AMZN without identified counterparty exposure.
- Treat any announced consumer-products or sponsorship partnerships as a diligence trigger: assess merchant-of-record, payment acceptance, inventory financing, and ownership of the underlying media assets before assigning value to the new platform.
More News
- History shows financial calamities occur when rates rise rapidly like this: 'Something always breaks'
- Oracle Japan shares surge 7% after record fiscal first quarter, bucking selloff of U.S. parent
- Here’s the Tesla Semi… again
- Costco makes progress on a key membership metric. Here's our new price target on the stock
- UAE bars Iranian airlines as US sanctions squeeze Iran’s aviation sector
- Akamai secures $11.6B cloud deal with Anthropic for AI workloads