
FF EAI Robotics Ecosystem (FFR) Completes Acquisition of FFAI Robotics Business, Establishing a Nasdaq-Listed Humanoid and Bionic Robotics Platform October Robot Sales Expected to Exceed 300 Units; Unveils FF OmniMind, a Unified AI Brain for All Robots
Source: PR Newswire
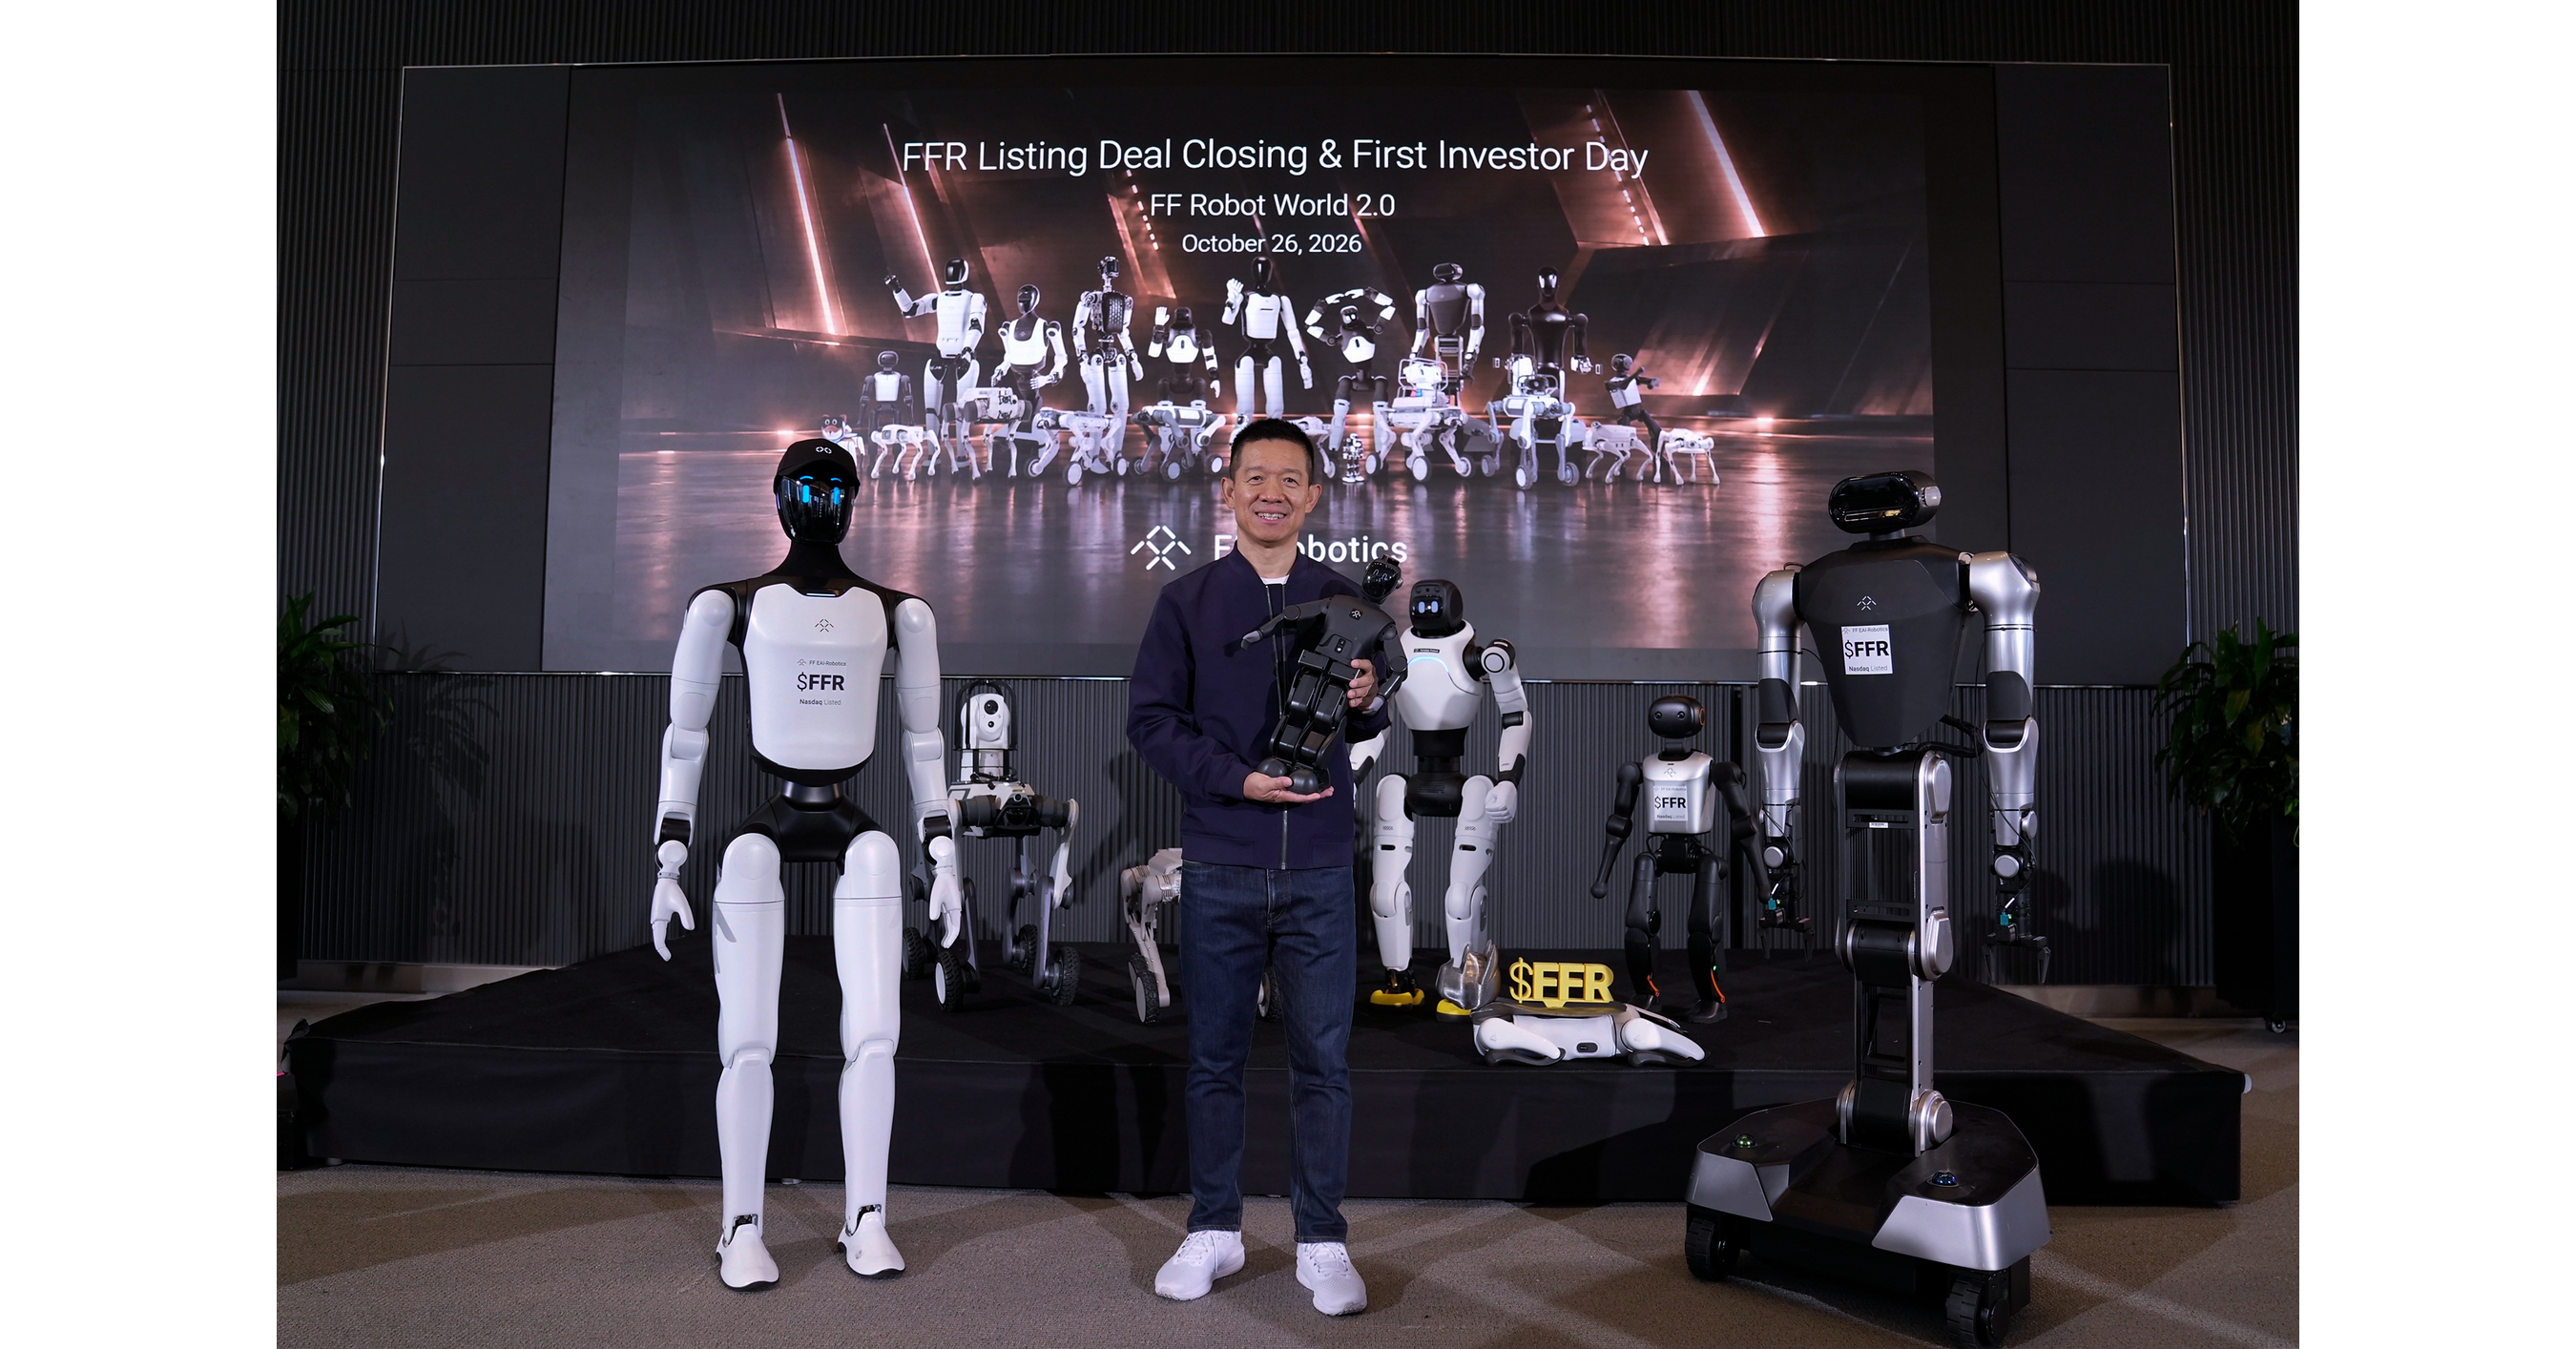
FFR completed its acquisition of FFAI’s robotics business on October 23, 2026, issuing common and non-voting convertible preferred shares to an FFAI subsidiary as consideration, and announced leadership changes and the FF OmniMind unified robot AI platform. The acquired business expects approximately 2,000 robot sales and shipments for full-year 2026 on a standalone basis, with positive unit gross margins; October shipments are expected to exceed 300. FFR also outlined projections of $45.2 million in 2027 revenue and $1.98 billion in cumulative revenue over five years, explicitly noting these are uncertain projections and that the 2026 standalone guidance is not consolidated FFR results.
Analysis
The key asymmetry is between operating ambition and security-level exposure. FFR’s headline unit and revenue outlook is largely a management plan, while the disclosed positive unit gross margin says nothing about fixed costs, cash burn, or consolidated profitability. The 2,000-unit 2026 figure is for the acquired business on a standalone full-year basis; FFR consolidates it only from October 23, so treating that figure as FFR’s reported 2026 revenue would materially overstate the near-term contribution. Partnerships and government-procurement access are options, not contracted demand.
The acquisition also changes FFAI’s exposure: it has exchanged the robotics business for common and non-voting convertible preferred shares in FFR. FFAI may retain upside if those securities appreciate, but the economic value and potential selling pressure depend on conversion terms, share count, restrictions, and FFR liquidity—details to verify in filings. This creates a possible FFR supply overhang and makes FFAI’s residual value partly dependent on a volatile, newly repositioned affiliate.
Near term, the release can support momentum, but the 1–3 month test is whether post-close filings show revenue conversion, cash collection, and manageable dilution. Over 6–18 months, repeat deployments and service economics matter more than robot shipments; failure to turn pilots into recurring orders would undermine the platform narrative. A contrarian risk is that investors capitalize long-range projections before independent evidence of customer retention or unit economics. The thesis improves with audited post-close revenue and cash receipts; it fails on material dilution, liquidity stress, or shipment growth without improving cash conversion.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Ticker Sentiment
Key Decisions for Investors
- Do not annualize the standalone 2026 guidance into FFR consolidated results. Treat FFR as a speculative event-driven name and avoid adding on the release alone; reassess after the first post-close filing provides recognized revenue, cash collections, operating costs, and fully diluted share count.
- For existing FFR exposure, size against potential equity supply: verify the preferred-share conversion ratio, voting and resale restrictions, and any registration or lockup terms in the transaction documents. A large or near-term convertible overhang would invalidate a momentum-long thesis.
- Keep FFAI as a watch rather than a clean beneficiary trade. Its value now depends partly on the FFR securities received; verify their carrying value, conversion economics, and monetization restrictions before assigning credit for the asset transfer.
- Track monthly shipments against paid deployments, repeat orders, and cash receipts—not announced partnerships or shipment counts alone. Weak conversion from pilots to paid recurring business, or a liquidity/Nasdaq compliance warning, is a thesis-failure signal; evidence of repeat institutional orders with improving cash conversion would justify revisiting the risk.
More News
- FFR completes robotics acquisition, issues 2026 guidance
- Faraday Future spins its robot business into a separate Nasdaq company
- From Wall Street to Silicon Valley, Anthropic IPO poised to have massive 'trickle-down effect'
- A shock in Brazil sends stocks plunging, while neoclouds take another hit
- EQT becomes the nation’s leading natural gas ‘juggernaut’ with a $13B deal as data center, export demand surges
- Microsoft offers buyouts to nearly 30% of workforce in ongoing AI shift