
SEDCO Capital and Wahed Partner to Broaden Access to Makkah and Madinah Real Estate
Source: PR Newswire
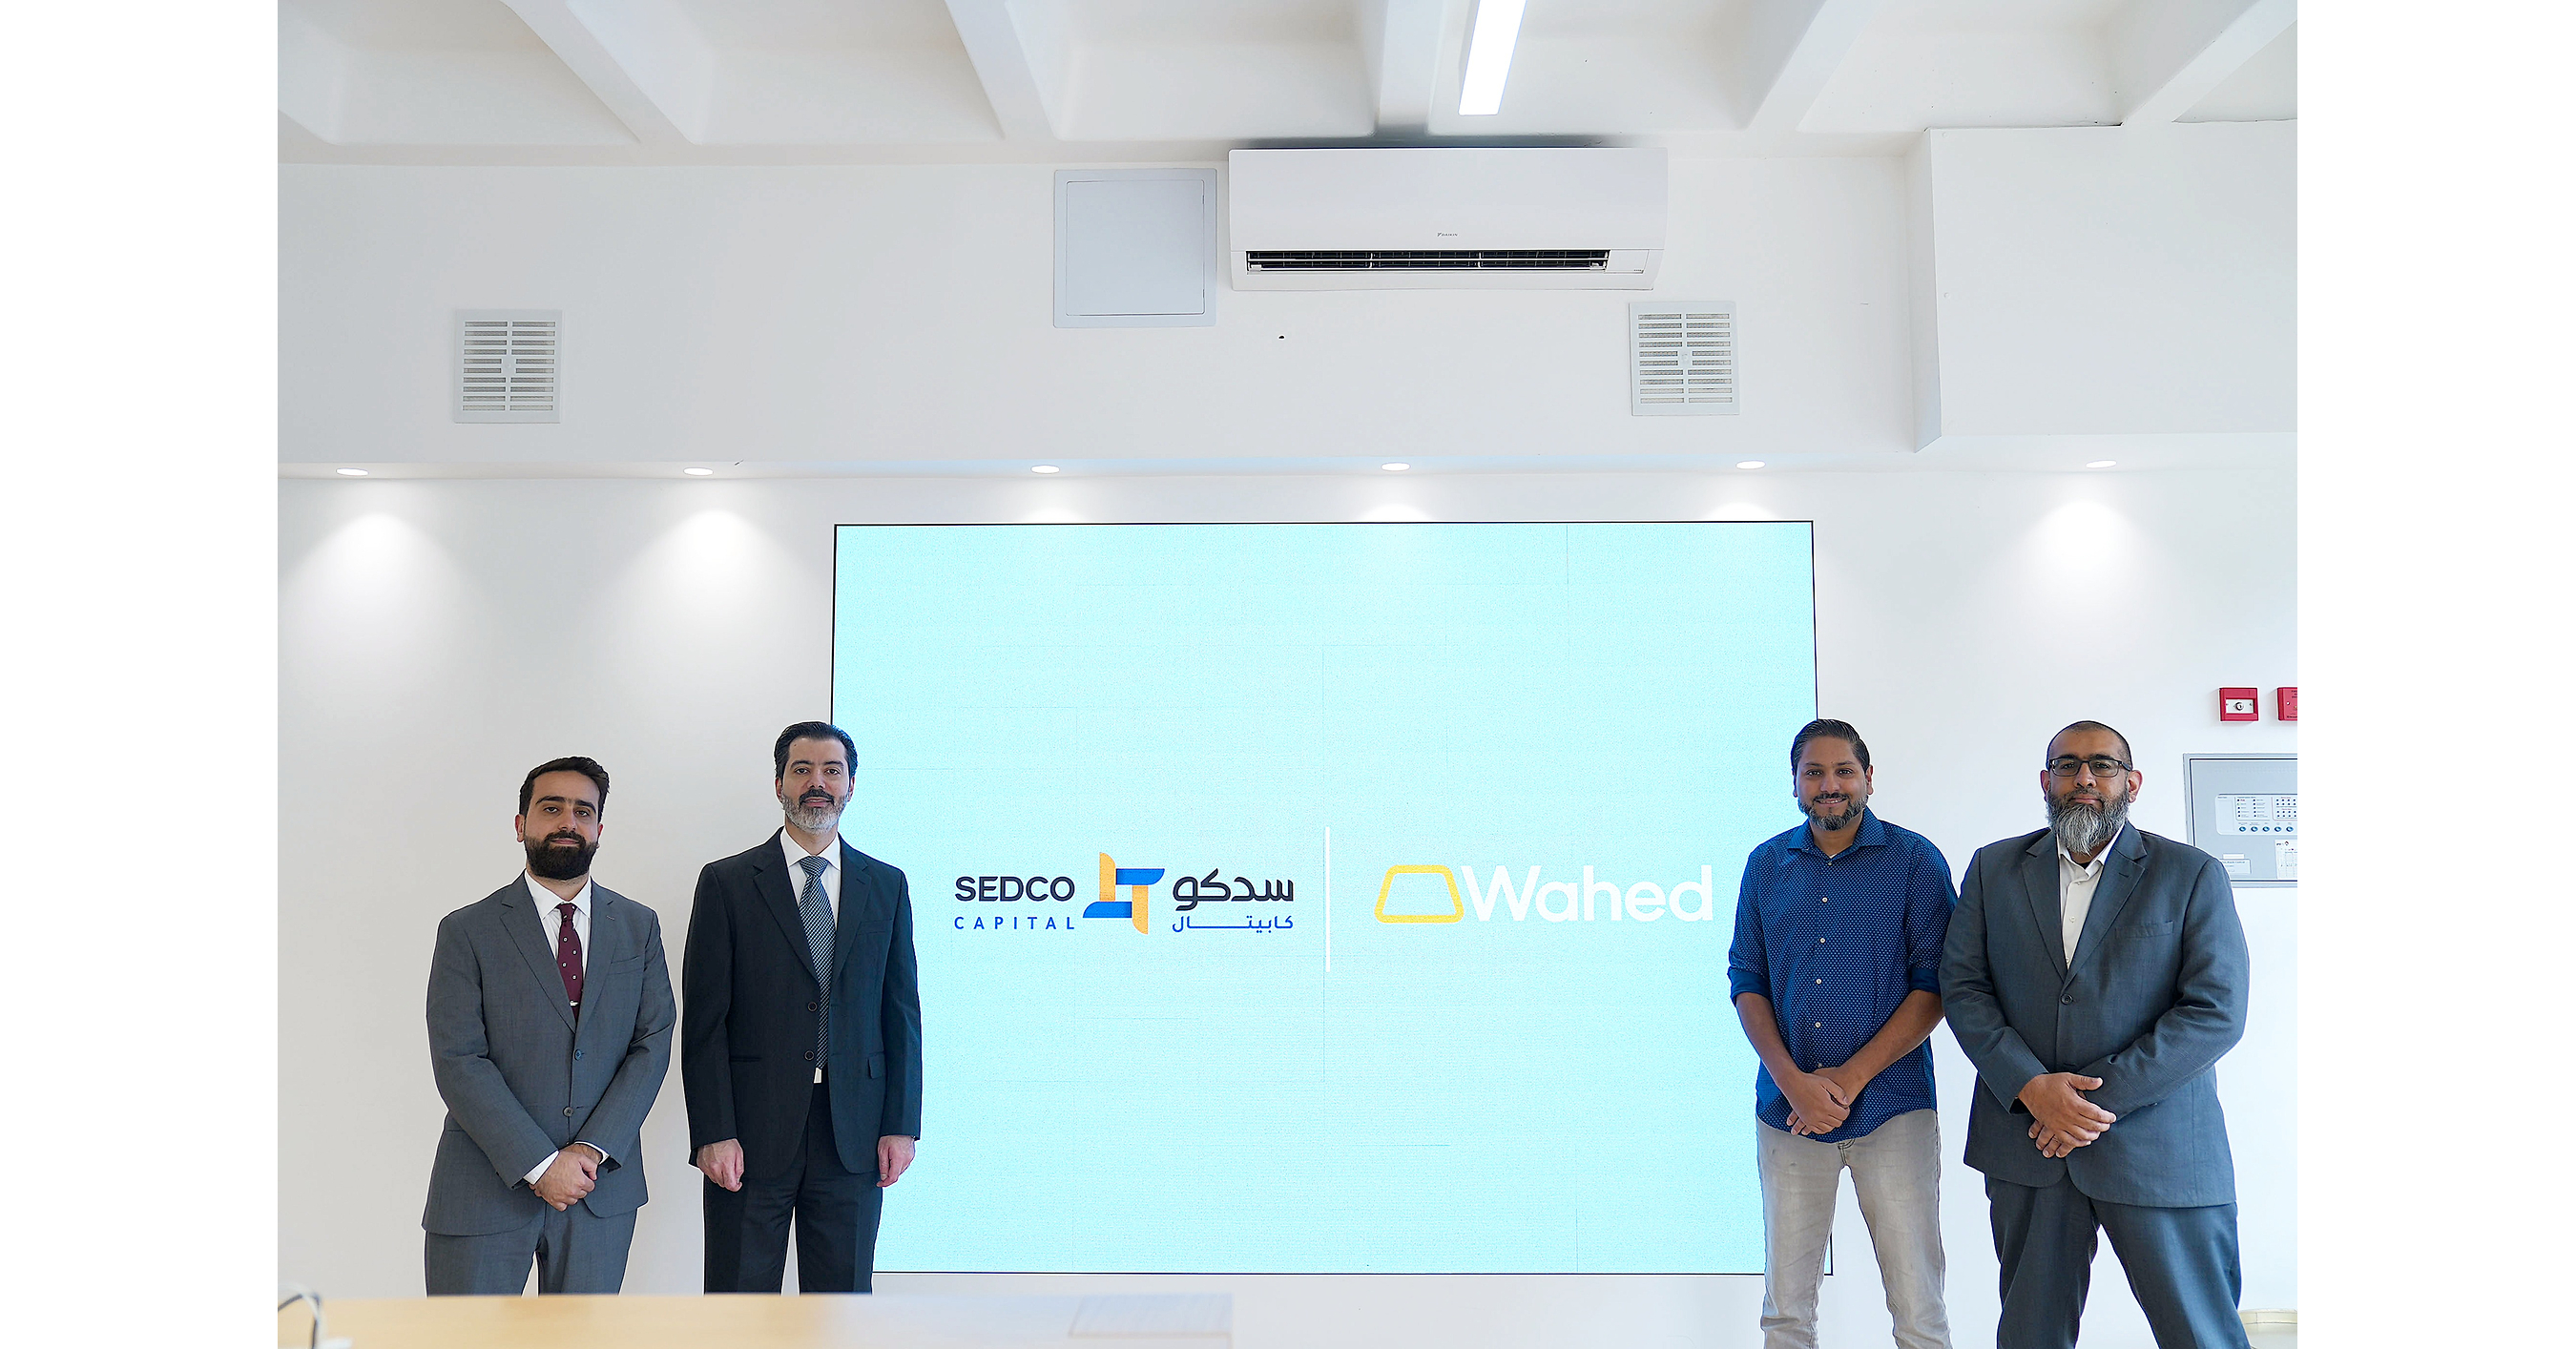
SEDCO Capital and Islamic fintech Wahed plan to launch a publicly offered, Shariah-compliant real estate investment suite focused on Makkah and Madinah, combining SEDCO's Saudi property capabilities with Wahed's 500,000-investor global platform. The offering targets demand tied to Saudi Vision 2030, which aims to enable 30 million annual Umrah pilgrims by 2030, supporting investment in accommodation, hospitality, retail and residential assets. SEDCO manages more than SAR50 billion ($13.5 billion) in assets, while Wahed manages or administers over $2 billion.
Analysis
The investable implication is less a near-term earnings event than incremental price discovery for scarce, pilgrimage-linked Saudi real estate. If the vehicle succeeds in aggregating offshore retail demand, it could lower the required return on stabilized hotel, retail and mixed-use assets in the two cities; listed owners/operators with embedded land banks and development inventory—Jabal Omar (4250), Makkah Construction (4100), Taiba (4090) and Dur Hospitality (4010)—would be the most logical read-through beneficiaries. The second-order risk is that easier capital access raises land and construction costs faster than room-rate growth, favoring completed, cash-generative assets over developers still funding multi-year build-outs.
This is not yet a clean catalyst for Saudi equities: fund size, fee structure, asset-acquisition pipeline, investor eligibility, liquidity terms and regulatory approval remain undisclosed. A retail-distributed product can bring sticky inflows, but it may also be pro-cyclical—redemption pressure during a tourism slowdown or Saudi risk-off episode would force valuation marks lower precisely when private-market liquidity is weakest. Over the next 1-3 months, watch for a formal product filing, cornerstone commitments and identified seed assets; over 6-18 months, the relevant confirmation is sustained RevPAR, occupancy and operating-cash-flow growth rather than announced visitor targets.
Consensus may overvalue the distribution narrative. Wahed's client base does not automatically translate into deployable cross-border capital, particularly where suitability, currency conversion, local ownership and fund-subscription constraints apply. The more durable opportunity is likely in the listed asset owners if the new suite purchases existing stabilized assets at cap rates below public-market implied values; absent disclosed acquisition terms, there is no basis to assume an immediate NAV uplift.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Key Decisions for Investors
- No immediate position on the partnership announcement. Create a 1-3 month alert for the fund's regulatory filing, target size, leverage limit, redemption terms and seed-asset list; only underwrite a listed-equity read-through once those disclosures establish meaningful capital relative to the relevant local asset market.
- Build a relative-value watchlist: long Taiba (4090) or Makkah Construction (4100) versus short Dar Al Arkan (4300) if pilgrimage-market operating metrics accelerate. Prefer the owner/operator leg where evidence shows stabilized cash-flow growth; use a 6-12 month horizon and exit if occupancy/RevPAR fail to improve for two reporting periods or net debt rises faster than operating income.
- Avoid chasing Jabal Omar (4250) solely on potential fund demand. Its upside is most sensitive to development execution, financing costs and asset monetization; consider it only after a disclosed transaction validates asset pricing. A financing delay, widening Saudi credit spreads, or project-cost inflation would falsify the bullish NAV-re-rating thesis.
- Monitor SAR funding conditions and Saudi hotel supply additions as the key macro hedge. If new room inventory materially outpaces realized pilgrimage growth, completed-asset valuations and REIT-like vehicles could de-rate despite strong headline visitor numbers; that would favor a defensive bias toward lower-leverage operators over development-heavy names.
More News
- Are global oil reserves sufficient to withstand renewed US-Iran war?
- France is flashing euro crisis signals. This time, the fault lines are different
- OpenAI Trims Target Value & Volvo Cars Cuts 2,500 Jobs
- PG&E’s CEO says AI is ‘the best thing that could’ve ever happened to the grid’
- ‘They are trying to intimidate us’: Indonesia’s Prabowo remains defiant in the face of an MSCI double downgrade
- Volvo Cars shares plunge 25% amid China sales slump and fresh job cuts