
Taylor Guitars Introduces Next Generation 12-Fret Grand Concert Models
Source: PRWeb
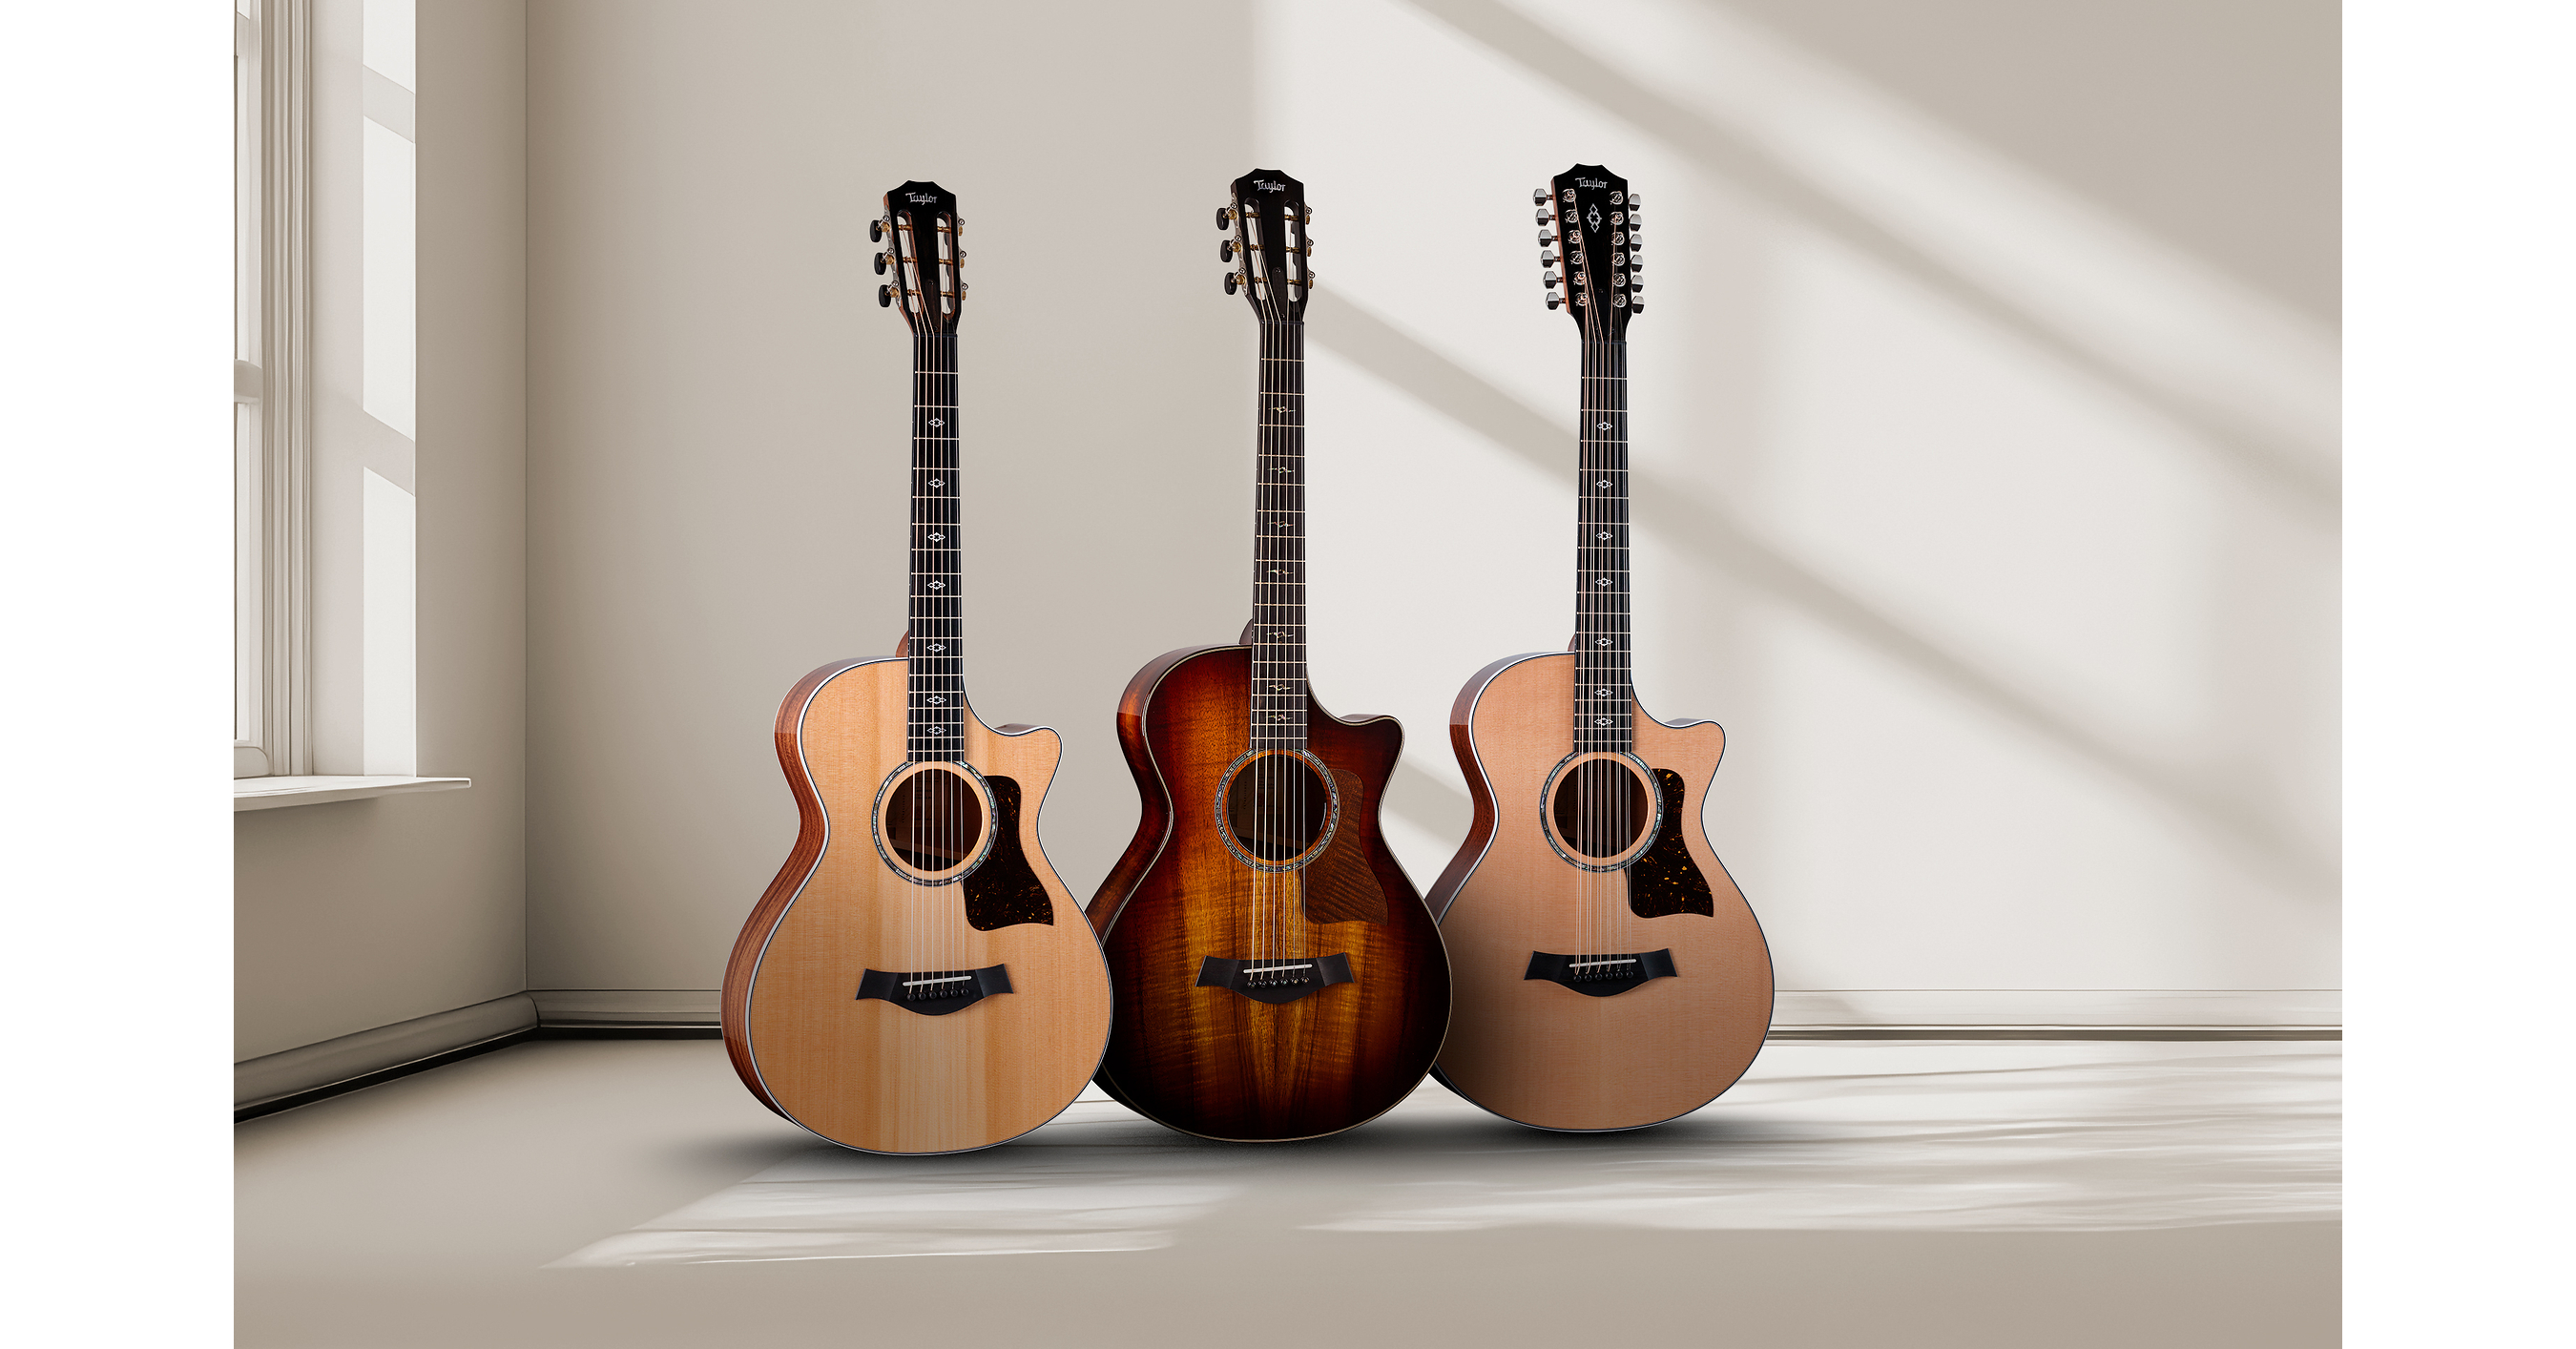
Taylor Guitars launched five Next Generation 12-fret Grand Concert models (PS12ce, K22ce, 712ce, 552ce 12-string, 512ce), emphasizing new “Next-Gen” features like Action Control Neck™, scalloped V-Class® bracing, and Claria™ electronics. The new guitars are available now through authorized dealers worldwide starting at $2,999, with the 12-string 552ce positioned as a more approachable entry into the 12-string sound. Overall, the release is a positive product/innovation update but is unlikely to be material to broader markets.
Analysis
This reads more like brand-defense and mix-management than a true demand inflection. The economic read-through is that premium, high-ASP discretionary goods can still command attention in a softening consumer backdrop, but launches of this type mostly reshuffle share within a niche rather than expand the category. The likely near-term beneficiary is the dealer channel, which gets fresh inventory and a reason to reset marketing; the risk is that channel fill shows up before sell-through, leaving secondary prices and turns as the real arbiter of success.
The second-order issue is cannibalization: a premium refresh can protect pricing on existing upper-tier models, but if the new SKU ladder is too broad it can pull demand from adjacent guitars instead of bringing in new buyers. Over 1-3 months, the key signal is not launch enthusiasm but preorder velocity versus inventory buildup at authorized dealers. Over 6-18 months, the question is whether this materially lifts average selling price and mix or simply creates another high-end variant with limited volume.
For public-market investors, the direct impact is essentially nil, so forcing a trade is low quality. The only plausible read-through is to premium discretionary sentiment more broadly: if consumers continue to buy $3k+ instruments, that slightly supports the idea that affluent hobbyist spend is holding up, which would be incrementally constructive for higher-end discretionary names and specialty retail exposure. But absent evidence of meaningful unit acceleration, the move is better treated as a watch item than a catalyst.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Key Decisions for Investors
- No trade in GOOGL / TSTS / TWODY today; there is no credible earnings linkage, and this headline does not change estimates or multiple assumptions. Reassess only if a real distribution/traffic channel is identified.
- Watch XLY vs XLP over the next 1-3 months as a broad consumer-spend proxy, but do not act on this launch alone. The risk/reward is poor unless channel data confirm premium discretionary resilience.
- If you want optional exposure to a stronger premium-consumer tape, consider a small tactical long XLY on a pullback rather than chasing strength; invalidate the idea if upcoming retail sales or consumer confidence prints weaken materially.
- Set a channel-check alert: if dealer inventory turns deteriorate or secondary-market discounts emerge over the next quarter, treat this as cannibalization rather than category growth and avoid any discretionary beta exposure.
More News
- There’s $33 Trillion in Stock Gains Riding on the Future of AI
- Nissan eyes increasing U.S. production as new Rogue hybrid launches
- Volkswagen woes deepen as blue-chip index exit follows latest profit warning
- SoftBank Seeking Over $11 Billion in Junk Bond Deal for OpenAI Investment
- Eurosystem brings central bank money to tokenised finance
- Can the US win the AI cold war with China?