
NOVVA Group pozyskuje od ABO Energy portfel projektów OZE o mocy 3,17 GW na potrzeby globalnej infrastruktury AI
Source: PR Newswire
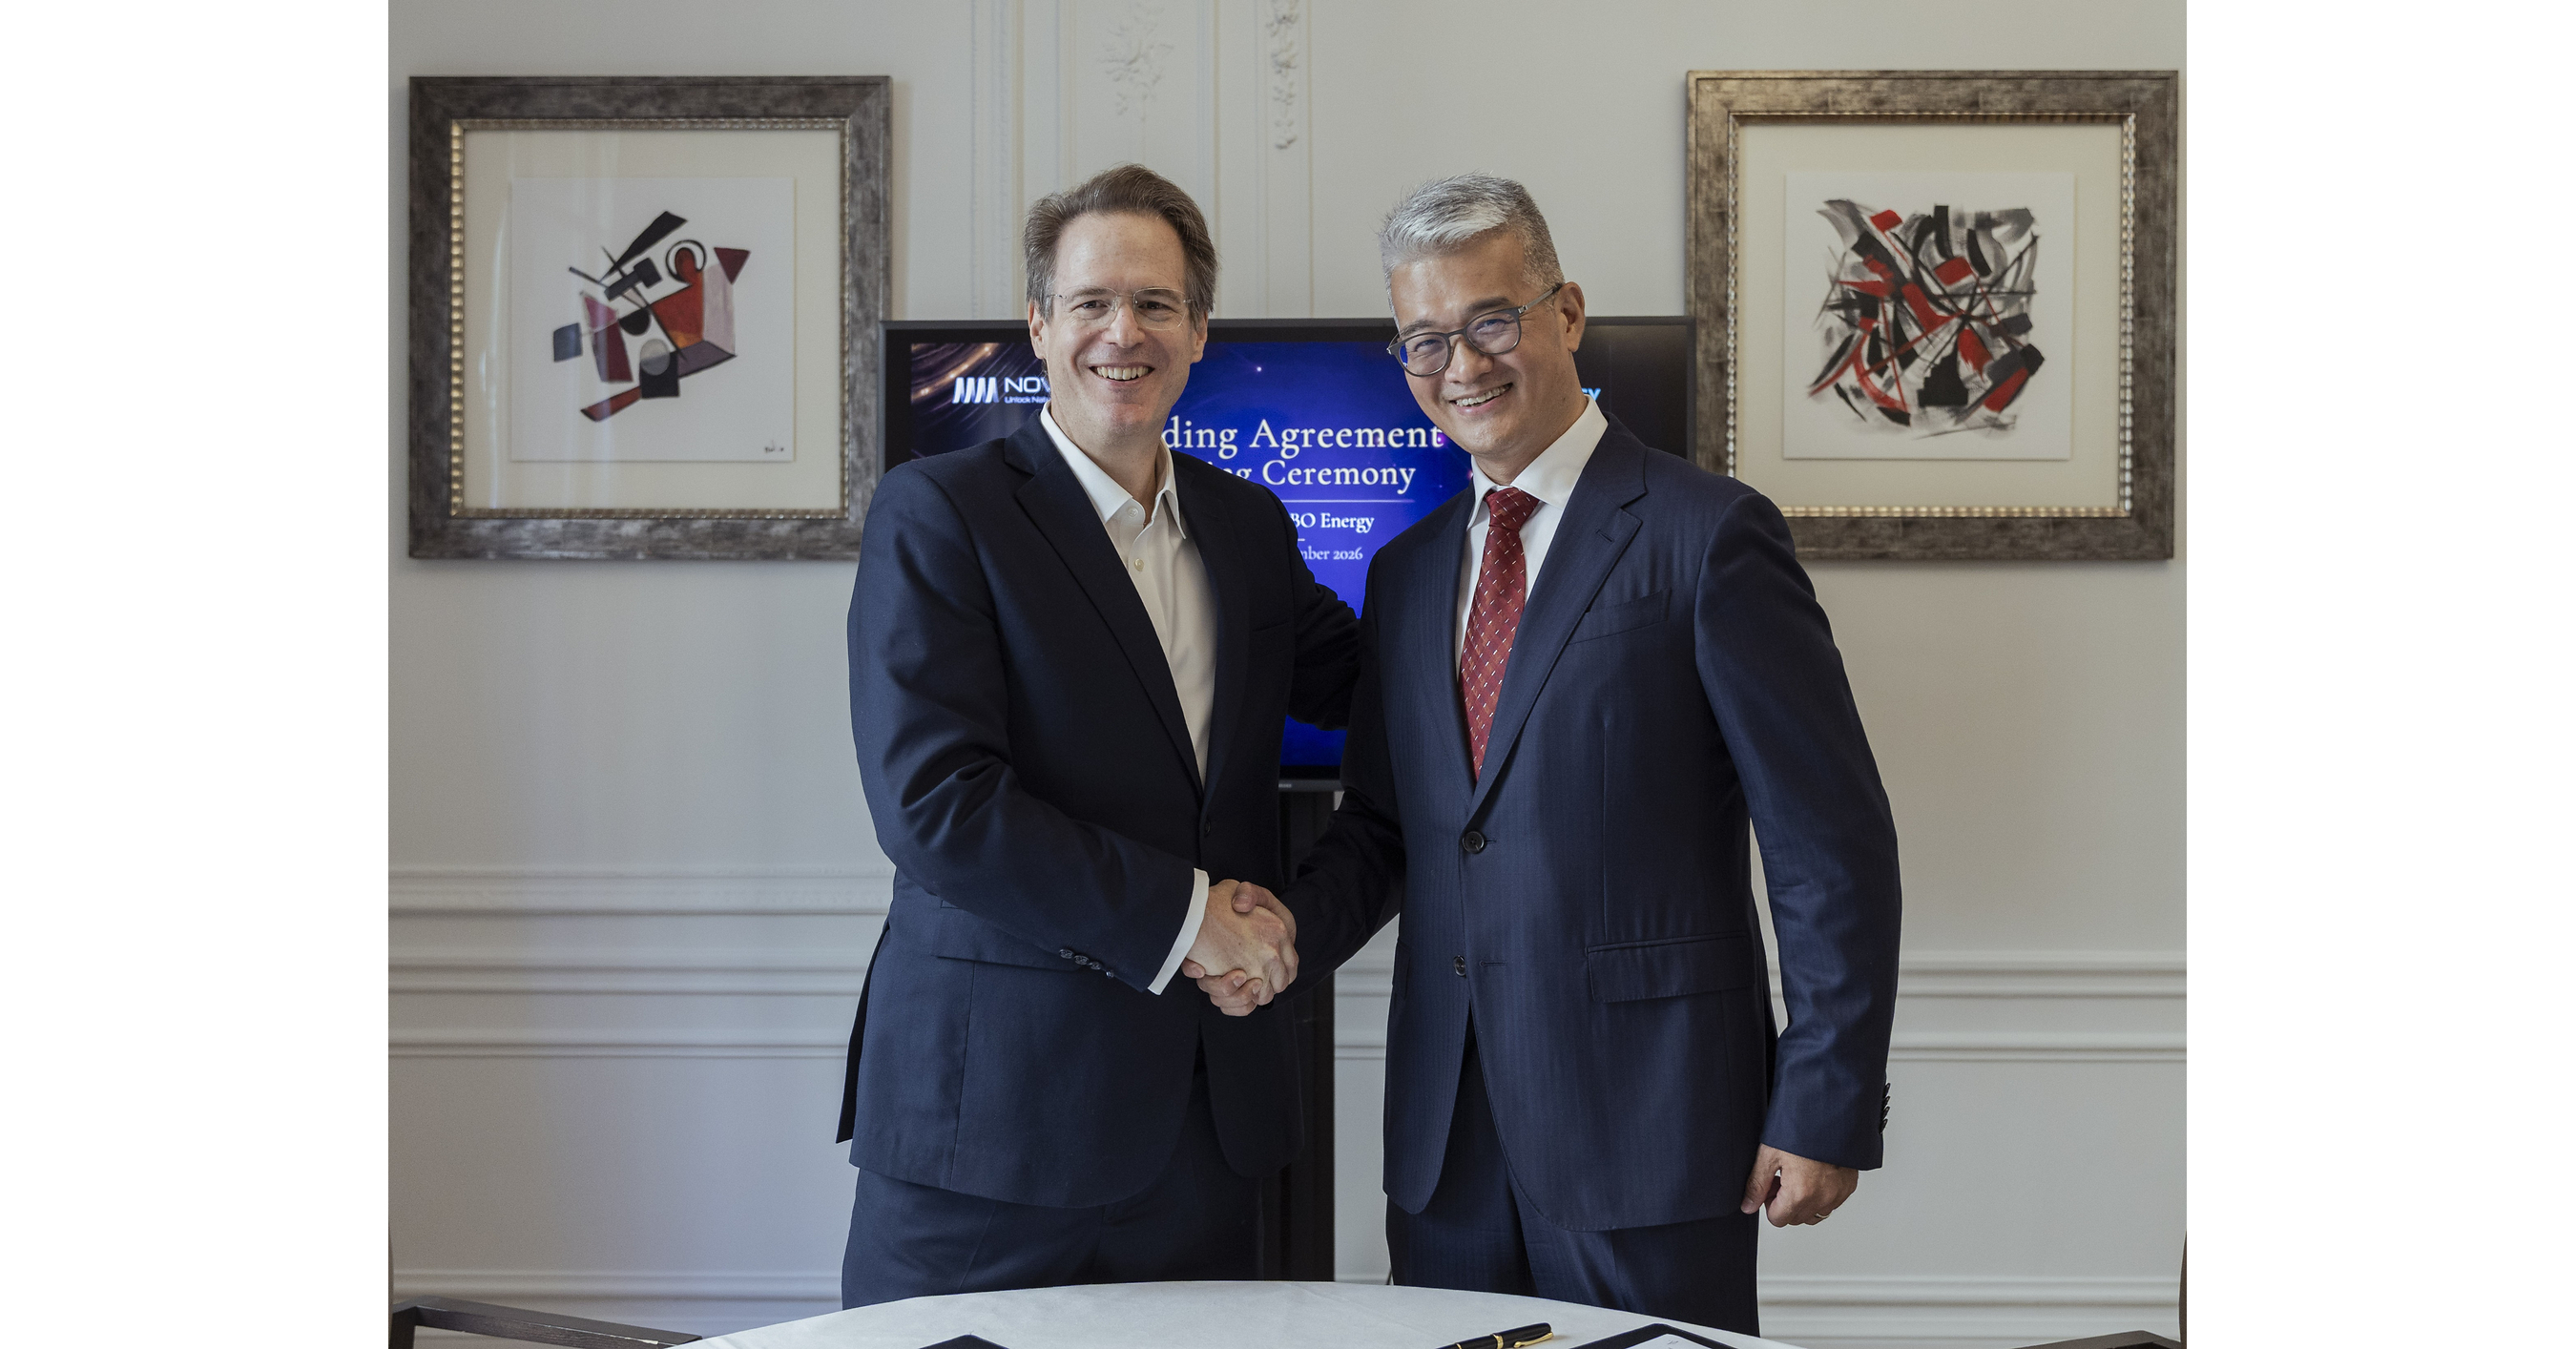
Novva signed a binding framework agreement to acquire ABO Energy's 3.17 GW renewable-energy project portfolio in Argentina, materially expanding its power supply pipeline for AI data-center infrastructure. The transaction follows Novva's earlier acquisition of three Colombian solar projects from ABO Energy and accelerates its Latin American expansion. The portfolio of wind and solar assets is intended to provide financeable, predictable clean-power capacity for next-generation data centers and powered-land developments.
Analysis
For AB9, the valuation question is not headline gigawatts but whether the transaction converts a long-dated, capital-intensive development inventory into near-term cash at an attractive price. A sale of permitted or advanced-stage projects can release development capital, reduce construction and merchant-power exposure, and support a higher cash-conversion multiple; however, no purchase price, stage-of-development split, closing conditions, or retained EPC/O&M economics have been disclosed. Until these terms are known, the announcement is more a pipeline-validation signal than an earnings upgrade.
The buyer's AI-infrastructure framing should be treated cautiously in Argentina: renewable generation does not itself solve the data-center constraint without firm transmission access, storage, contracted offtake, and hard-currency financing. The likely bottleneck shifts to grid interconnection and sovereign/FX risk, potentially increasing the value of projects with secured permits and transmission rights while impairing nominal MW that remain early stage. This could modestly improve competitive positioning for established Argentine power owners such as CEPU and PAM if new renewable build-out tightens access to transmission capacity, but it does not yet establish incremental demand for their output.
Near-term sentiment in AB9 can remain constructive on evidence of portfolio monetization, while the 1-3 month catalyst path is signing/closing, disclosed proceeds, and any confirmation that ABO retains engineering, construction, or asset-management revenue. Over 6-18 months, repeated asset recycling could lower AB9's balance-sheet intensity and de-risk its development model; the contrary outcome is that project sales reflect difficulty financing construction in volatile emerging markets. The thesis is falsified if disclosed consideration is materially below implied late-stage development value, closing is delayed by approvals/financing, or AB9 cuts its remaining pipeline or margin outlook.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.68
Ticker Sentiment
Key Decisions for Investors
- Maintain AB9 on a positive watch list rather than initiate solely on the release. Upgrade to a tactical 1-3 month long only after consideration, development stage, and closing timetable are disclosed; require proceeds sufficient to demonstrate a meaningful premium to carrying value or a visible reduction in net debt. Risk: the framework agreement may not close or may carry limited economics for ABO.
- For investors already long AB9, retain exposure through the next company update but cap position sizing until transaction terms are public. Take risk down if management characterizes the assets as early-stage or if retained EPC/O&M revenue is absent, since the transaction would then be primarily a one-off pipeline disposal rather than recurring margin creation.
- Monitor CEPU and PAM for second-order transmission scarcity rather than buying immediately. A long can be considered only if Argentine grid-capacity awards, PPAs, or capacity-price revisions validate that renewable additions are tightening dispatch/interconnection economics; sovereign-risk repricing and peso controls remain the dominant downside variables.
- Do not express the AI-power theme through broad data-center or semiconductor longs from this event. The investable catalyst is project monetization and grid execution, not a verified incremental compute-load contract; confirmation of bankable offtake, storage, and transmission rights would be required before assigning strategic AI-infrastructure value.
More News
- 'Hostile act': Trump threatens EU with tariffs over Canada associate-membership proposal
- US military claims Strait of Hormuz remains open amid ongoing blockade
- Berkshire May Boost Japan Trading House Holdings, Itochu Says
- US official says upcoming spectrum auctions could generate more than $100 billion
- Fed delivers its first hike in 3 years. Plus, what's moving Starbucks and GE Vernova
- Fed’s Warsh lays out forces driving up bond yields
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- The $4.7 Trillion Bet: When Does AI Capex Become AI Revenue?
- Equity Research Automation Statistics: A 2026 Evidence Check